
Regional banking company WesBanco (NASDAQ: WSBC) fell short of the market’s revenue expectations in Q3 2026 as sales rose 4.3% year on year to $272.7 million. Its non-GAAP profit of $0.89 per share was 1.6% above analysts’ consensus estimates.
Is now the time to buy WesBanco? Find out by accessing our full research report, it’s free.
WesBanco (WSBC) Q3 2026 highlights:
- Net Interest Income: $226.9 million vs analyst estimates of $229.4 million (4.7% year-on-year growth, 1.1% miss)
- Net Interest Margin: 3.6% vs analyst estimates of 3.6% (in line)
- Revenue: $272.7 million vs analyst estimates of $275.3 million (4.3% year-on-year growth, 0.9% miss)
- Efficiency Ratio: 52.2% vs analyst estimates of 55.6% (339.9 basis point beat)
- Adjusted EPS: $0.89 vs analyst estimates of $0.88 (1.6% beat)
- Tangible Book Value per Share: $22.73 vs analyst estimates of $23.31 (8.5% year-on-year growth, 2.5% miss)
- Market Capitalization: $3.61 billion
"Our third quarter results reflect the continued strength of WesBanco's disciplined growth strategy and relationship-focused banking model," said Jeff Jackson, President and Chief Executive Officer. "Year-to-date adjusted diluted earnings per share increased nearly 7%, while we maintained solid positive operating leverage and generated strong organic loan growth that more than offset elevated commercial real estate payoffs. With strong momentum across our franchise and a robust commercial pipeline, we believe we are well positioned to build on that performance in the quarters ahead."
Company overview
Tracing its roots back to 1870 in West Virginia, WesBanco (NASDAQ: WSBC) is a bank holding company that provides retail and commercial banking, trust services, insurance, and investment products through its subsidiaries across several Midwestern and Mid-Atlantic states.
Sales growth
Net interest income and fee-based revenue are the two pillars supporting bank earnings. The former captures profit from the gap between lending rates and deposit costs, while the latter encompasses charges for banking services, credit products, wealth management, and trading activities. Over the last five years, WesBanco grew its revenue at a solid 12.2% compounded annual growth rate. Its growth beat the average banking company and shows its offerings resonate with customers.
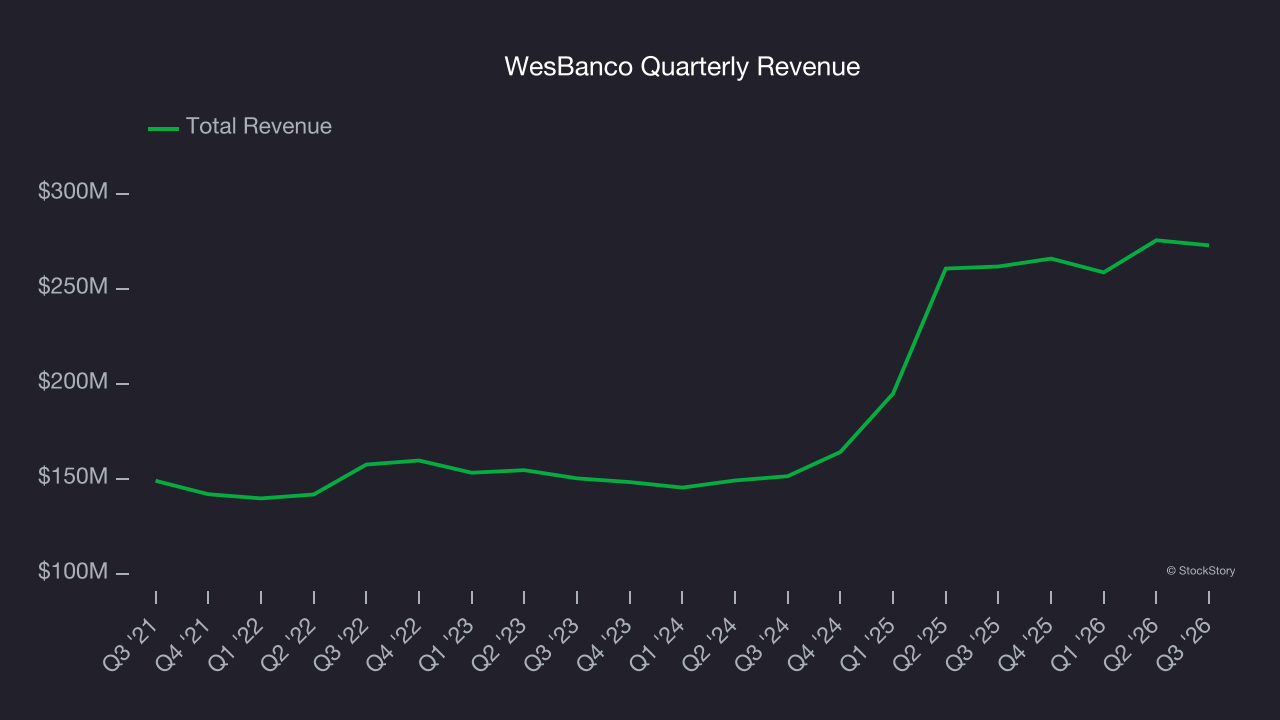
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. WesBanco’s annualized revenue growth of 34.4% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 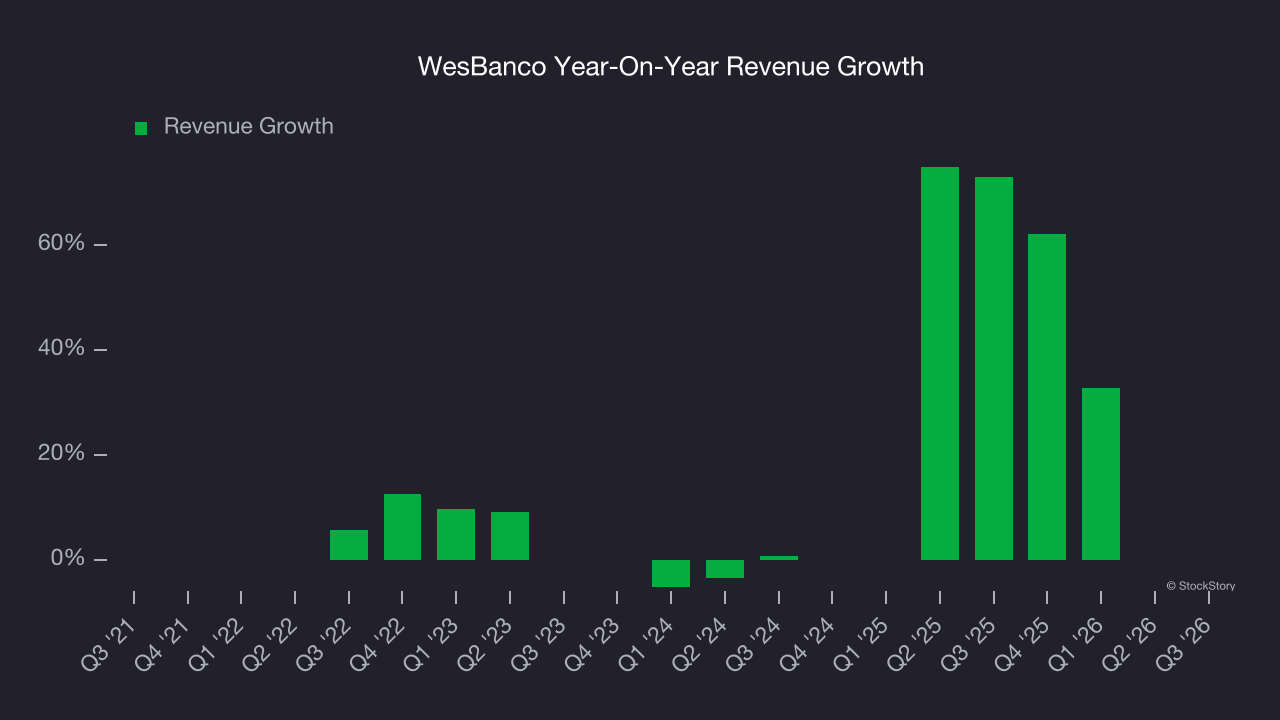 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, WesBanco’s revenue grew by 4.3% year on year to $272.7 million, falling short of Wall Street’s estimates.
Net interest income made up 82.7% of the company’s total revenue during the last five years, meaning WesBanco barely relies on non-interest income to drive its overall growth.
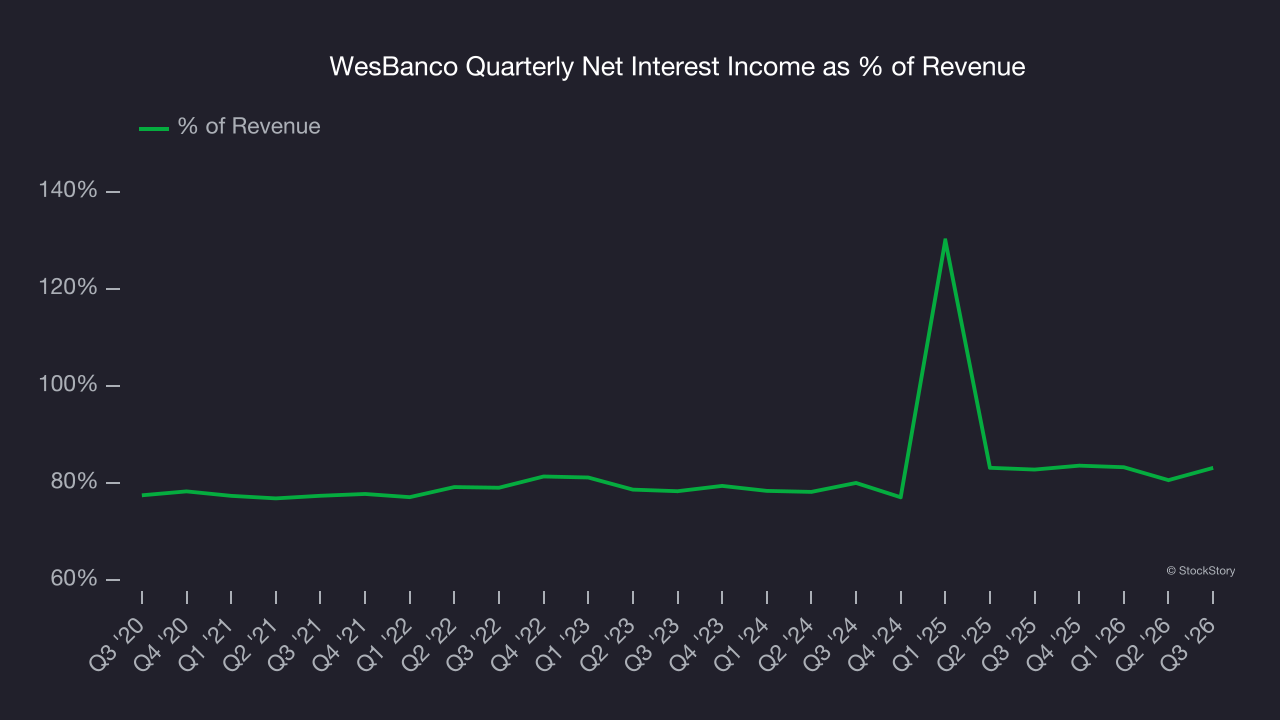
Our experience and research show the market cares primarily about a bank’s net interest income growth as non-interest income is considered a lower-quality and non-recurring revenue source.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Tangible book value per share (TBVPS)
Banks profit by intermediating between depositors and borrowers, making them fundamentally balance sheet-driven enterprises. Market participants emphasize balance sheet quality and sustained book value growth when evaluating these institutions.
This is why we consider tangible book value per share (TBVPS) the most important metric to track for banks. TBVPS represents the real, liquid net worth per share of a bank, excluding intangible assets that have debatable value upon liquidation. EPS can become murky due to acquisition impacts or accounting flexibility around loan provisions, and TBVPS resists financial engineering manipulation.
WesBanco’s TBVPS was flat over the last five years. The last two years unveil a similar pattern as TBVPS was roughly flat at $22.73 per share.
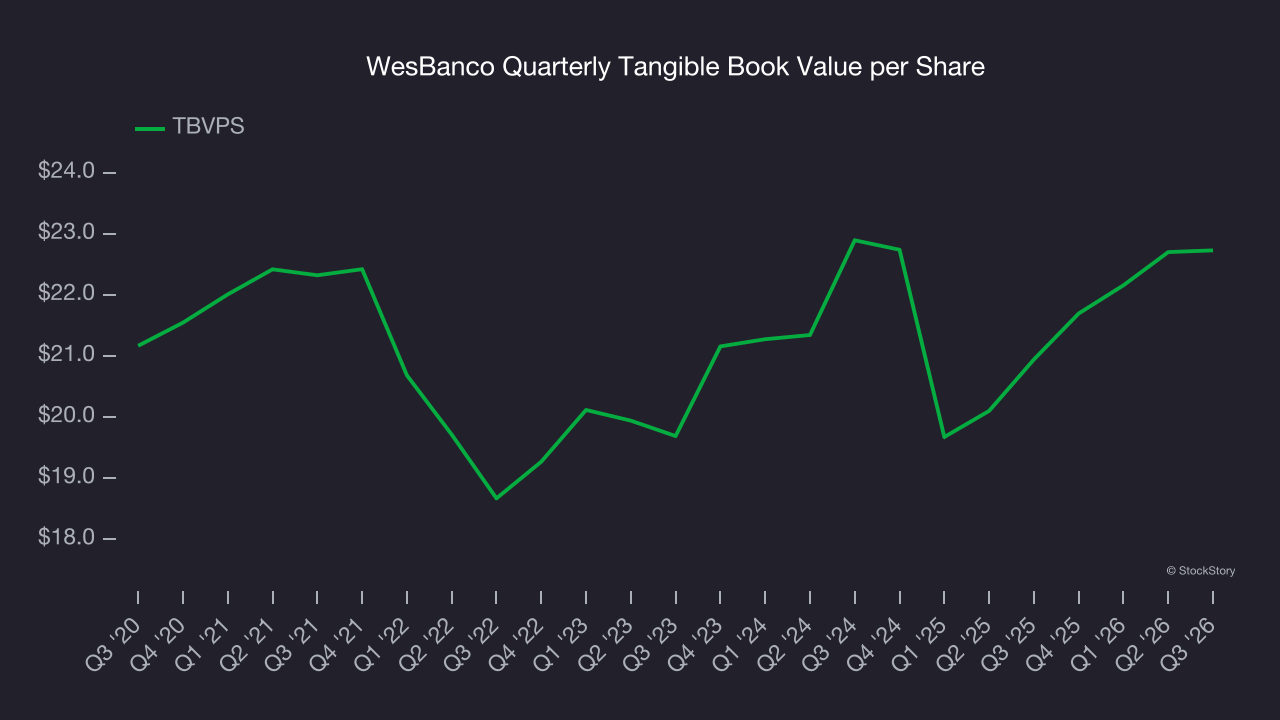
Over the next 12 months, Consensus estimates call for WesBanco’s TBVPS to grow by 13.1% to $25.70, decent growth rate.
Key takeaways from WesBanco’s Q3 results
We struggled to find many positives in these results. Its tangible book value per share missed and its net interest income fell slightly short of Wall Street’s estimates. Overall, this quarter could have been better. The stock remained flat at $37.61 immediately following the results.
The latest quarter from WesBanco’s wasn’t that good. One earnings report doesn’t define a company’s quality, though, so let’s explore whether the stock is a buy at the current price. What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).