
Hawaiian banking company First Hawaiian (NASDAQ: FHB) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 1.7% year on year to $230.2 million. Its GAAP profit of $0.52 per share was 10.2% below analysts’ consensus estimates.
For more on First Hawaiian Bank, read our free full research report.
First Hawaiian Bank (FHB) Q3 2026 highlights:
- Net Interest Income: $174.1 million vs analysts’ consensus estimates of $174.3 million (2.8% year-on-year growth, in line)
- Net Interest Margin: 3.3% vs analysts’ consensus estimates of 3.3% (in line)
- Revenue: $230.2 million vs analysts’ consensus estimates of $228.7 million (1.7% year-on-year growth, 0.7% beat)
- Efficiency Ratio: 69.2% vs analysts’ consensus estimates of 56.6% (1,259.7 basis point miss)
- EPS (GAAP): $0.52 vs analysts’ consensus estimates of $0.58 (10.2% miss)
- Tangible Book Value per Share: $14.97 vs analysts’ consensus estimates of $15.32 (6.5% year-on-year growth, 2.3% miss)
- Market Capitalization: $3.18 billion
“I’m pleased with the solid earnings we delivered this quarter and the continued trust our customers place in us,” said Bob Harrison, Chairman, President and Chief Executive Officer. “Our deposit growth in a competitive market reflects the strength of those relationships, and our balance sheet is well positioned to benefit from rising interest rates. As we prepare for the Tri Counties Bank acquisition, we’re focused on building on that foundation and the growth opportunities ahead.”
Revenue growth
Two primary revenue streams drive bank earnings. While net interest income, which is earned by charging higher rates on loans than paid on deposits, forms the foundation, fee-based services across banking, credit, wealth management and trading operations provide additional income. Over the last five years, First Hawaiian Bank grew its revenue at a sluggish 4.4% compounded annual growth rate. This was below our standard for the banking sector.
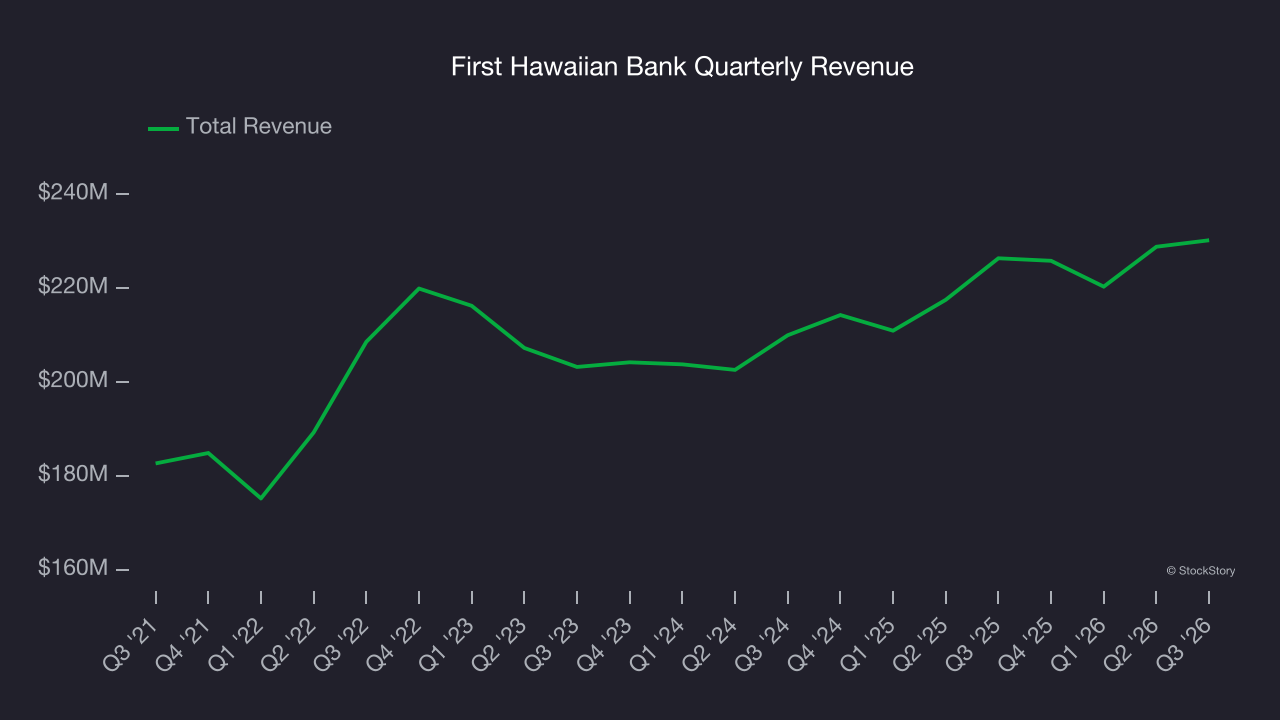
Long-term growth matters most, but within financials, a half-decade historical view may miss recent interest rate changes, market returns and industry trends. First Hawaiian Bank’s annualized revenue growth of 5% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 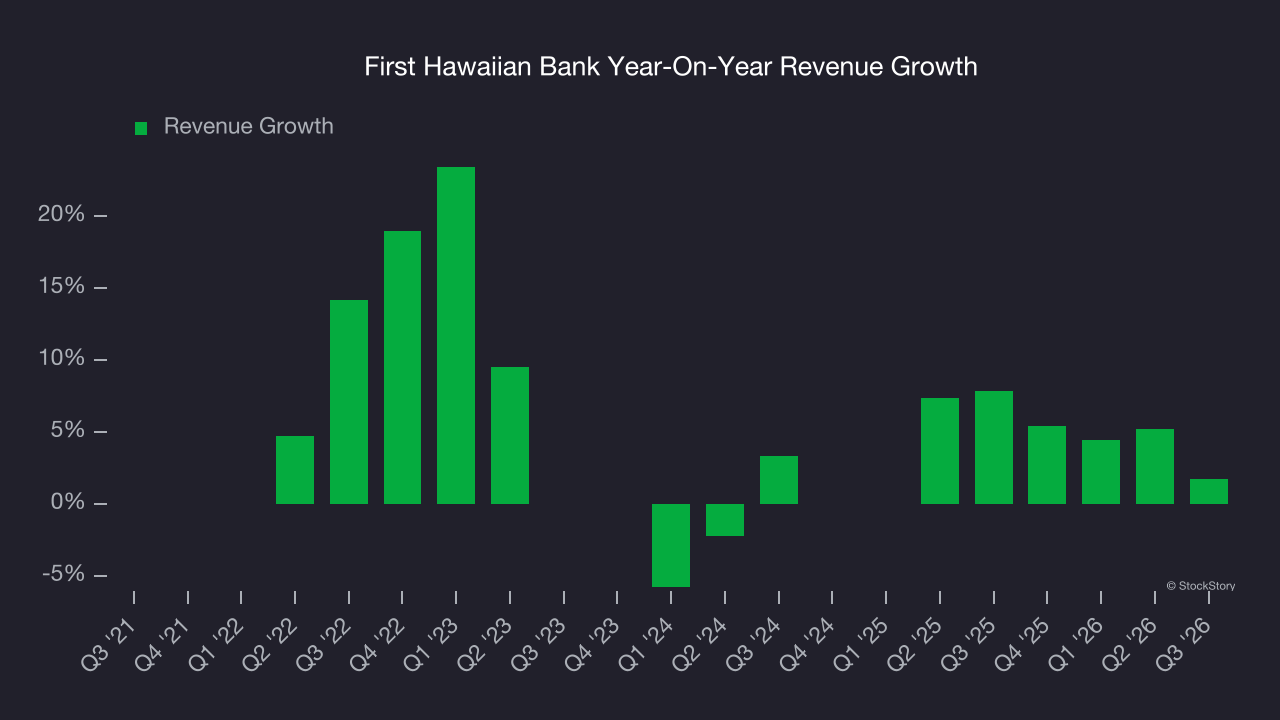 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, First Hawaiian Bank reported modest year-on-year revenue growth of 1.7% but beat Wall Street’s consensus estimates by 0.7%.
Net interest income made up 75.9% of the company’s total revenue during the last five years, meaning lending operations are First Hawaiian Bank’s largest source of revenue.
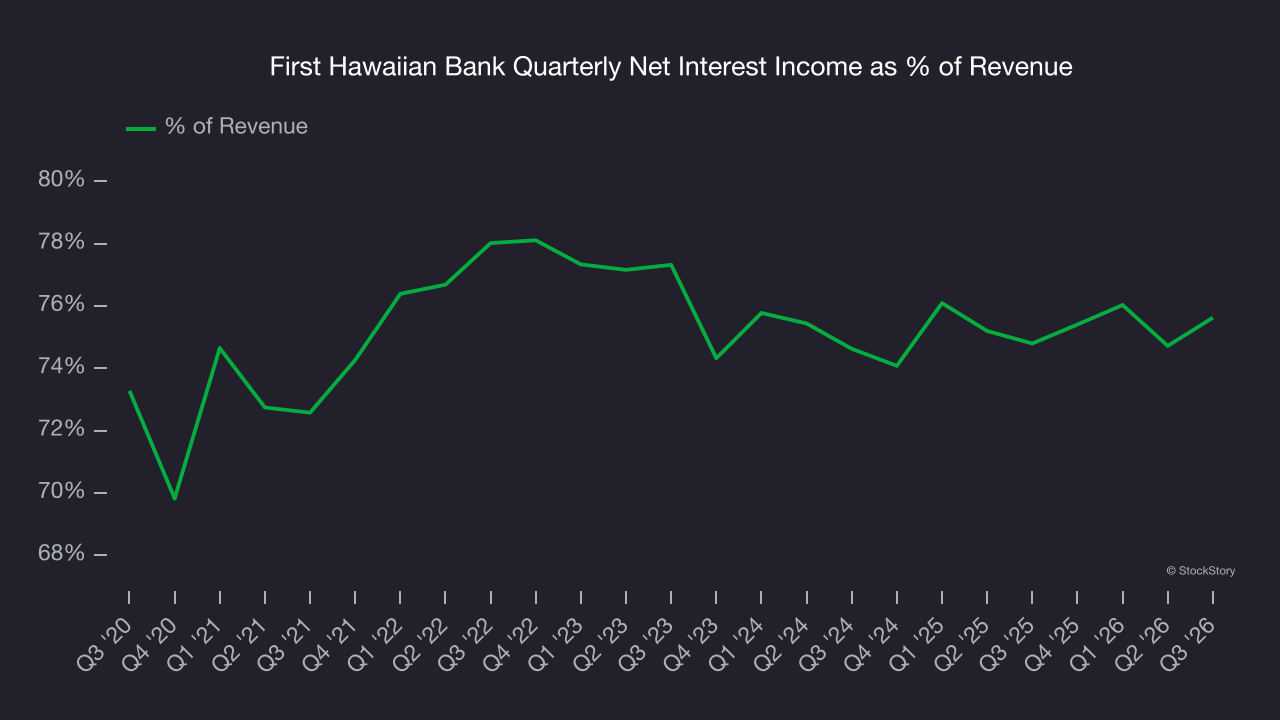
Net interest income commands greater market attention due to its reliability and consistency, whereas non-interest income is often seen as lower-quality revenue that lacks the same dependable characteristics.
Tangible book value per share (TBVPS)
Banks are balance sheet-driven businesses because they generate earnings primarily through borrowing and lending. They’re also valued based on their balance sheet strength and ability to compound book value (another name for shareholders’ equity) over time.
This explains why tangible book value per share (TBVPS) is a leading banking metric. TBVPS excludes intangible assets whose value can be uncertain, providing a more reliable measure of tangible net worth per share. Traditional metrics like EPS are helpful but can be distorted by M&A activity and loan loss accounting rules.
First Hawaiian Bank’s TBVPS grew at a sluggish 2.3% annual rate over the last five years. However, TBVPS growth has accelerated recently, rising by 7.6% annually over the last two years from $12.92 to $14.97 per share.
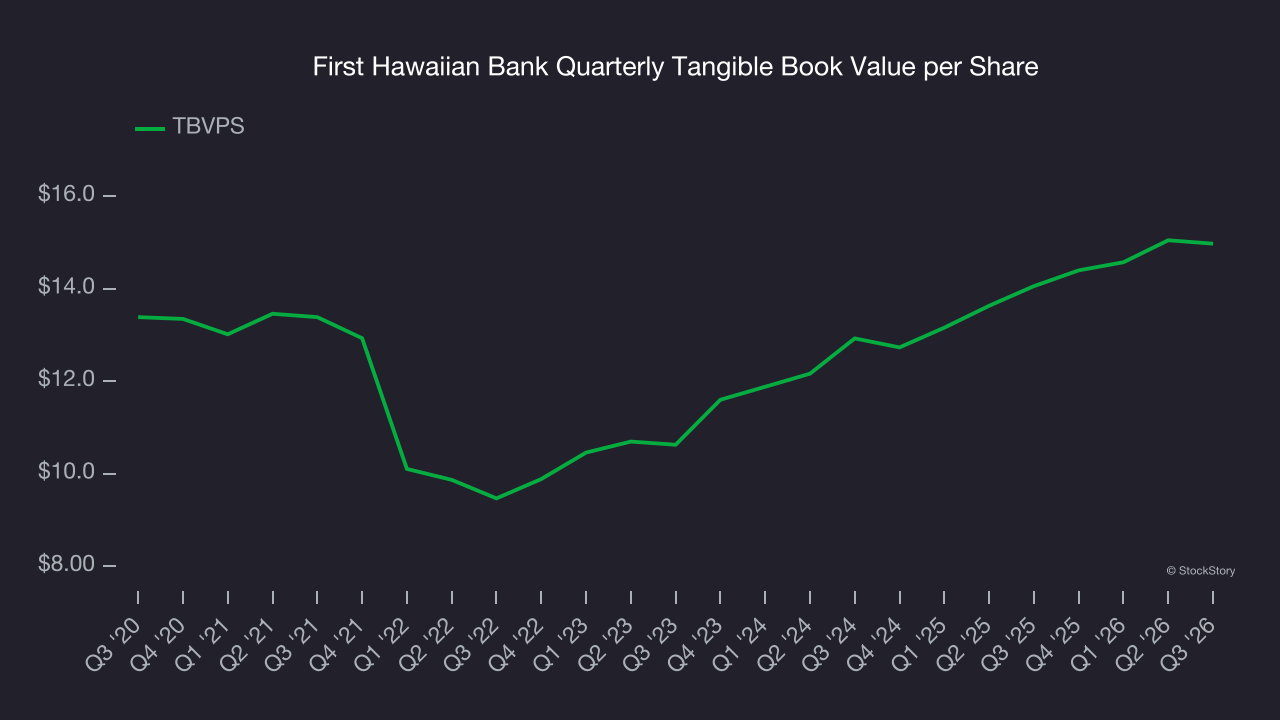
Over the next 12 months, consensus estimates call for First Hawaiian Bank’s TBVPS to grow by 6.7% to $15.98, a weak growth rate.
Key takeaways from First Hawaiian Bank’s Q3 results
First Hawaiian Bank’s narrow revenue beat was a positive in an otherwise softer quarter: EPS missed consensus estimates, and tangible book value per share also fell short of Wall Street’s consensus. Shares fell 4.8% to $24.89 immediately after the results.
First Hawaiian Bank’s latest quarter was underwhelming. One earnings report doesn’t define a company’s quality, though, so assessing whether the stock is a buy at the current price requires a broader look. The latest quarter matters, but longer-term business quality and valuation matter more when deciding whether to invest. For more on those factors, read the full research report here (it’s free).