
Dental technology company Align Technology (NASDAQ: ALGN) beat Wall Street’s revenue expectations in Q3 2026, with revenue rising 1.9% year on year to $1.01 billion. On the other hand, next quarter’s revenue guidance of $1.01 billion was less impressive, coming in 3.7% below analysts’ consensus estimates. Its non-GAAP profit of $2.80 per share was 1.3% above analysts’ consensus estimates.
For more on Align Technology, read our free full research report.
Align Technology (ALGN) Q3 2026 highlights:
- Revenue $1.01 billion vs S&P analysts’ consensus estimates of $1.00 billion (1.9% year-on-year growth, 1.1% beat)
- Adjusted EPS $2.80 vs S&P analysts’ consensus estimates of $2.76 (1.3% beat)
- Adjusted operating income $247.8 million vs analysts’ consensus estimates of $239.6 million (24.4% margin, 3.4% beat)
- Revenue guidance $1.01 billion at the midpoint for Q4 2026, below analysts’ consensus estimates of $1.05 billion
- Operating margin 16.7%, up from 9.7% in the same quarter last year
- Sales volumes rose 6.6% year on year
- Market capitalization $10.79 billion
TEMPE, Ariz.--(BUSINESS WIRE)--Align Technology, Inc. (Nasdaq: ALGN), a medical device company that designs, manufactures and sells the Invisalign® System of clear aligners, iTero™ intraoral scanners and exocad™ CAD/CAM software for digital orthodontics and restorative dentistry, today reported financial results for the third quarter ("Q3'26").
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. Align Technology’s revenue grew at a tepid 2.1% annualized rate over the last five years, falling short of our standards.
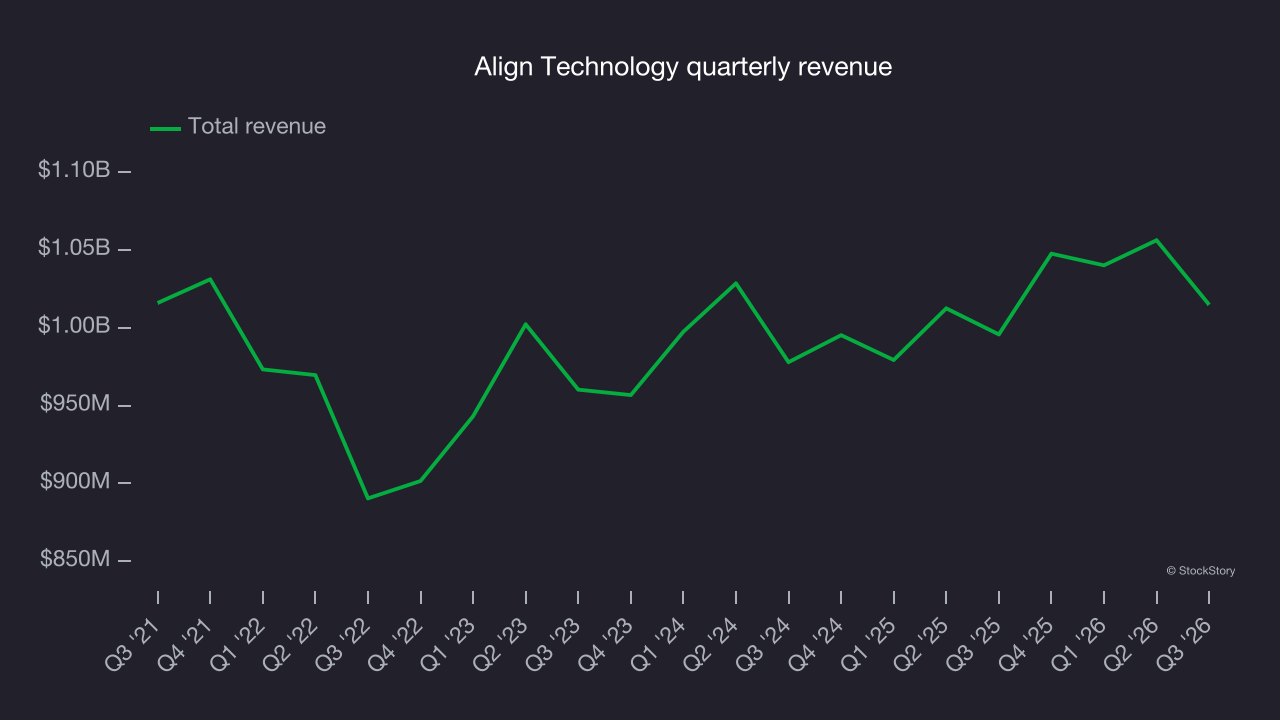
Long-term growth matters most, but within healthcare, a half-decade historical view may miss recent innovations or disruptive industry trends. Align Technology’s annualized revenue growth of 2.5% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 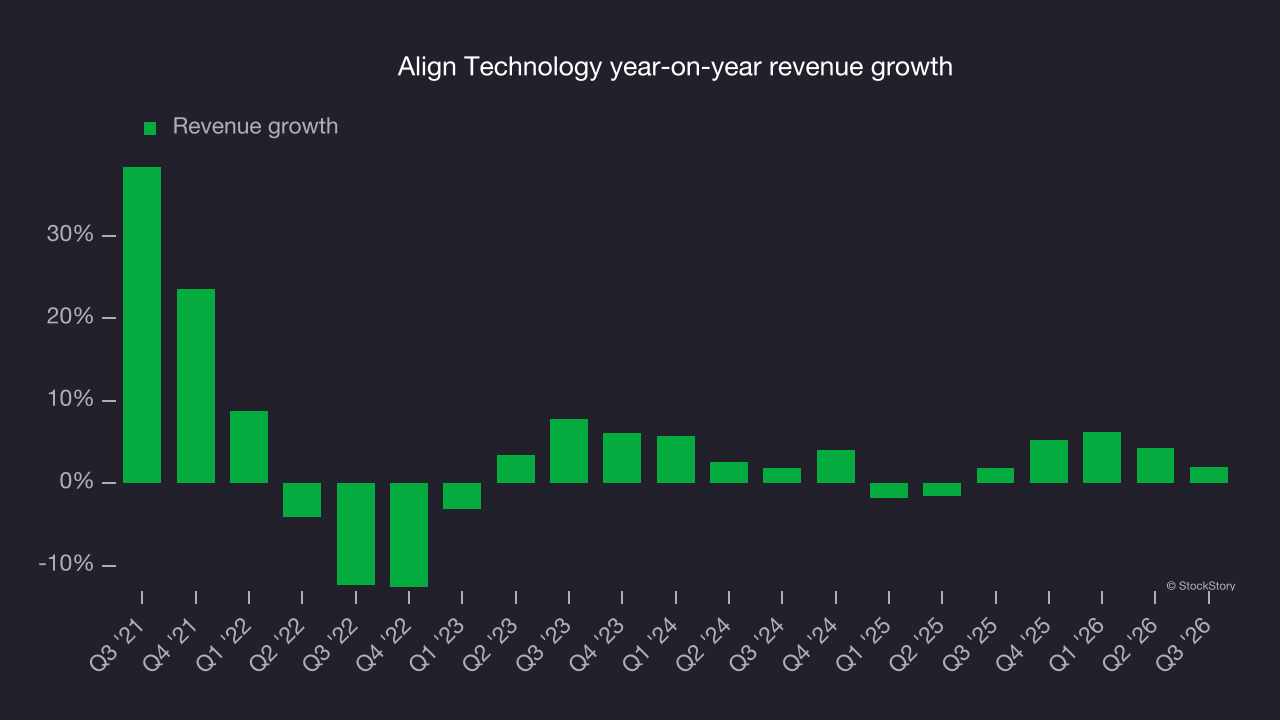
This quarter, Align Technology reported modest year-on-year revenue growth of 1.9% but beat Wall Street’s consensus estimates by 1.1%. Management is guiding for a 3.6% year-on-year decline in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 1.8% over the next 12 months, according to S&P, similar to its two-year rate. This projection is underwhelming and implies its newer products and services will not accelerate its top-line performance yet.
Adjusted operating margin
Align Technology’s adjusted operating margin has risen over the last 12 months and averaged 22.2% over the last five years. Its profitability was also strong for a healthcare business, showing it’s a well-run company with an efficient cost structure.
Looking at the trend in its profitability, Align Technology’s adjusted operating margin of 23.7% for the trailing 12 months may be around the same as five years ago, but it has increased by 1.7 percentage points over the last two years.
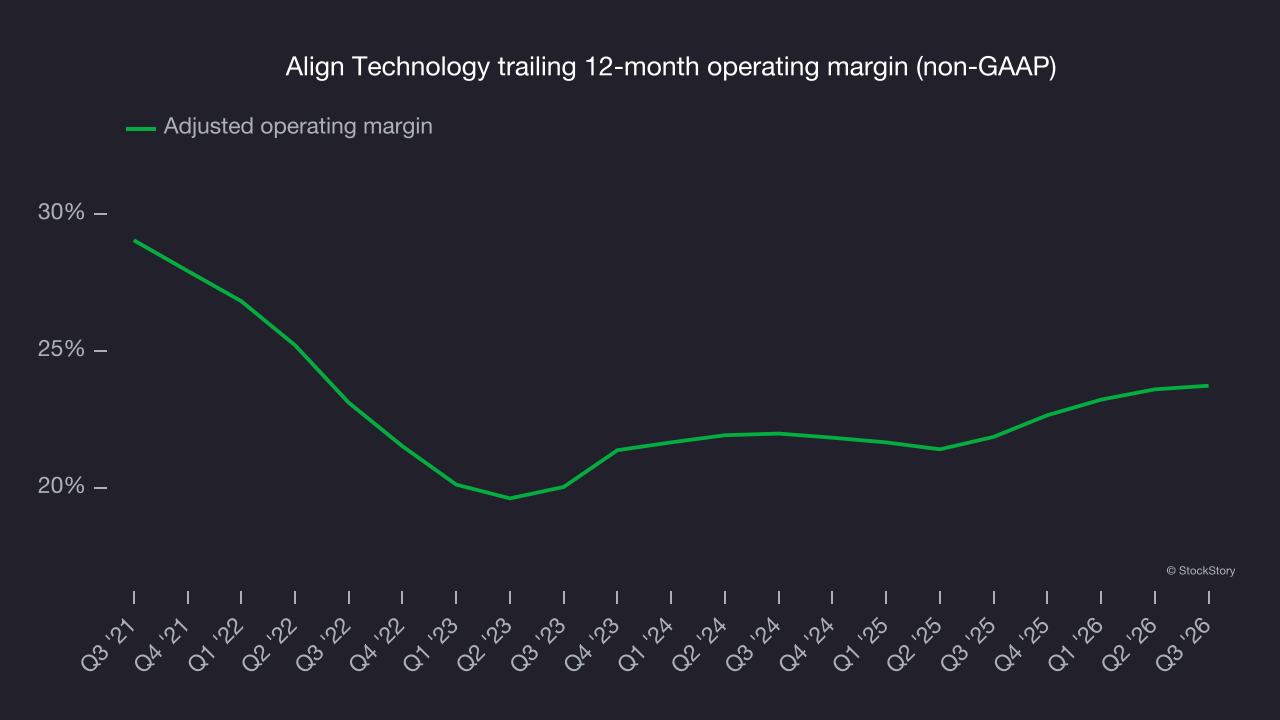
In Q3, Align Technology generated an adjusted operating margin of 24.4%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Long-term changes in earnings per share (EPS) matter for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Align Technology’s flat EPS over the last five years was below its 2.1% annualized revenue growth. However, its adjusted operating margin didn’t change during this time, indicating that non-fundamental factors such as interest and taxes affected its ultimate earnings.
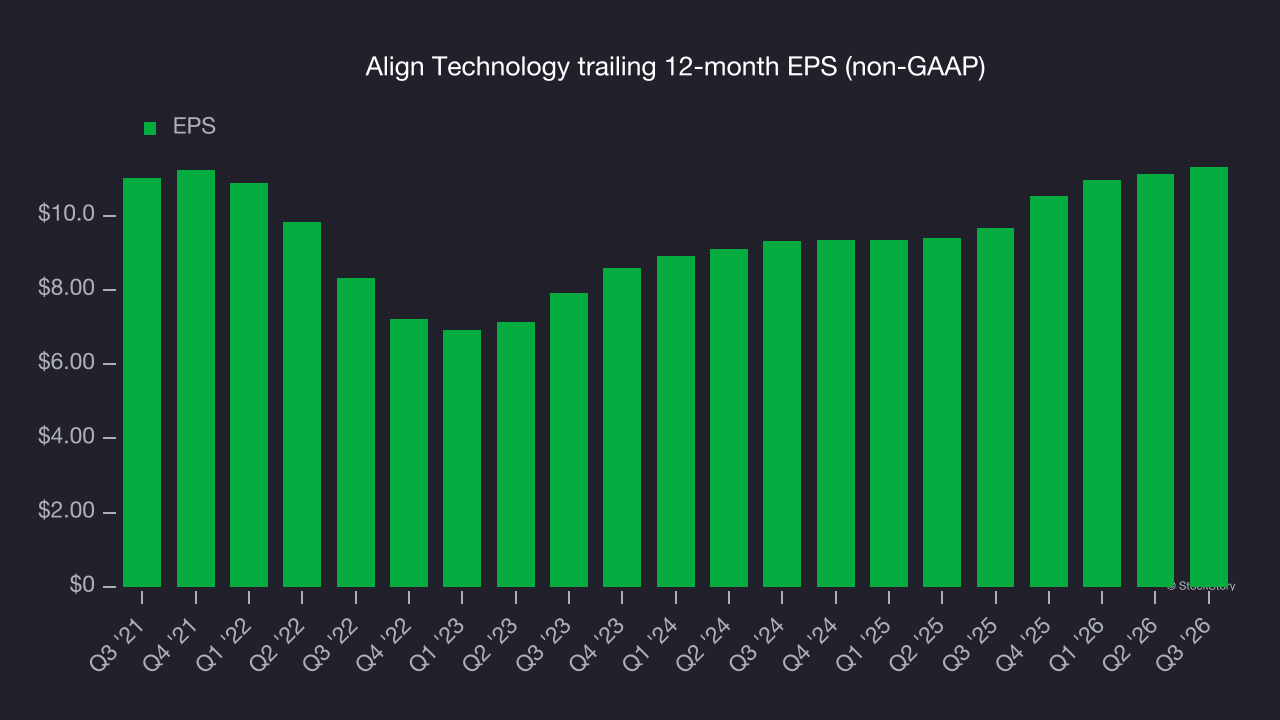
In Q3, Align Technology reported adjusted EPS of $2.80, up from $2.61 in the same quarter last year. This result beat analysts’ consensus estimates by 1.3%. Over the next 12 months, Wall Street expects Align Technology’s full-year EPS to grow 5.8% from $11.31 to $11.97, according to S&P.
Key takeaways from Align Technology’s Q3 results
Align Technology’s narrow revenue beat was offset by next-quarter revenue guidance that missed expectations, leaving room for a better quarter overall. Shares remained flat at $154.00 immediately after the report.
When assessing Align Technology at its current price, the latest quarter is only one part of the longer-term business quality picture. Quality, when combined with valuation, can help determine if the stock is a buy. Read the full research report here (it’s free).