
Online used car dealer Carvana (NYSE: CVNA) announced better-than-expected revenue in Q3 2026, with revenue up 42.4% year on year to $8.04 billion.
For more on Carvana, read our full research report for free.
Carvana (CVNA) Q3 2026 highlights:
- Revenue $8.04 billion vs S&P analysts’ consensus estimates of $7.67 billion (42.4% year-on-year growth, 4.9% beat)
- Adjusted EBITDA $800 million vs analysts’ consensus estimates of $791.3 million (10% margin, 1.1% beat)
- EBITDA guidance $2.85 billion at the midpoint for the full year, below analysts’ consensus estimates of $2.93 billion
- Operating margin 8.9%, in line with the same quarter last year
- Retail units sold 217,385
- Market capitalization $42.64 billion
“In the last two years, we have doubled the number of customers we serve while continuing to lead the industry in unit economics and giving value back to our customers by offering twice the selection, faster deliveries, and lower interest rates on their loans,” said Ernie Garcia, Carvana founder and CEO. “We are just beginning to realize the potential of the machine we are building.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years. Over the last three years, Carvana grew its revenue at a strong 34.9% compounded annual growth rate. Its growth surpassed the average consumer internet company and shows its offerings resonate with customers.
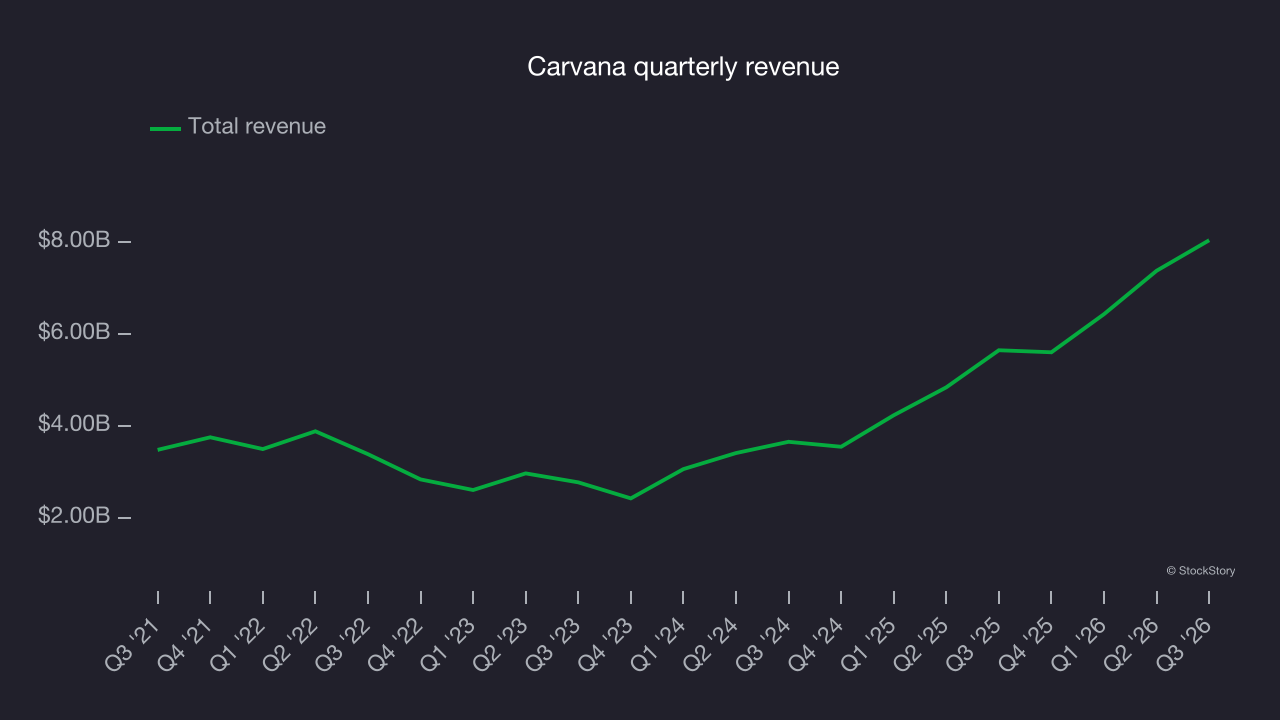
This quarter, Carvana reported year-on-year revenue growth of 42.4%, and its $8.04 billion of revenue beat Wall Street’s consensus estimates by 4.9%.
Looking ahead, sell-side analysts expect revenue to grow 26.1% over the next 12 months, according to S&P, a deceleration versus the last three years. Still, this projection is impressive given its scale and suggests the market is forecasting success for its products and services.
Revenue per unit
Average revenue per unit (ARPU) is a critical metric to track because it measures how much customers spend per order.
Carvana’s ARPU growth has been strong over the last two years, averaging 10.7%. Its ability to increase monetization demonstrates its platform’s value for existing units. 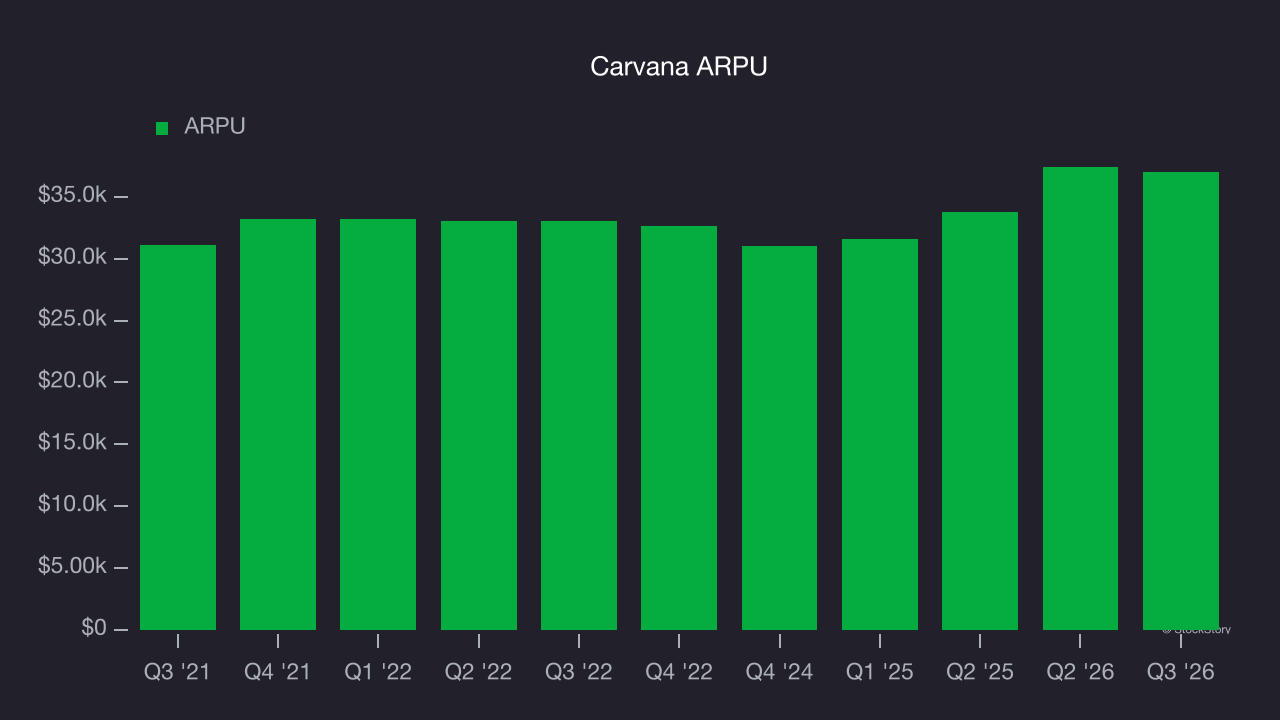
Key takeaways from Carvana’s Q3 results
Carvana’s Q3 results were mixed, with revenue beating analysts’ consensus estimates and EBITDA narrowly topping Wall Street’s consensus. Full-year EBITDA guidance, however, fell short of expectations. Shares surged 8.4% to $63.99 immediately after the release.
Is Carvana a buy at its current price? The latest quarter is only one part of assessing long-term business quality. Quality, combined with valuation, can help determine whether the stock is a buy. For more on Carvana, read our full research report here (it’s free).