Latin American e-commerce and fintech company MercadoLibre (NASDAQ: MELI) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 45.1% year on year to $10.75 billion. Its GAAP profit of $8.83 per share was 4.7% below analysts’ consensus estimates.
For more on MercadoLibre, read our free full research report.
MercadoLibre (MELI) Q3 2026 highlights:
- Revenue $10.75 billion vs S&P analysts’ consensus estimates of $10.64 billion (45.1% year-on-year growth, 1% beat)
- EPS (GAAP) $8.83 vs analysts’ consensus estimates of $9.27 (4.7% miss)
- Adjusted EBITDA $982 million vs analysts’ consensus estimates of $984.7 million (9.1% margin, in line)
- Operating margin 6.3%, down from 9.8% in the same quarter last year
- Free cash flow margin 22.8%, down from 31.7% in the previous quarter
- Unique active buyers 108.8 million, up 31.8 million year on year
- Market capitalization $84.27 billion
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Even a bad business can perform well for one or two quarters, but a high-quality one grows for years. MercadoLibre’s revenue grew at a strong 41.1% compounded annual growth rate over the last three years. Its growth surpassed the average consumer internet company and shows its offerings resonate with customers.
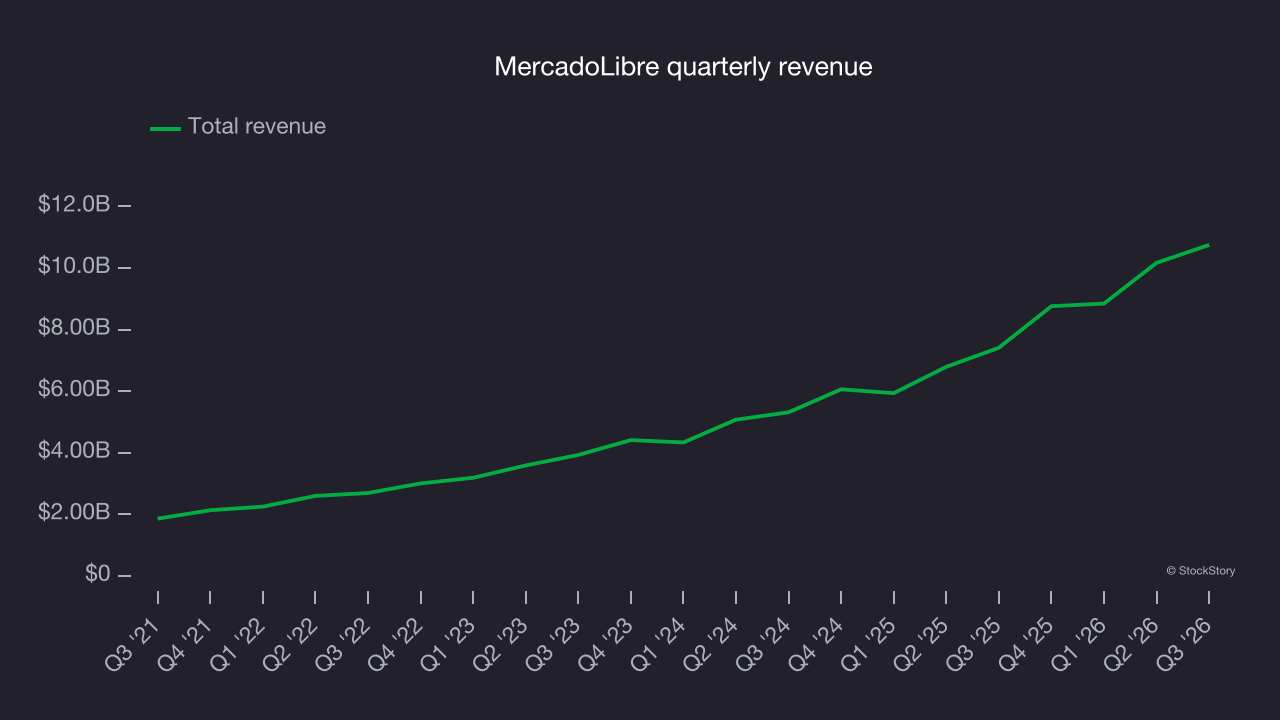
This quarter, MercadoLibre reported year-on-year revenue growth of 45.1%, and its $10.75 billion of revenue beat Wall Street’s consensus estimates by 1%.
Looking ahead, sell-side analysts expect revenue to grow 31.1% over the next 12 months, according to S&P, a deceleration versus the last three years. Still, this projection is strong given its scale and indicates the market expects continued success for its products and services.
Unique active buyers
User growth
As an online marketplace, MercadoLibre generates revenue growth by increasing both the number of users on its platform and the average order size in dollars.
Over the last two years, MercadoLibre’s unique active buyers, a key performance metric for the company, increased by 12.4% annually to 108.8 million in the latest quarter. This growth rate is strong for a consumer internet business and indicates users value its offerings. 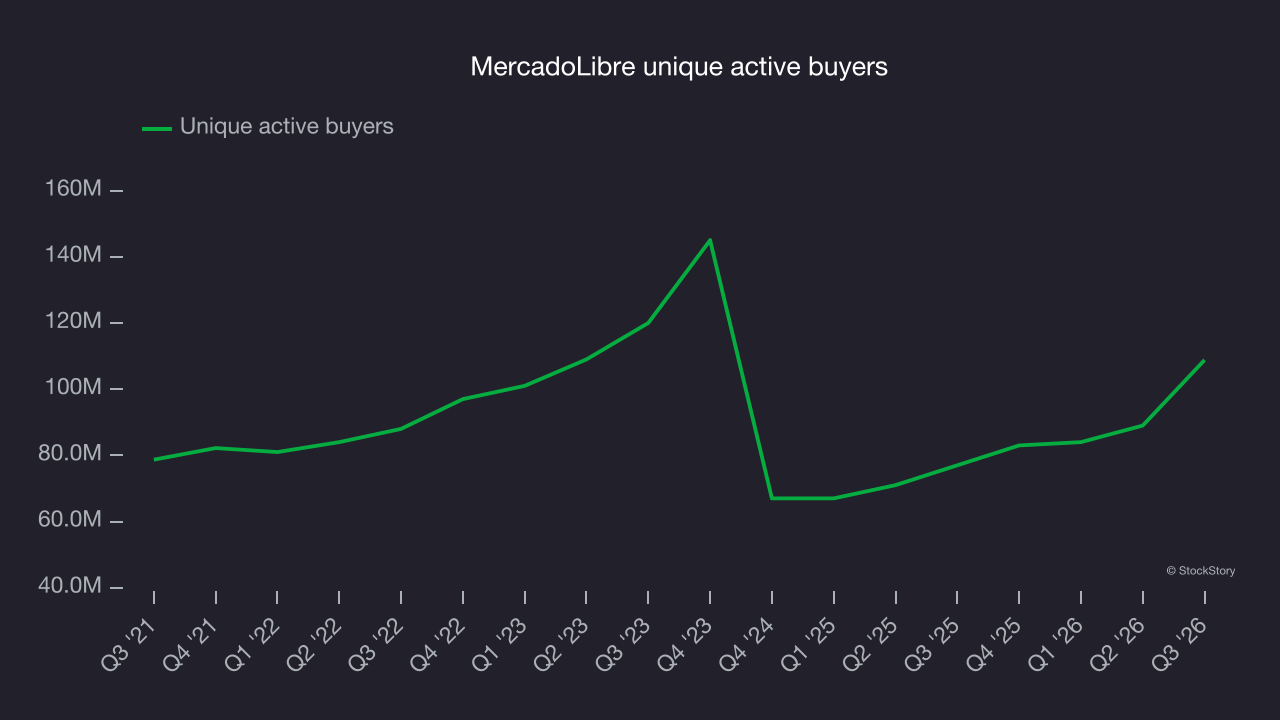
In Q3, MercadoLibre added 31.8 million unique active buyers, leading to 41.3% year-on-year growth. The quarterly print was higher than its two-year result, suggesting its new initiatives are accelerating user growth.
Revenue per user
Average revenue per user, or ARPU, is a critical metric to track because it measures how much the company earns in transaction fees from each user. ARPU also provides insight into a user’s average order size and MercadoLibre’s take rate, or “cut”, on each order.
MercadoLibre’s ARPU growth has been substantial over the last two years, averaging 51%. Its ability to increase monetization while growing its unique active buyers rapidly reflects the strength of its platform, as its users are spending significantly more than last year. 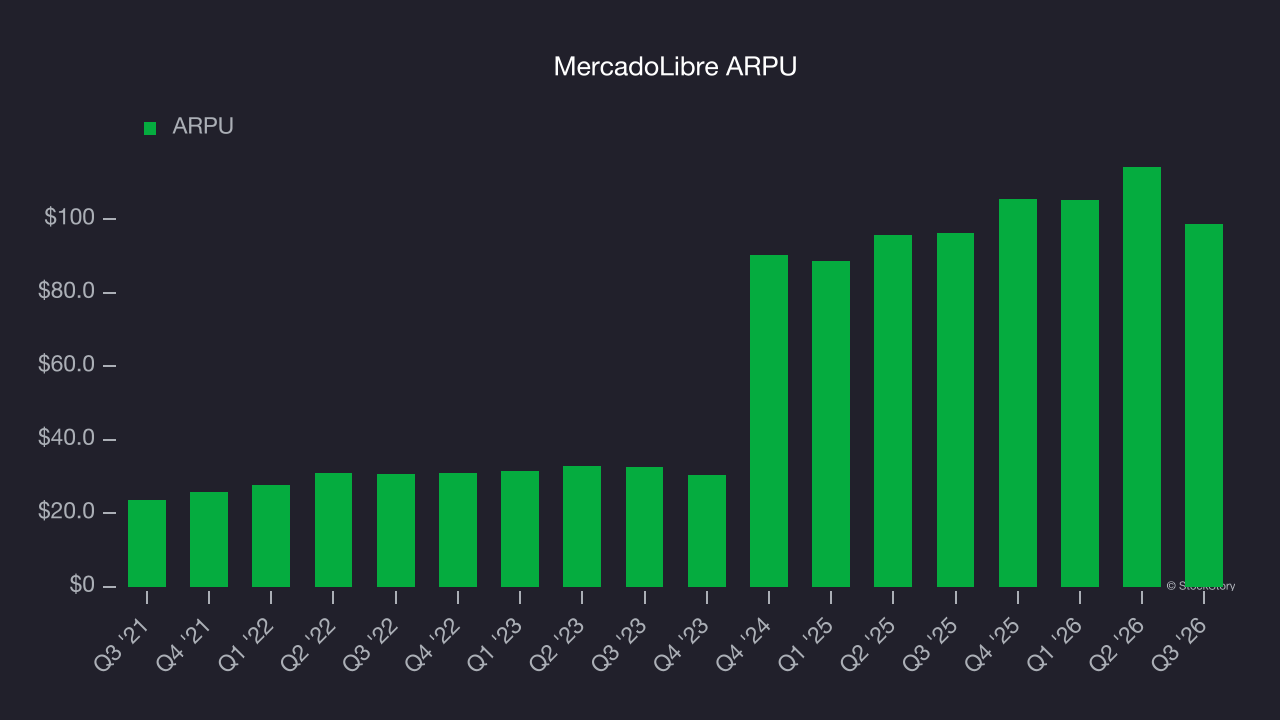
This quarter, MercadoLibre’s ARPU came in at $98.80. It grew by 2.7% year on year, slower than its user growth.
Key takeaways from MercadoLibre’s Q3 results
MercadoLibre’s user count stood out in Q3, and revenue narrowly topped Wall Street’s consensus estimates, giving the quarter some key positives. Investors were likely hoping for more: Shares tumbled 7% to $1,613 immediately after the results.
For MercadoLibre, the latest quarter matters, but not nearly as much as longer-term fundamentals and valuation when deciding if the stock is a buy. Read more in the full research report here (it’s free).