What a fantastic six months it’s been for Dell. Shares of the company have skyrocketed 69.1%, hitting $365.87. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now still a good time to buy DELL? Or are investors being too optimistic? Find out in our full research report, it’s free.
Why are we positive on DELL?
Founded by Michael Dell in his University of Texas dorm room in 1984 with just $1,000, Dell Technologies (NYSE: DELL) provides hardware, software, and services that help organizations build their IT infrastructure, manage cloud environments, and enable digital transformation.
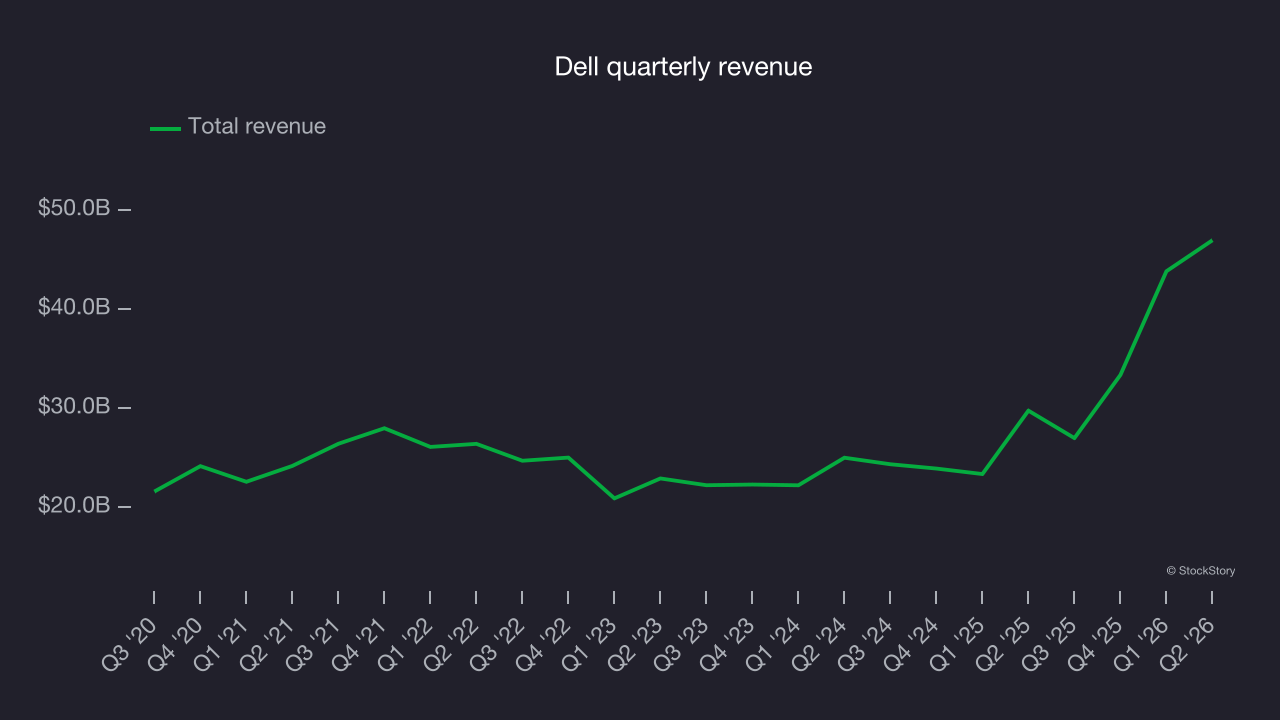
1. Skyrocketing revenue shows strong momentum
A company’s long-term performance is an indicator of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Luckily, Dell’s sales grew at an impressive 10.3% compounded annual growth rate over the last five years. Its growth beat the average business services company and shows its offerings resonate with customers.
2. Outstanding long-term EPS growth
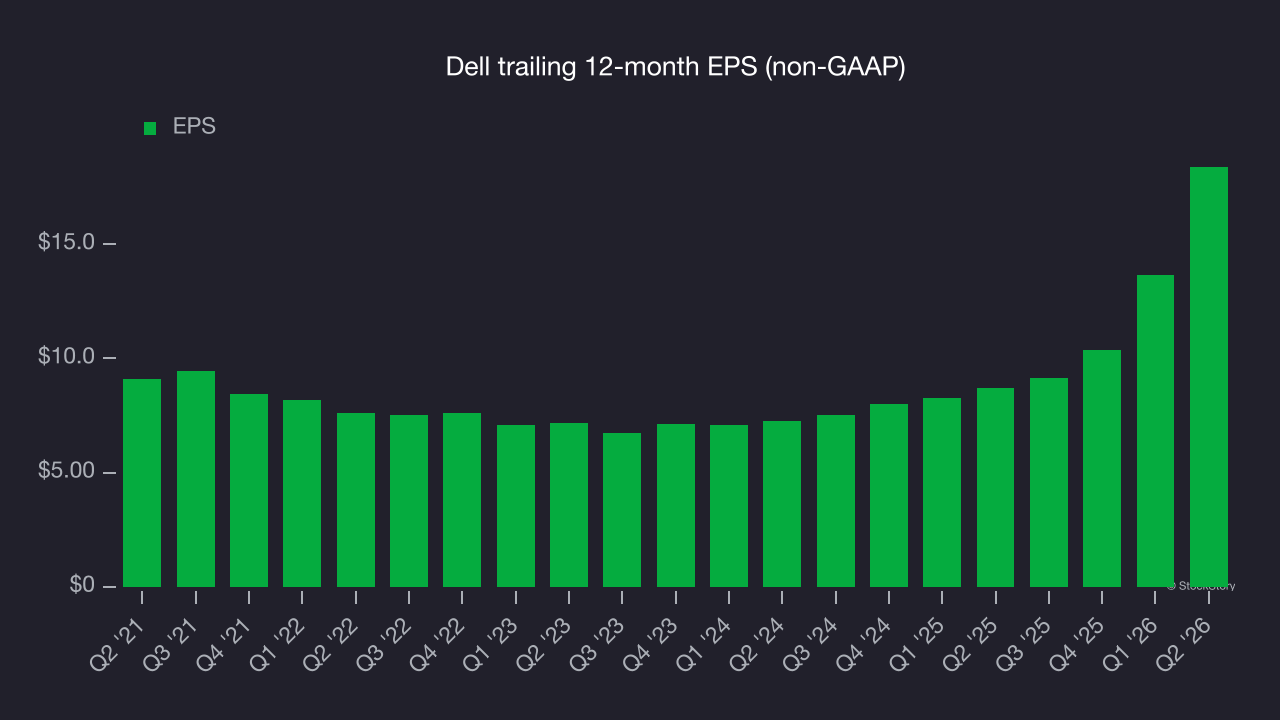
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Dell’s EPS grew at 15.1% compounded annual growth rate over the last five years, higher than its 10.3% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
3. New investments bear fruit as ROIC jumps
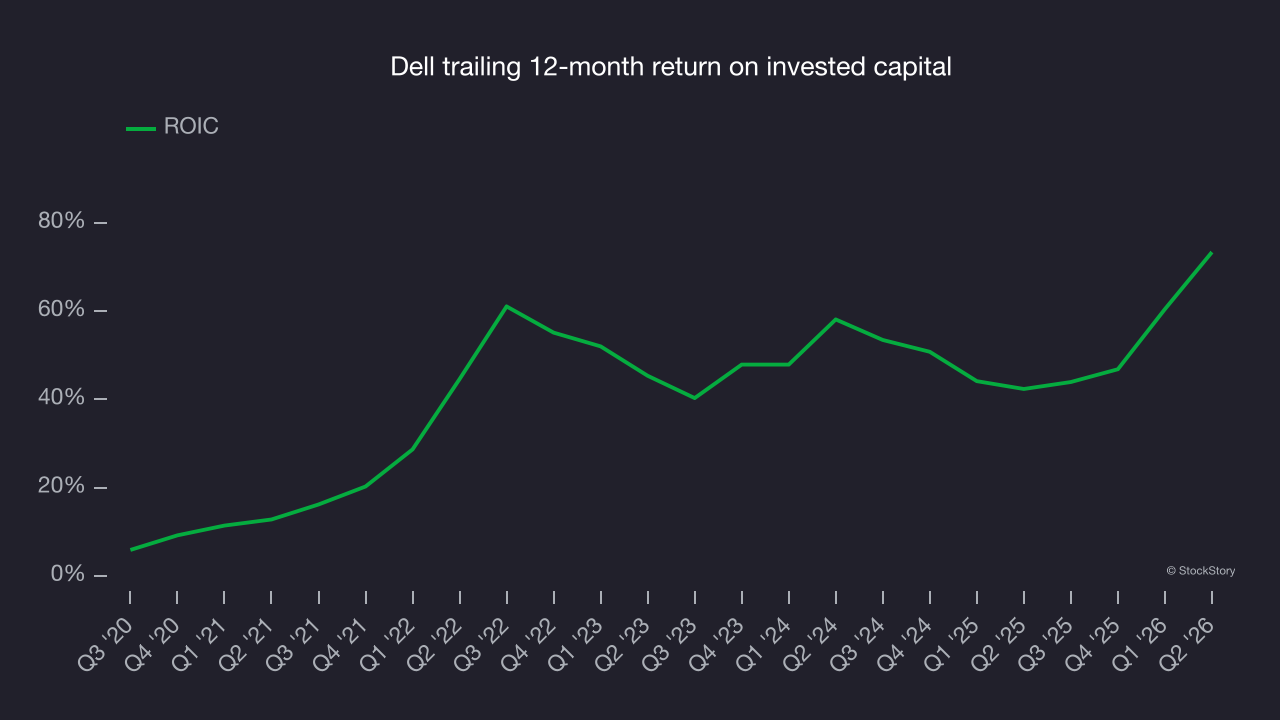
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Fortunately, Dell’s ROIC has increased significantly over the last few years. This is a great sign when paired with its already strong returns. It could suggest its competitive advantage or profitable growth opportunities are expanding.
Final judgment
These are just a few reasons why Dell ranks near the top of our list, and with the recent surge, the stock trades at 14.5× forward P/E (or $365.87 per share). Is now the right time to buy? See for yourself in our in-depth research report, it’s free.
High-quality stocks for all market conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.