Real estate technology company The Real Brokerage (NASDAQ: REAX) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 28% year on year to $727.9 million. Revenue guidance for the full year exceeded analysts’ consensus estimates, but next quarter’s guidance of $600 million was less impressive, coming in 3.3% below expectations. Its GAAP loss of $2.25 per share was significantly below analysts’ consensus estimates.
For more on The Real Brokerage, read our full research report for free.
The Real Brokerage (REAX) Q3 2026 highlights:
- Revenue $727.9 million vs S&P analysts’ consensus estimates of $684.1 million (28% year-on-year growth, 6.4% beat)
- EPS (GAAP) -$2.25 vs analysts’ consensus estimates of $0.30 (significant miss)
- Adjusted EBITDA $33.75 million vs analysts’ consensus estimates of $35.1 million (4.6% margin, 3.8% miss)
- Revenue guidance $600 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $620.7 million
- EBITDA guidance $182.5 million at the midpoint for the full year, above analysts’ consensus estimates of $114.2 million
- Operating margin -9.9%, down from -0.1% in the same quarter last year
- Market capitalization $621.2 million
“The first two months since bringing together Real and REMAX have reinforced our belief in the tremendous opportunity ahead,” said Tamir Poleg, Chairman and Chief Executive Officer. “We've moved quickly to simplify the organization, improve operating efficiency and lay the foundation for a stronger, more competitive platform. While the housing market remains challenging, we are focused on what we can control: providing an unmatched value proposition, executing our integration, and delivering sustainable market share growth and margin expansion. We believe the combination of Real's technology, collaborative culture and flexible brokerage model with REMAX's global brand and strong franchise network positions us to create significant long-term value for our agents, franchisees and shareholders.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years. The Real Brokerage’s 98.3% annualized revenue growth over the last five years was strong. Its growth beat the average consumer discretionary company and shows its offerings resonate with customers.
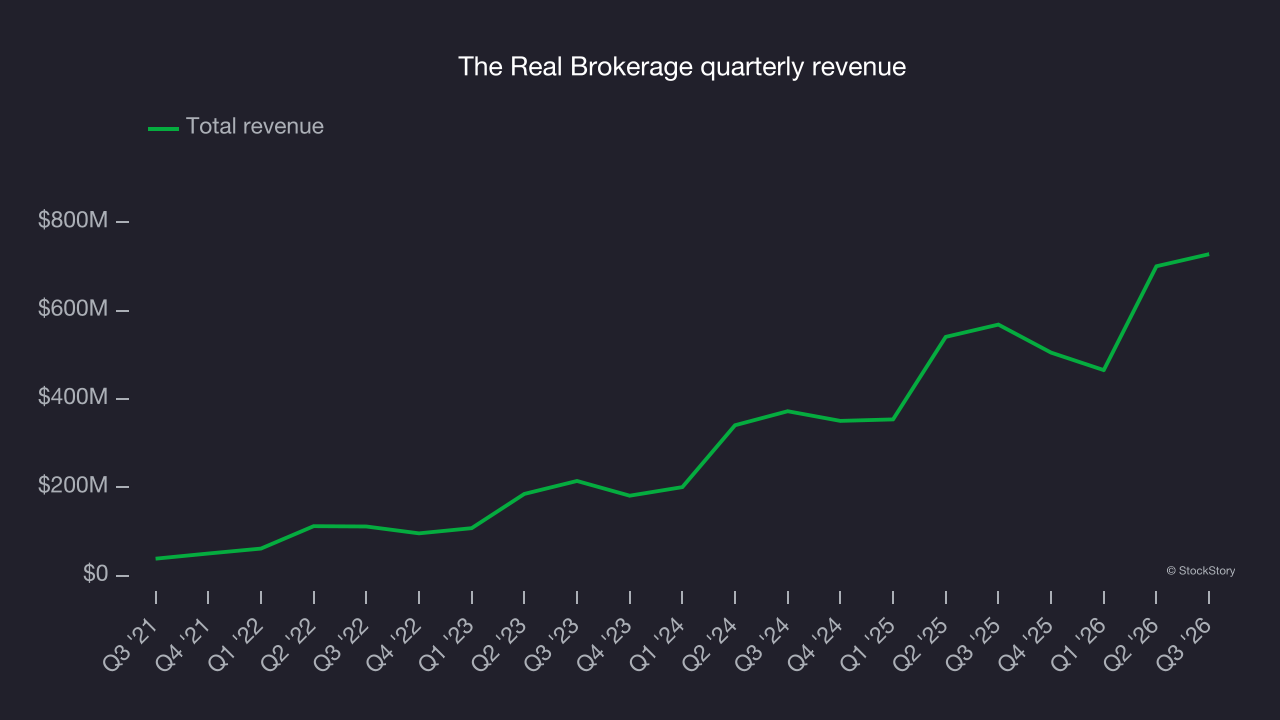
Long-term growth matters most, but within consumer discretionary, a stretched historical view may miss a company riding a successful new product or trend. The Real Brokerage’s annualized revenue growth of 48% over the last two years is below its five-year trend, but the results still suggest healthy demand. 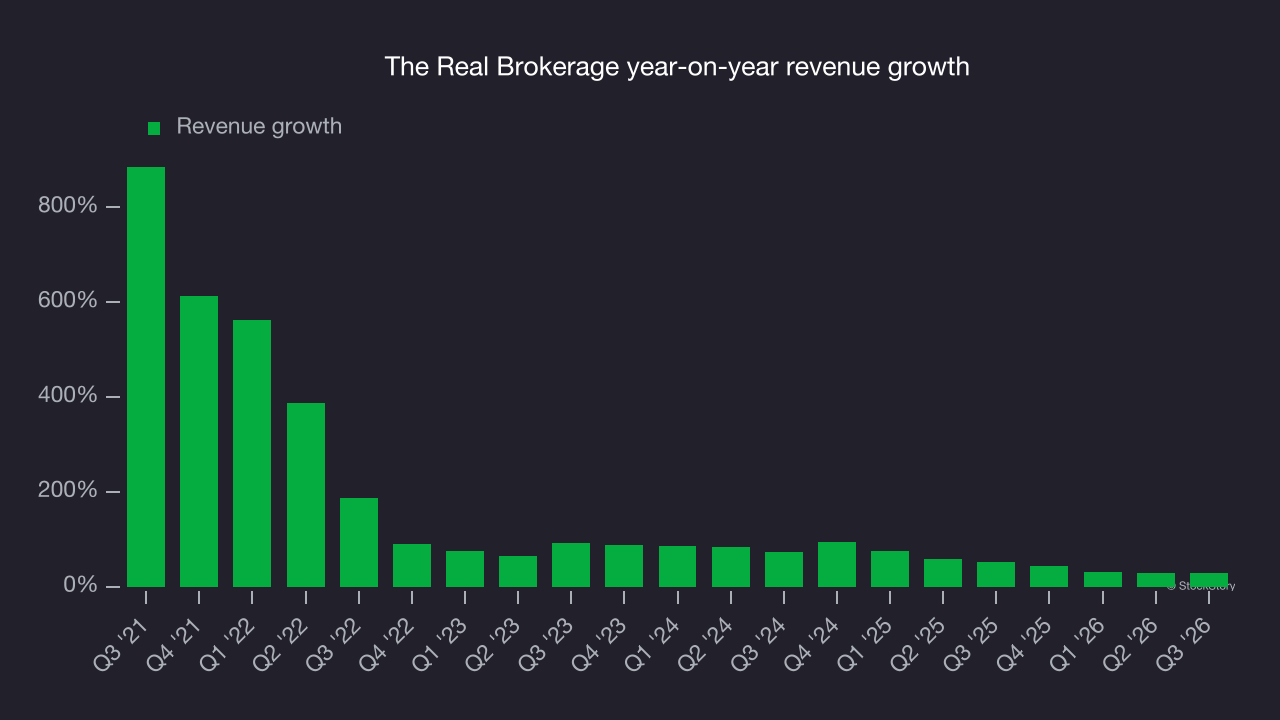
This quarter, The Real Brokerage reported strong year-on-year revenue growth of 28%, and its $727.9 million of revenue topped Wall Street’s consensus estimates by 6.4%. Company management is currently guiding for an 18.8% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 15.9% over the next 12 months, according to S&P, a deceleration versus the last two years. Despite the slowdown, this projection is healthy and suggests the market sees success for its products and services.
Operating margin
The Real Brokerage’s operating margin has been trending down over the last 12 months and averaged negative 2% over the last two years. Unprofitable, high-growth companies warrant extra scrutiny, especially if their margins fall because they’re spending heavily to stay relevant, an unsustainable practice.
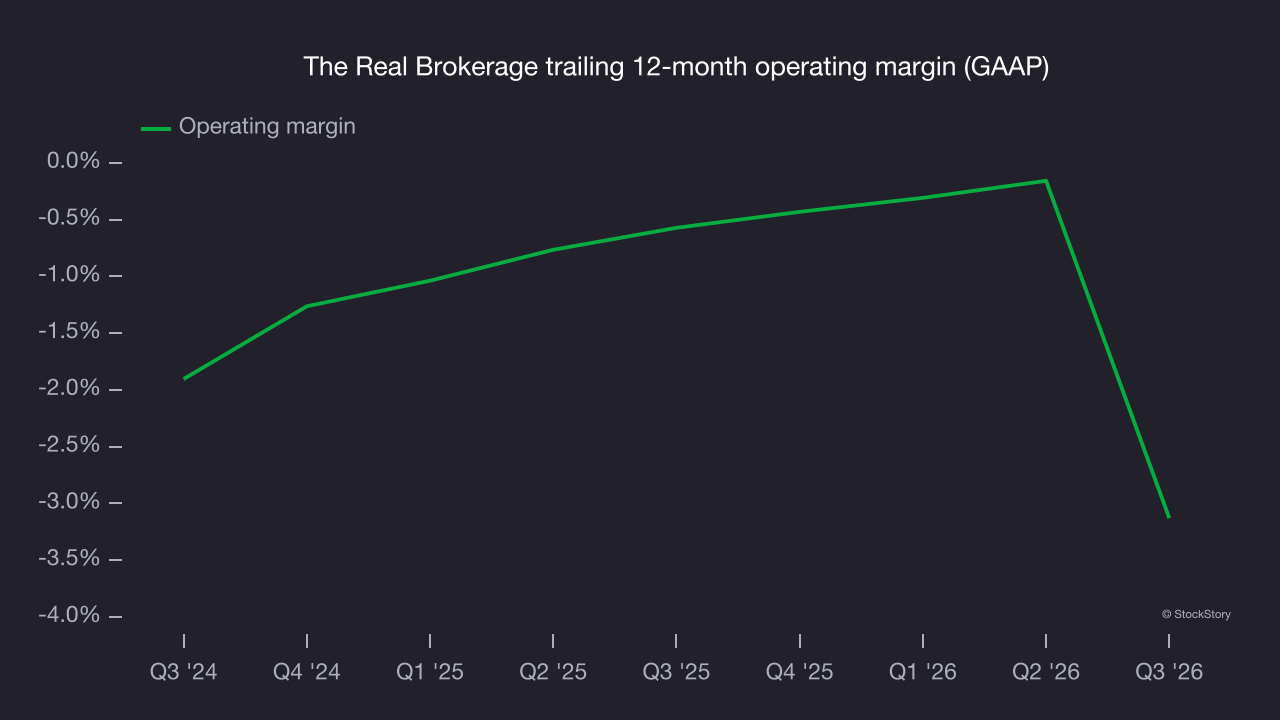
This quarter, The Real Brokerage generated a negative 9.9% operating margin.
Cash flow
Earnings are valuable for assessing company performance, but cash matters because accounting profits alone can’t pay the bills.
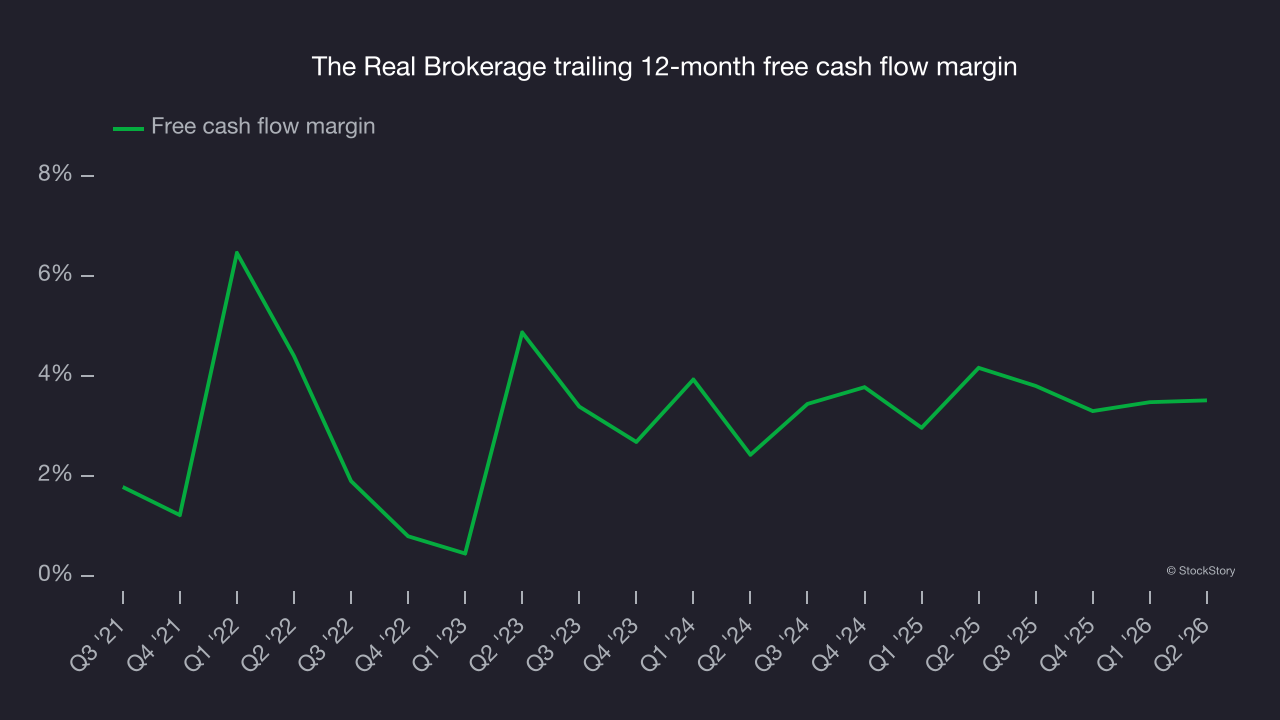
The Real Brokerage has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 4%, below expectations for a consumer discretionary business.
Key takeaways from The Real Brokerage’s Q3 results
Full-year guidance was a key positive in The Real Brokerage’s mixed Q3 update, with EBITDA guidance well above analysts’ consensus estimates and revenue guidance also topping Wall Street’s consensus. But the quarterly results and near-term outlook had shortfalls: EPS missed estimates, and next-quarter revenue guidance fell short of Wall Street’s consensus. The market seemed to be hoping for more, and shares fell 4.1% to $16.29 immediately after the results.
When deciding whether to buy the stock, the latest quarter matters, but not nearly as much as longer-term fundamentals and valuation. For more on these factors, read the full research report here (it’s free).