
Digital advertising technology company PubMatic (NASDAQ: PUBM) announced better-than-expected revenue in Q3 2026, with revenue up 17.1% year on year to $79.58 million. Guidance for next quarter’s revenue was better than expected at $92 million at the midpoint, 0.6% above analysts’ consensus estimates. Its non-GAAP profit of $0.25 per share was 78.6% above analysts’ consensus estimates.
For more on PubMatic, read our free full research report.
PubMatic (PUBM) Q3 2026 highlights:
- Revenue $79.58 million vs S&P consensus estimates of $76.11 million (17.1% year-on-year growth, 4.6% beat)
- Adjusted EPS $0.25 vs S&P consensus estimates of $0.14 (78.6% beat)
- Adjusted EBITDA $25.96 million vs analysts’ consensus estimates of $17.98 million (32.6% margin, 44.4% beat)
- Revenue guidance $92 million at the midpoint for Q4 2026, roughly in line with what analysts were expecting
- EBITDA guidance $80 million at the midpoint for the full year, above analysts’ consensus estimates of $71.56 million
- Operating margin 11%, up from -12.4% in the same quarter last year
- Free cash flow margin 22.1%, up from 17.4% in the previous quarter
- Market capitalization $811.5 million
"We delivered an outstanding third quarter, with revenue growth accelerating for the third consecutive quarter and adjusted EBITDA more than doubling year-over-year,” said Rajeev Goel, co-founder and CEO of PubMatic. “Our investments in advertiser performance are translating into faster, more profitable growth and a more diversified business. At the same time, AI is accelerating the shift from sell-side targeting to sell-side decisioning, enabling buyers to act on richer intelligence closer to the inventory and first party insights. Our proprietary platform intelligence, agentic leadership and AI-native infrastructure position us to lead this shift, deliver more value to buyers and publishers and expand our market opportunity."
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. PubMatic’s 7.7% annualized revenue growth over the last five years was sluggish, falling short of the software sector benchmark.
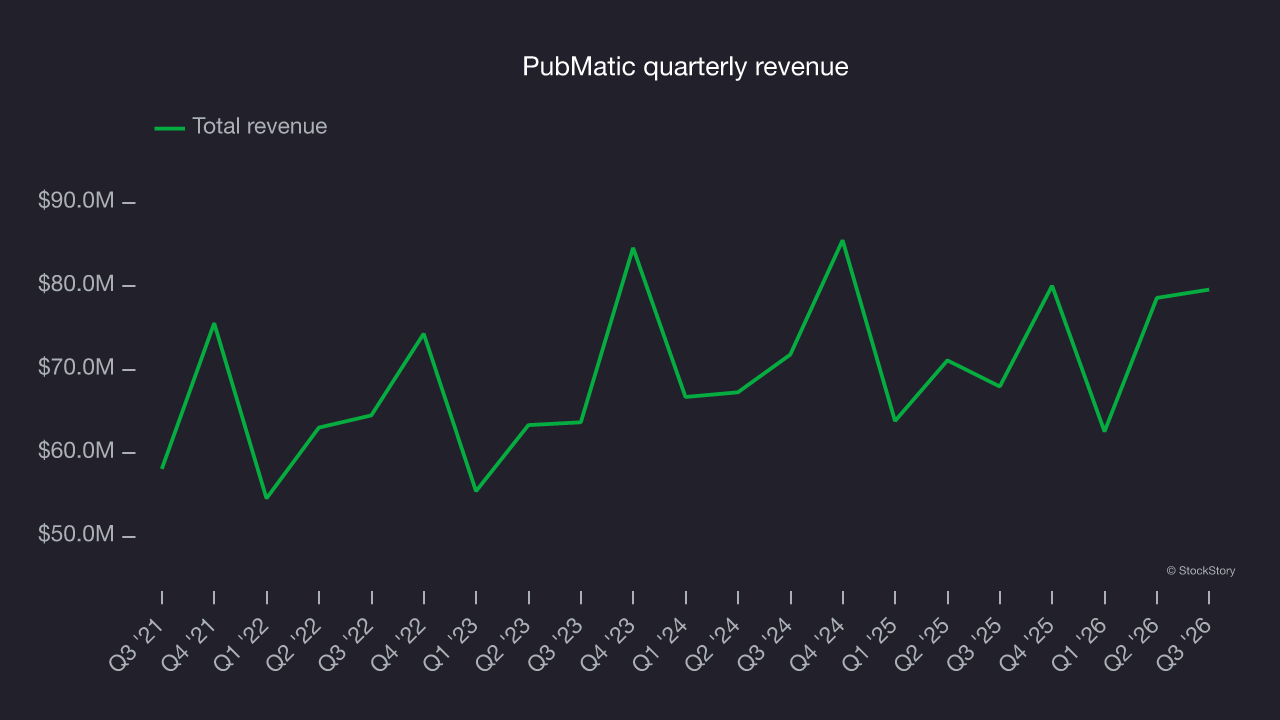
Long-term growth is the most important, but within software, a half-decade historical view may miss new innovations or demand cycles. PubMatic’s recent performance shows its demand has slowed as its annualized revenue growth of 1.8% over the last two years was below its five-year trend. Such decelerations in revenue growth warrant caution, as they could signal changing consumer tastes aided by low switching costs. 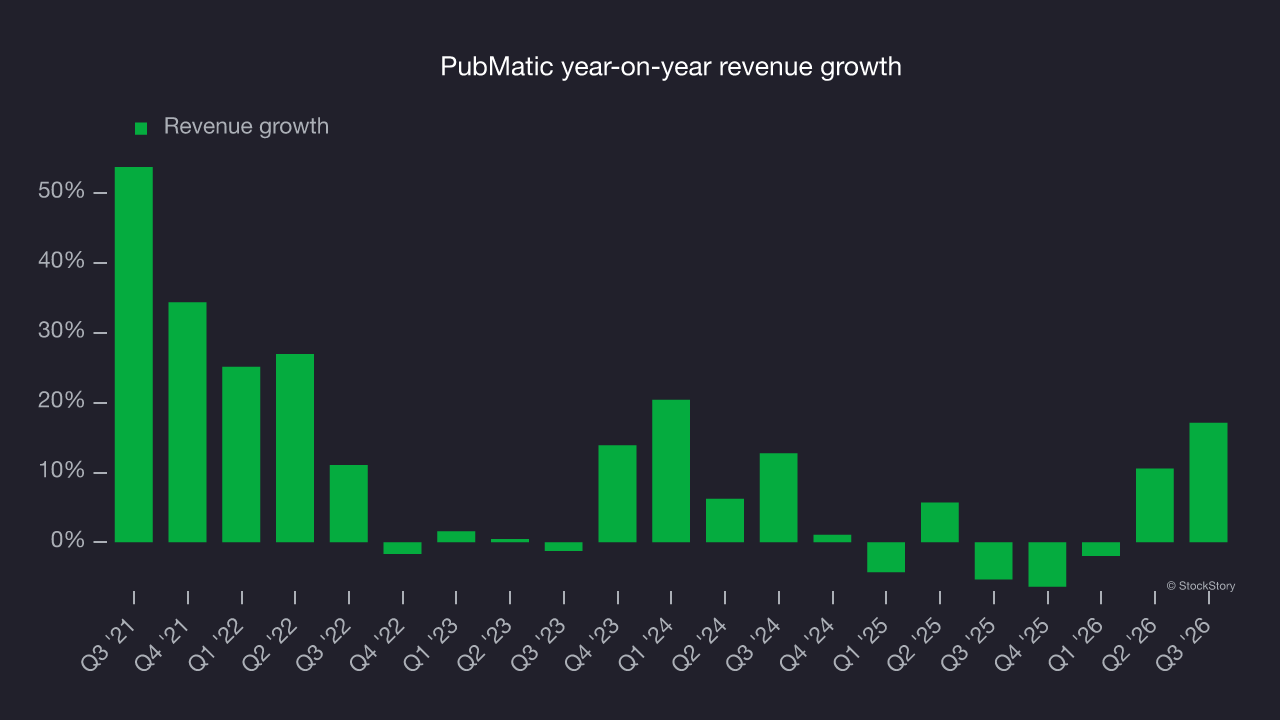
This quarter, PubMatic reported year-on-year revenue growth of 17.1%, and its $79.58 million of revenue exceeded Wall Street’s consensus estimates by 4.6%. Company management is currently guiding for a 14.9% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 8.5% over the next 12 months, according to S&P. While this projection suggests its newer products and services will spur better top-line performance, it is still below average for the sector.
Customer acquisition efficiency
The customer acquisition cost, or CAC, payback period measures the months a company needs to recoup the money spent on acquiring a new customer. This metric helps assess how quickly a business can break even on its sales and marketing investments.
PubMatic is efficient at acquiring new customers, and its CAC payback period was 31 months this quarter. The company’s relatively fast recovery of its customer acquisition costs means it can attempt to spur growth by increasing its sales and marketing investments.
Key takeaways from PubMatic’s Q3 results
PubMatic’s outlook was a highlight of a solid quarter: Full-year EBITDA guidance came in well ahead of analysts’ consensus estimates, and next-quarter EBITDA guidance also topped Wall Street’s consensus. Investors were likely hoping for more, however, as shares fell 2.3% to $18.58 immediately after the release.
To assess PubMatic at its current price, consider the bigger picture of valuation, business quality and the latest earnings. For more on PubMatic, read the full research report here (it’s free).