HCI Group’s 28.5% return over the past six months has outpaced the S&P 500 by 19.6%, and its stock price has climbed to $198.60 per share. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is it too late to buy HCI? Find out in our full research report, it’s free.
Why Are We Positive on HCI?
Starting as a Florida "take-out" insurer that assumed policies from the state-backed Citizens Property Insurance Corporation, HCI Group (NYSE: HCI) provides property and casualty insurance, primarily homeowners coverage, while leveraging proprietary technology to improve underwriting and claims processing.
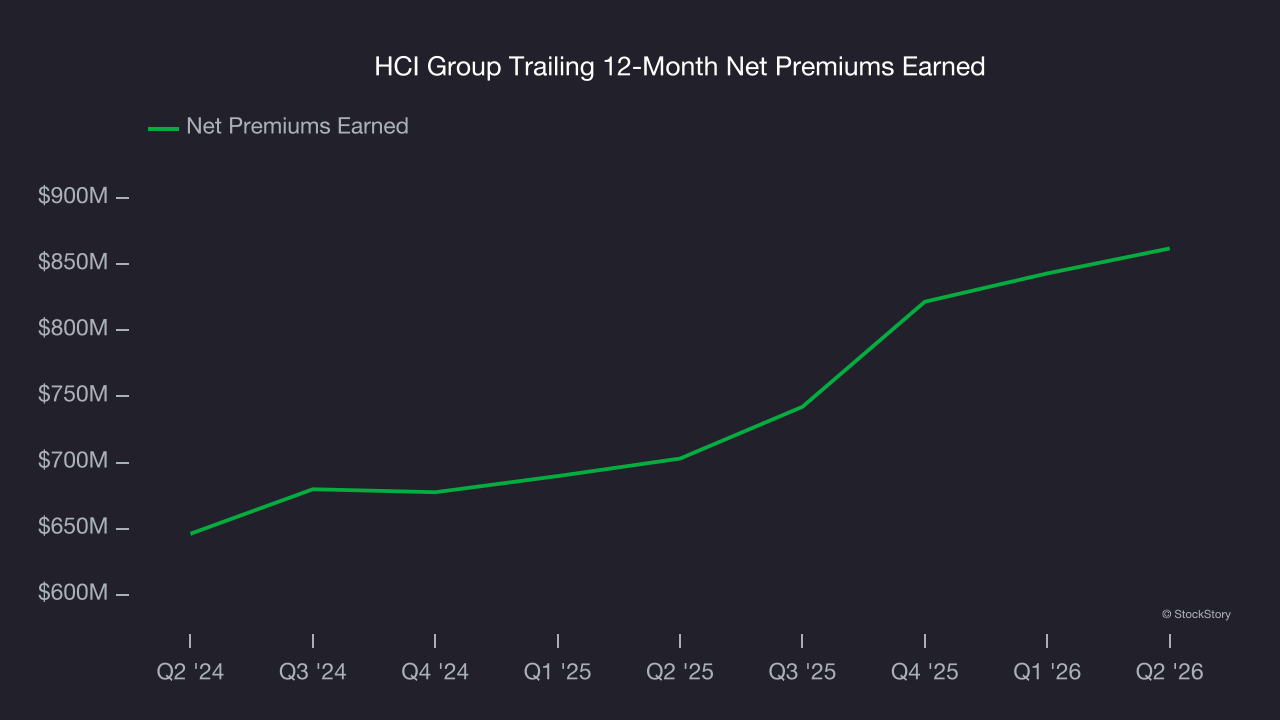
1. Net Premiums Earned Skyrocket, Fueling Growth Opportunities
When insurers sell policies, they protect themselves from extremely large losses or an outsized accumulation of losses with reinsurance (insurance for insurance companies). Net premiums earned are therefore net of what’s ceded to reinsurers as a risk mitigation and transfer strategy.
HCI Group’s net premiums earned has grown at a 15.5% annualized rate over the last two years, much better than the broader insurance industry and in line with its total revenue.
2. Outstanding Long-Term EPS Growth
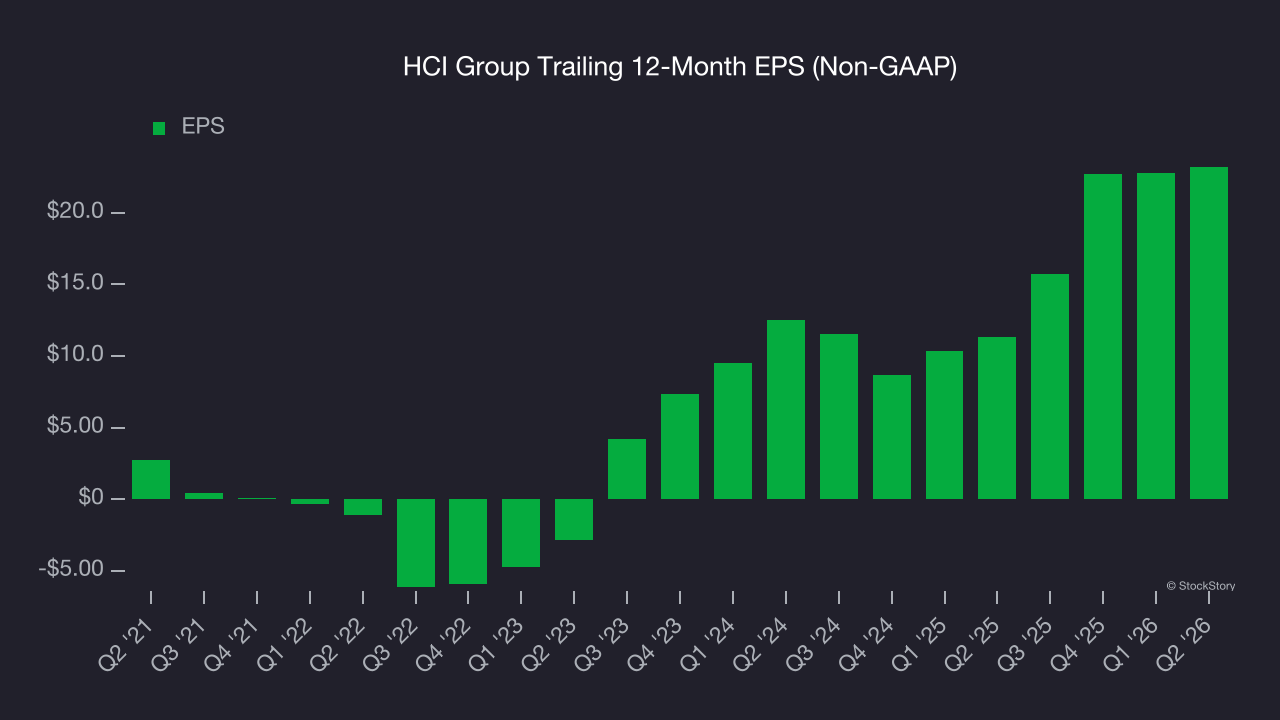
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
HCI Group’s EPS grew at 53.8% compounded annual growth rate over the last five years, higher than its 20.8% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
3. Growing BVPS Reflects Strong Asset Base
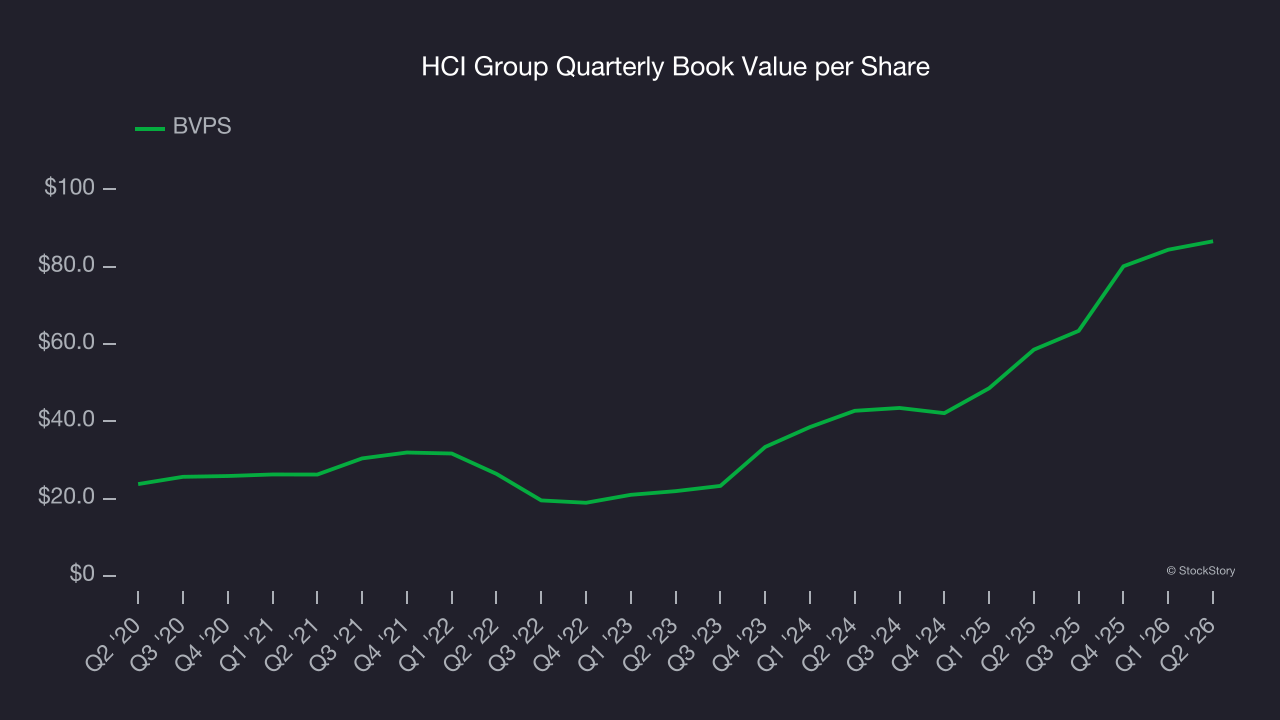
We consider book value per share (BVPS) a critical metric for insurance companies. BVPS represents the total net worth per share, providing insight into a company’s financial strength and ability to meet policyholder obligations.
HCI Group’s BVPS increased by 27% annually over the last five years, and growth has recently accelerated as BVPS grew at an incredible 42.4% annual clip over the past two years (from $42.72 to $86.60 per share).
Final Judgment
These are just a few reasons why we think HCI Group is one of the best insurance companies out there, and with its shares beating the market recently, the stock trades at 2× forward P/B (or $198.60 per share). Is now the time to initiate a position? See for yourself in our comprehensive research report, it’s free.
Stocks We Like Even More Than HCI Group
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.