
Over the past six months, Yum China’s stock price fell to $44.87. Shareholders have lost 7.9% of their capital, which is disappointing considering the S&P 500 has climbed by 7.7%. This might have investors contemplating their next move.
Is now the time to buy Yum China, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Yum China Not Exciting?
Even with the cheaper entry price, we’re sitting this one out for now. Here are three reasons why YUMC doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
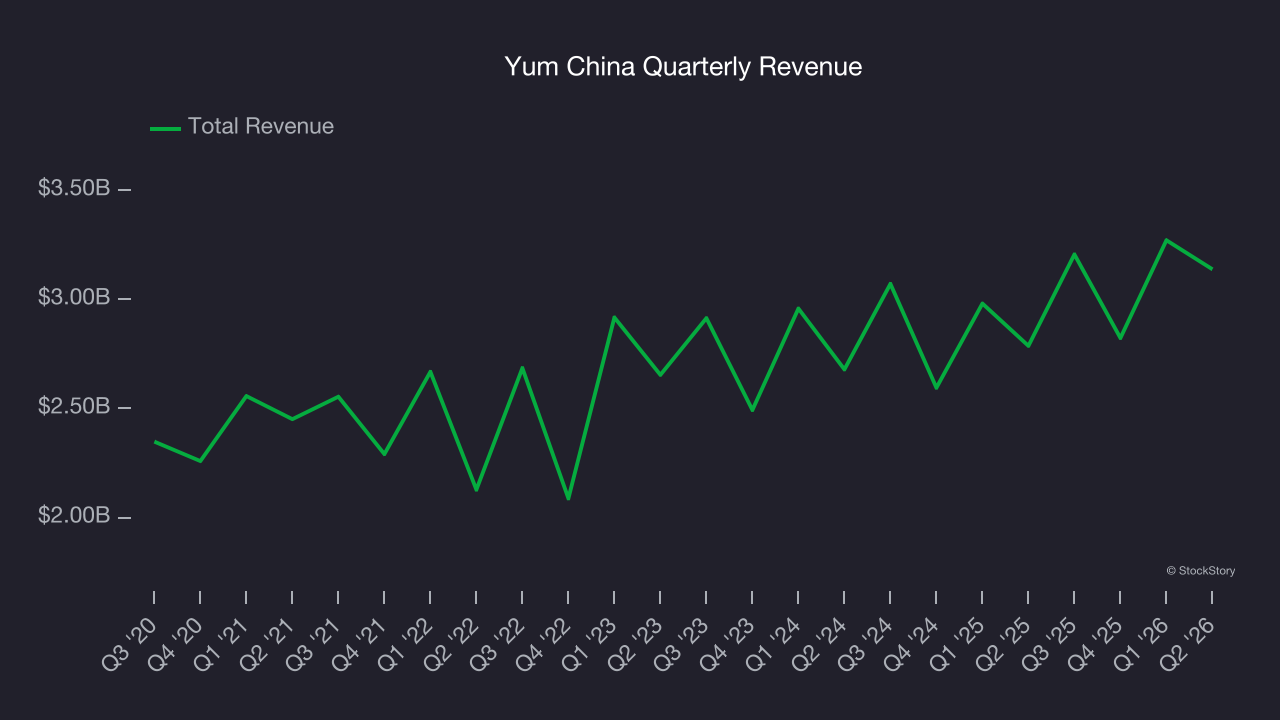
A company’s long-term sales performance is one signal of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Unfortunately, Yum China’s 5.5% annualized revenue growth over the last seven years was tepid. This was below our standard for the restaurant sector.
2. Flat Same-Store Sales Indicate Weak Demand
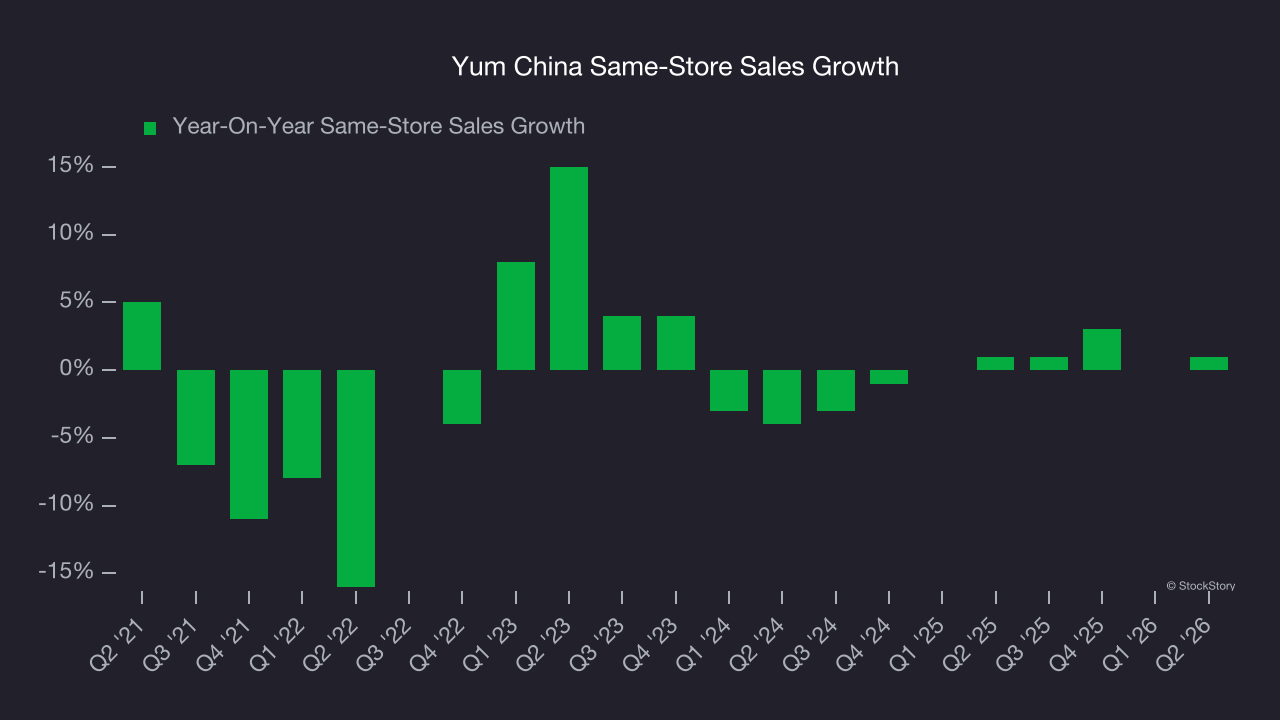
Same-store sales is an industry measure of whether revenue is growing at existing restaurants, and it is driven by customer visits (often called traffic) and the average spending per customer (ticket).
Yum China’s demand within its existing dining locations has barely increased over the last two years as its same-store sales were flat.
3. Low Gross Margin Reveals Weak Structural Profitability
Gross profit margins tell us how much money a restaurant gets to keep after paying for the direct costs of the meals it sells, like ingredients, and indicate its level of pricing power.
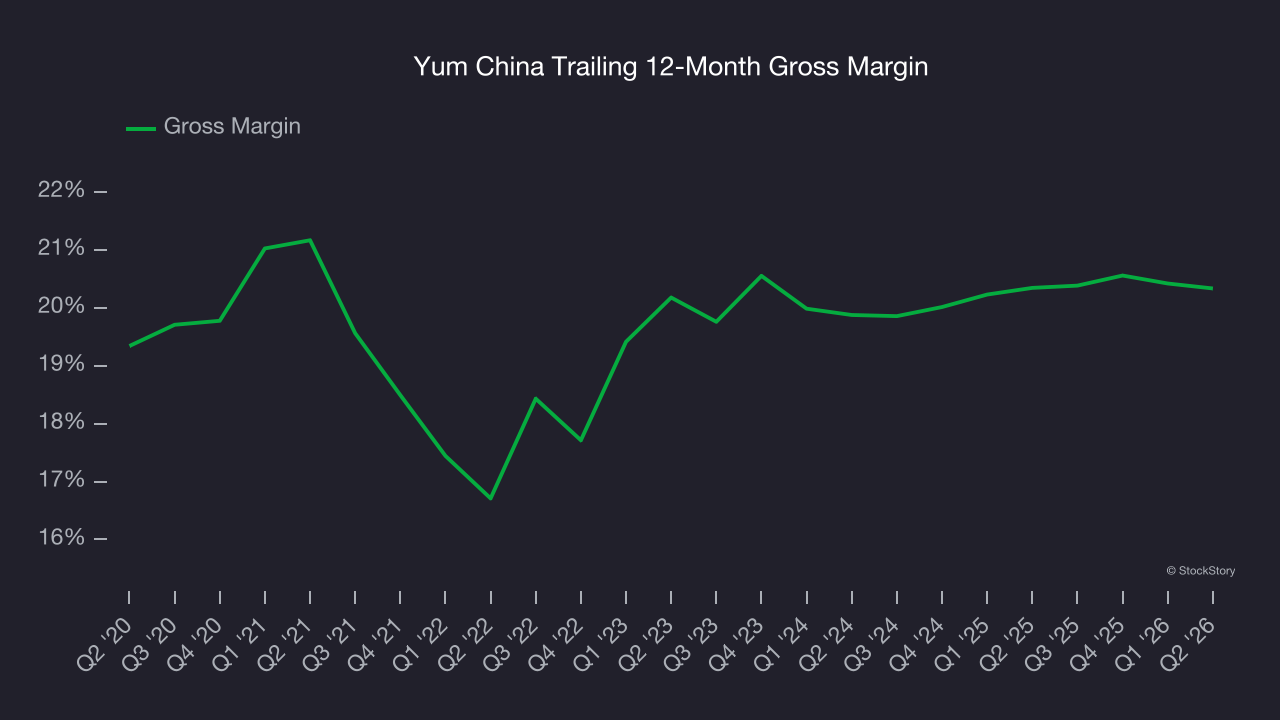
Yum China has bad unit economics for a restaurant company, giving it less room to reinvest and grow its presence. As you can see below, it averaged a 20.3% gross margin over the last two years. That means Yum China paid its suppliers a lot of money ($79.66 for every $100 in revenue) to run its business.
Final Judgment
Yum China’s business quality ultimately falls short of our standards. After the recent drawdown, the stock trades at 14.2× forward P/E (or $44.87 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re fairly confident there are better stocks to buy right now. We’d suggest looking at the Amazon and PayPal of Latin America.
Stocks We Like More Than Yum China
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.