Telecom software provider Amdocs (NASDAQ: DOX) met Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q4 2026), with revenue up 3.8% year on year to $1.19 billion. On the other hand, next quarter’s revenue guidance of $975 million was less impressive, coming in 18.7% below analysts’ consensus estimates. Its non-GAAP profit of $1.98 per share was in line with analysts’ consensus estimates.
For more on Amdocs, read our free full research report.
Amdocs (DOX) Q3 CY2026 highlights:
- Revenue $1.19 billion vs S&P analysts’ consensus estimates of $1.19 billion (3.8% year-on-year growth, in line)
- Adjusted EPS $1.98 vs S&P analysts’ consensus estimates of $1.98 (in line)
- Revenue guidance $975 million at the midpoint for Q4 CY2026, below analysts’ consensus estimates of $1.20 billion
- Adjusted EPS guidance $1.30 at the midpoint for Q4 CY2026, below analysts’ consensus estimates of $1.93
- Operating margin 15.8%, an increase from 11.5% in the same quarter last year
- Free cash flow margin 10.2%, a decline from 17.3% in the same quarter last year
- Backlog $3.5 billion at quarter end, a decline of 16.5% year on year
- Market capitalization $6.63 billion
"We delivered solid fourth quarter and full year fiscal 2026 results, consistent with our guidance, and I want to thank our employees around the world for their focus and commitment. I took over as CEO two quarters ago, and since then we have moved fast to develop a new growth strategy and are busy executing it. The core pillar of that strategy is aOS, our Agentic Operating System for telco, which is quickly gaining market traction. Today we announced a significant, eight-year strategic agreement with AT&T, our largest customer. It expands our longstanding partnership by pairing aOS with AT&T's AI-enabled delivery framework to modernize its business and customer operations. On top of AT&T, we are also excited to announce another three major strategic aOS deals with VodafoneThree in UK, VEON in Eurasia and Globe in Philippines. Together, these deals are great examples of how aOS is enabling Amdocs to expand its activities and becoming the trusted partner of choice for our customers' agentic journeys," said Shimie Hortig, president and chief executive officer of Amdocs Management Limited.
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years.
With $4.70 billion in revenue over the past 12 months, Amdocs is one of the larger companies in the business services industry and benefits from a well-known brand that influences purchasing decisions. However, its scale is a double-edged sword because it’s challenging to maintain high growth rates when it has already captured a large portion of the addressable market. To accelerate revenue growth, Amdocs likely needs to optimize its pricing or pursue new offerings and international expansion.
Amdocs’s revenue grew at a sluggish 1.8% compounded annual growth rate over the last five years. This shows it failed to generate meaningful demand.
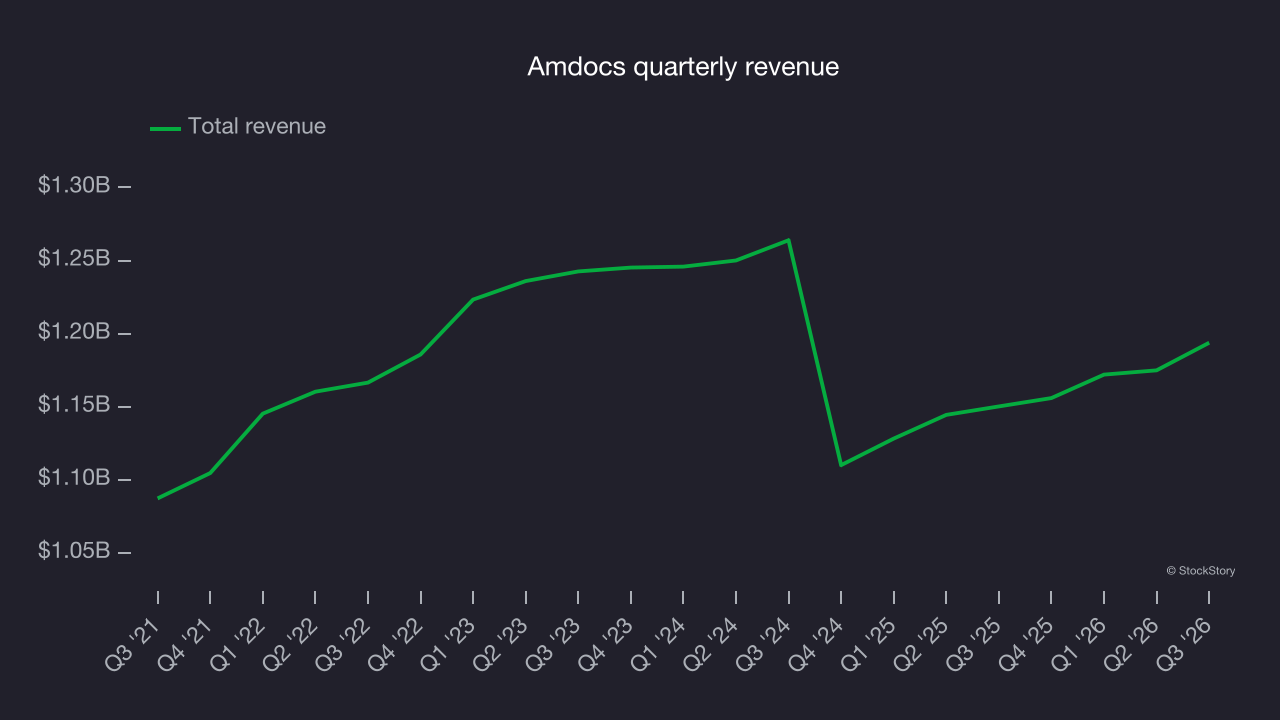
Long-term growth matters most, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. Amdocs’s performance shows it grew in the past but relinquished its gains over the last two years, as its revenue fell by 3.1% annually. 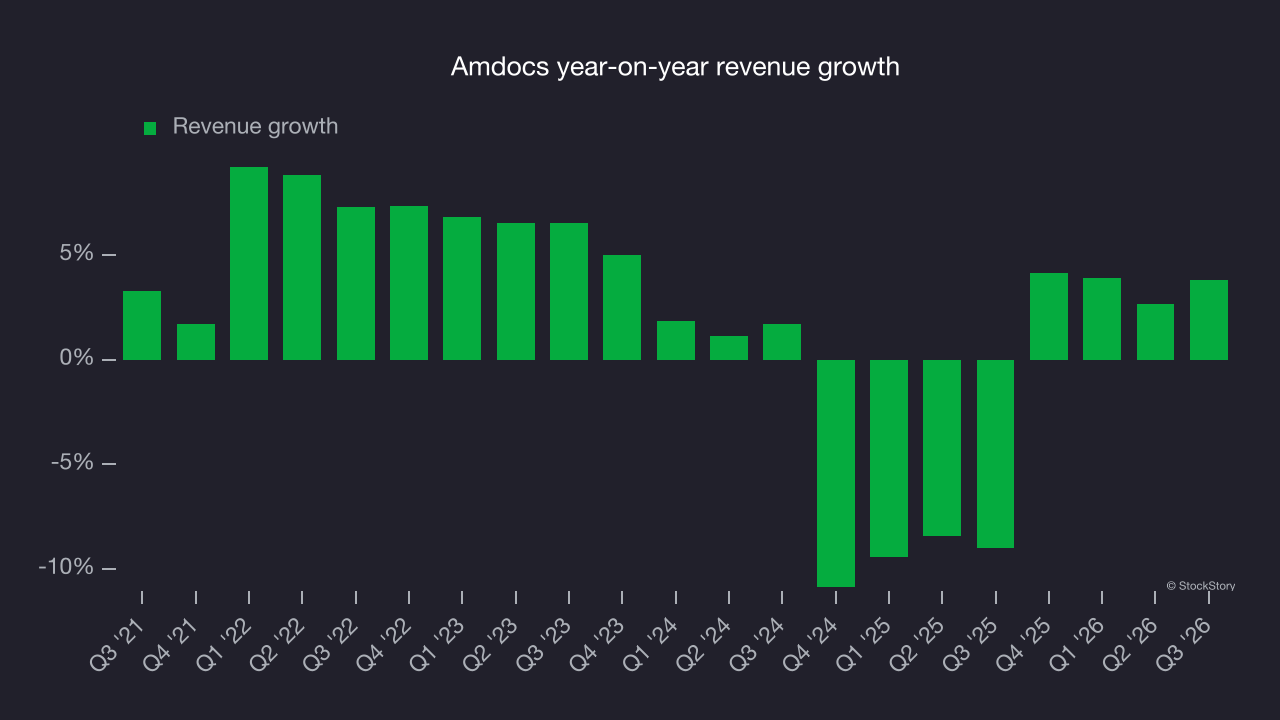
This quarter, Amdocs grew its revenue by 3.8% year on year, and its $1.19 billion of revenue was in line with Wall Street’s consensus estimates. Management is guiding for a 15.7% year-on-year decline in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 3.1% over the next 12 months, according to S&P. While this projection indicates its newer products and services will spur better top-line performance, it is still below the sector average.
Adjusted operating margin
Adjusted operating margin is a key measure of profitability. Think of it as net income (the bottom line) excluding the impact of non-recurring expenses, taxes and interest on debt – metrics less connected to business fundamentals.
Amdocs has operated efficiently over the last five years. It demonstrated high profitability for a business services company, with an average adjusted operating margin of 19%.
Amdocs’s adjusted operating margin rose by 2.5 percentage points over the last five years, as its revenue growth gave it operating leverage.
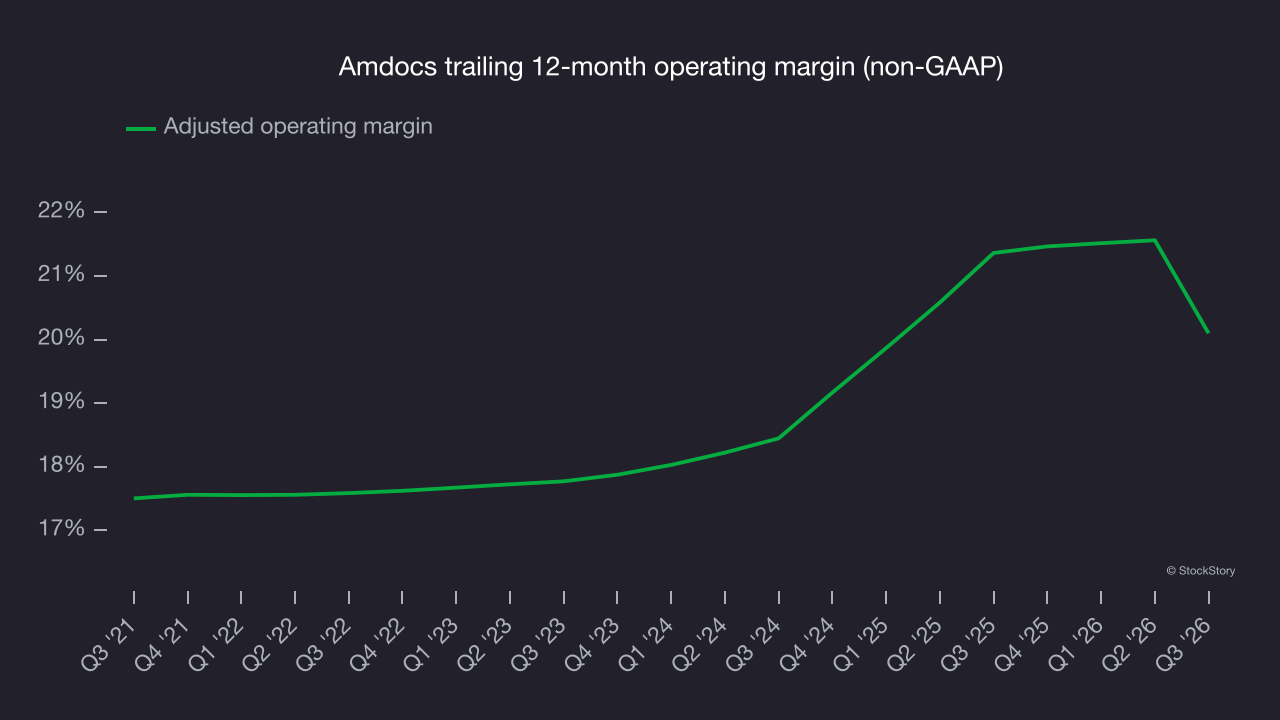
This quarter, Amdocs generated an adjusted operating margin of 15.8%, down 5.8 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Amdocs’s EPS grew at a 9.1% compounded annual growth rate over the last five years, higher than its 1.8% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
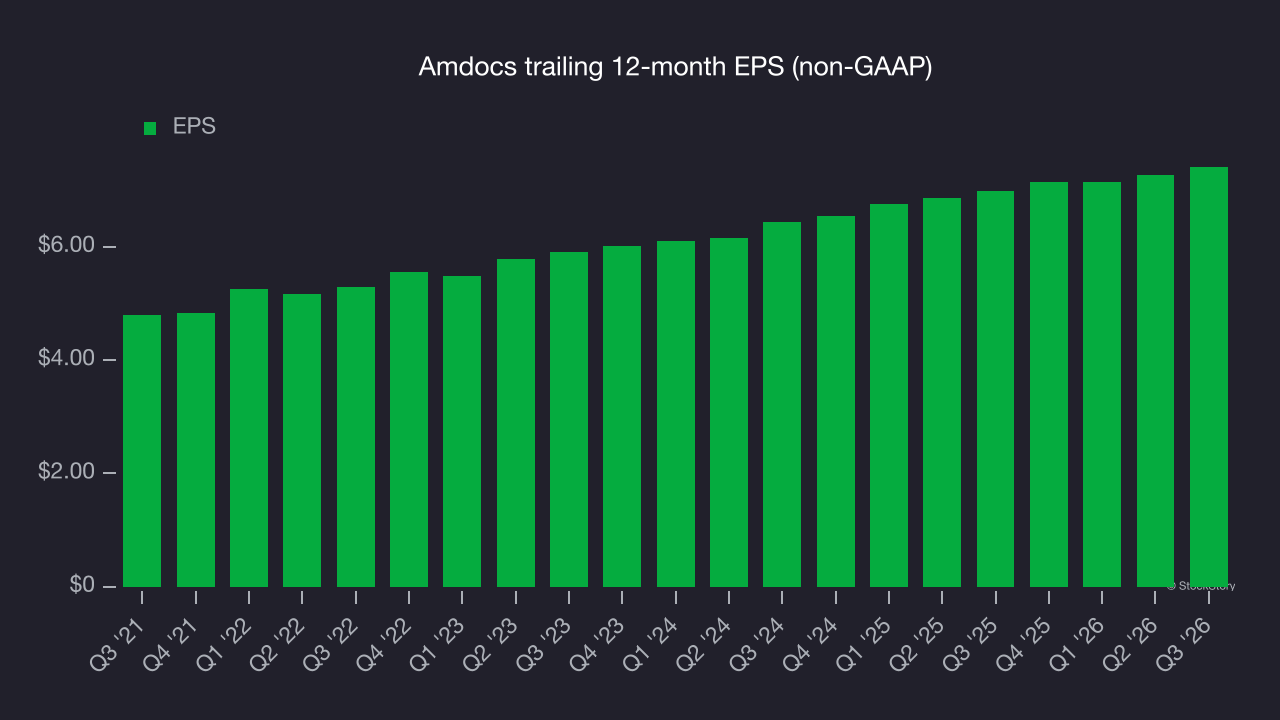
A closer look at Amdocs’s earnings helps explain its performance. As we mentioned earlier, Amdocs’s adjusted operating margin declined this quarter but expanded by 2.5 percentage points over the last five years. Its share count also shrank by 18.4%, and these factors together are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 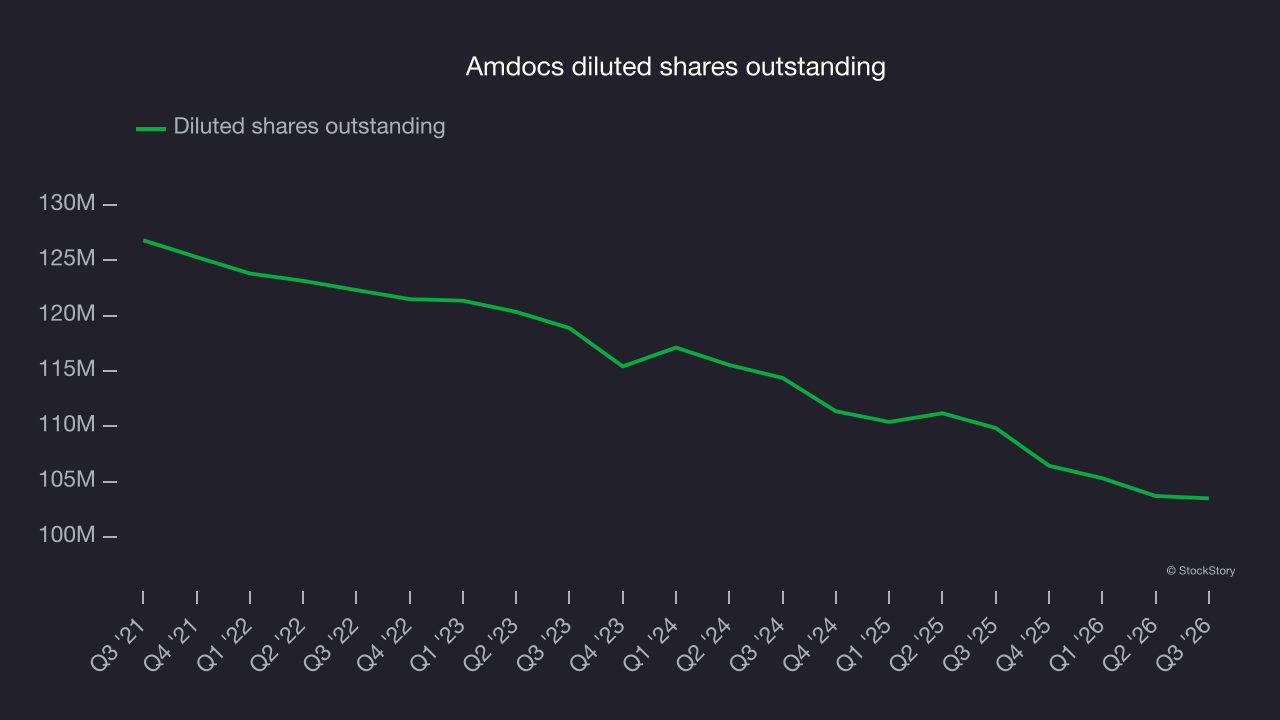
As with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Amdocs, its two-year annual EPS growth of 7.3% was lower than its five-year trend. A pickup in growth would be welcome.
In Q3, Amdocs reported adjusted EPS of $1.98, up from $1.83 in the same quarter last year. This result was close to analysts’ consensus estimates. Over the next 12 months, Wall Street expects Amdocs’s full-year EPS to grow 7% from $7.41 to $7.93, according to S&P.
Key takeaways from Amdocs’s Q3 results
Amdocs had a weaker quarter with few positives, and its outlook offered little relief. Revenue guidance for next quarter missed expectations, and EPS guidance also fell short of Wall Street’s consensus estimates. Shares plunged 40.3% to $37.29 immediately after the report.
Amdocs underperformed this quarter, but does that create a buying opportunity? The latest quarter matters, but not nearly as much as longer-term fundamentals and valuation when deciding whether the stock is a buy. For more on Amdocs, read our full research report here (it’s free).