
Work management platform monday.com (NASDAQ: MNDY) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 19.2% year on year to $377.5 million. On the other hand, next quarter’s revenue guidance of $381 million was less impressive, coming in 1.2% below analysts’ consensus estimates. Its non-GAAP profit of $2.14 per share was 55.6% above analysts’ consensus estimates.
For more on monday.com, read our free full research report.
monday.com (MNDY) Q3 2026 highlights:
- Revenue $377.5 million vs S&P analysts’ consensus estimates of $369.2 million (19.2% year-on-year growth, 2.2% beat)
- Adjusted EPS $2.14 vs S&P analysts’ consensus estimates of $1.37 (55.6% beat)
- Adjusted operating income $89.35 million vs analysts’ consensus estimates of $58.4 million (23.7% margin, 53% beat)
- Revenue guidance $381 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $385.7 million
- Operating margin 8.3%, up from -0.8% in the same quarter last year
- Free cash flow margin 4.2%, down from 14.4% in the previous quarter
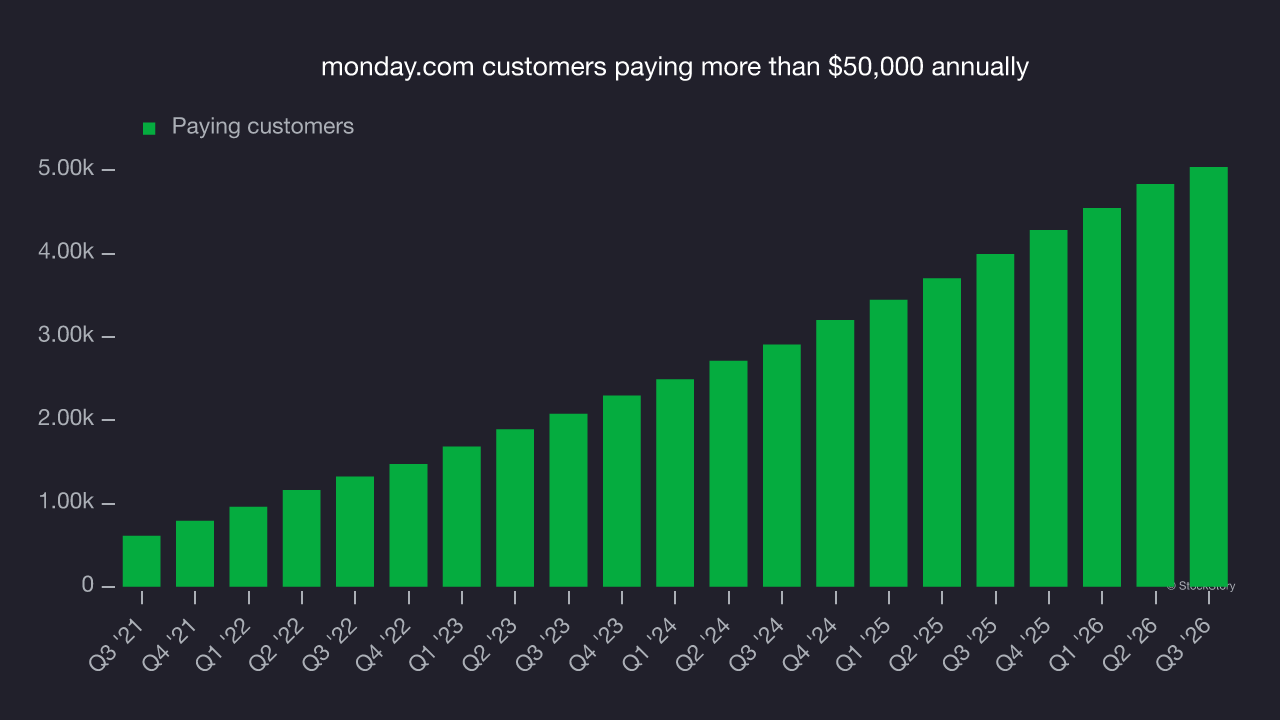
- Customers 5,038 customers paying more than $50,000 annually
- Net revenue retention rate 108%, down from 113% in the previous quarter
- Billings $374.8 million at quarter end, up 17.1% year on year
- Market capitalization $3.72 billion
“Our third quarter showed both the strength of our foundation and the work ahead,” said monday.com co-founders and co-CEOs Roy Mann and Eran Zinman. “Our business is undergoing a fundamental evolution, and we took significant steps this quarter to become an AI-first company. While we remain highly confident in this strategic path, an initiative of this scope introduces near-term operational headwinds, and we are committed to executing with discipline as we work through them.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Over the last five years, monday.com grew its revenue at a strong 40.3% compounded annual growth rate. Its growth surpassed the average software company and shows its offerings resonate with customers.
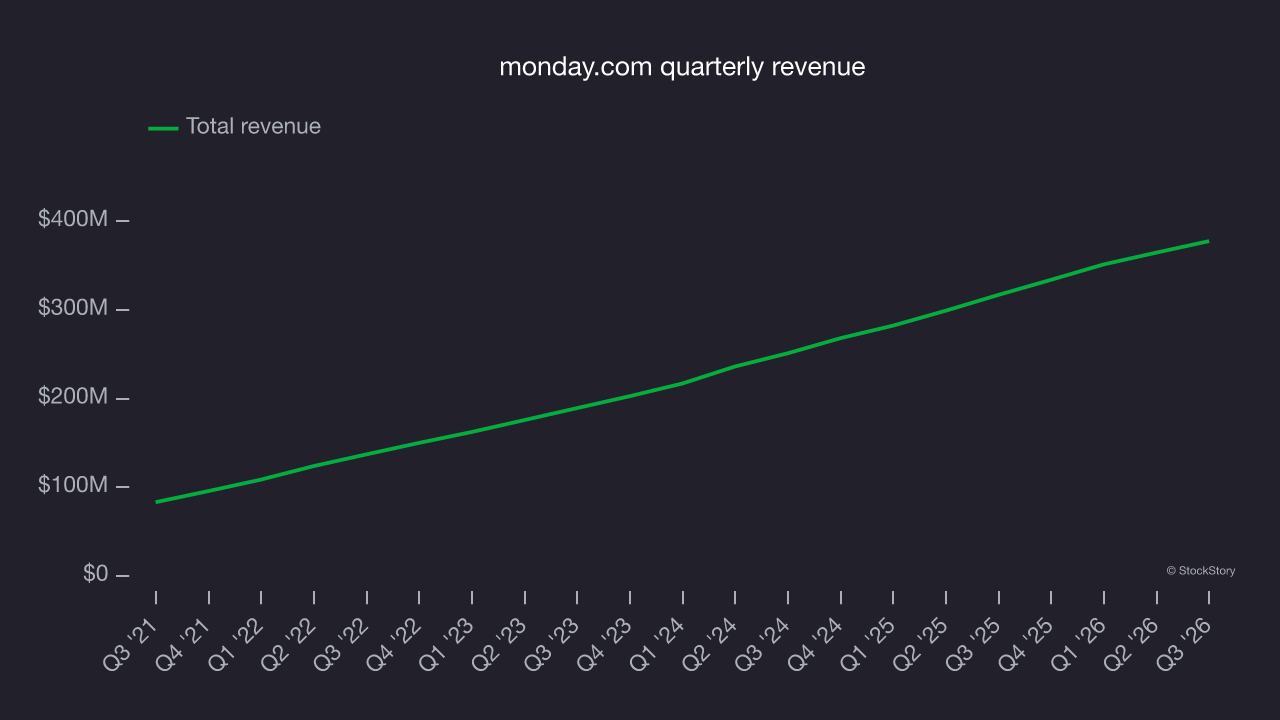
Long-term growth matters the most, but within software, a half-decade historical view may miss recent innovations or disruptive industry trends. monday.com’s annualized revenue growth of 25.5% over the last two years is below its five-year trend, but the results still suggest healthy demand. 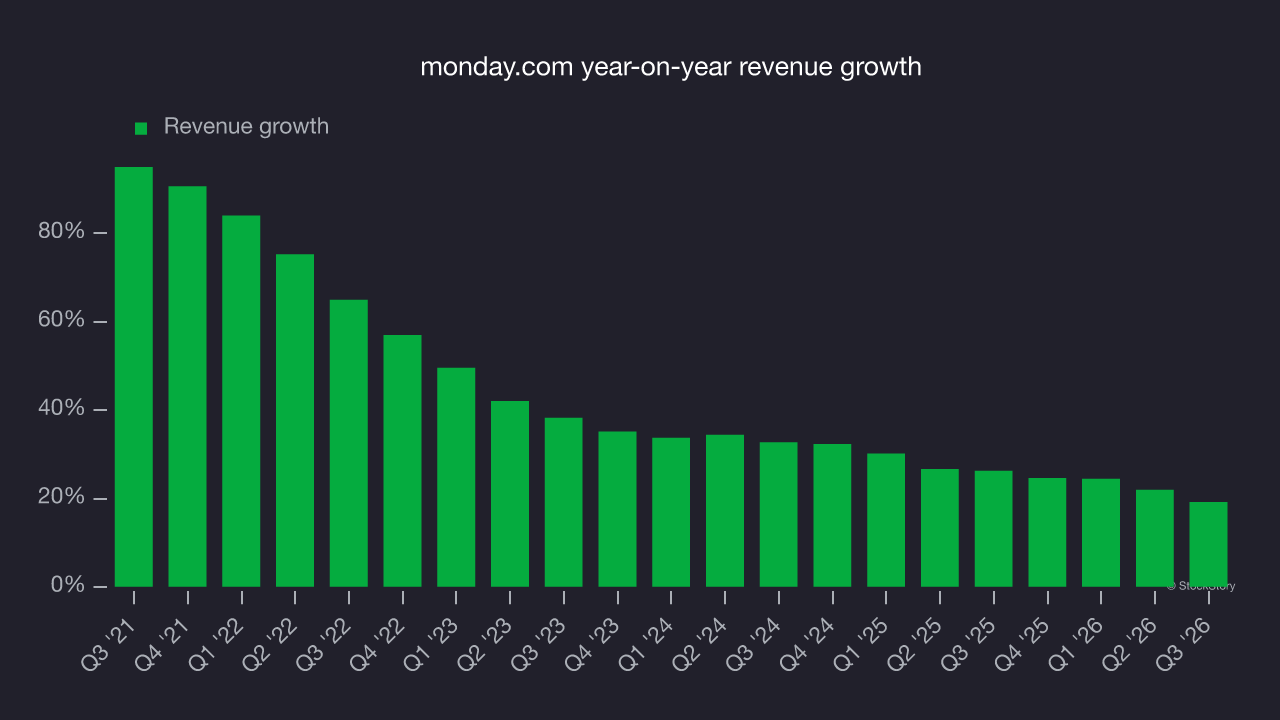
This quarter, monday.com reported year-on-year revenue growth of 19.2%, and its $377.5 million of revenue exceeded Wall Street’s consensus estimates by 2.2%. Company management is currently guiding for a 14.1% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 14.5% over the next 12 months, according to S&P, a deceleration versus the last two years. This underwhelming projection implies its products and services will face some demand challenges. On the positive side, the company is performing well on other measures of financial health.
Billings
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
monday.com’s billings came in at $374.8 million in Q3, and over the last four quarters, growth was healthy, averaging 18.4% year-on-year increases. This alternative top-line metric grew more slowly than total revenue, meaning the company recognizes revenue faster than it collects cash – a headwind for its liquidity that could also signal a slowdown in future revenue growth. 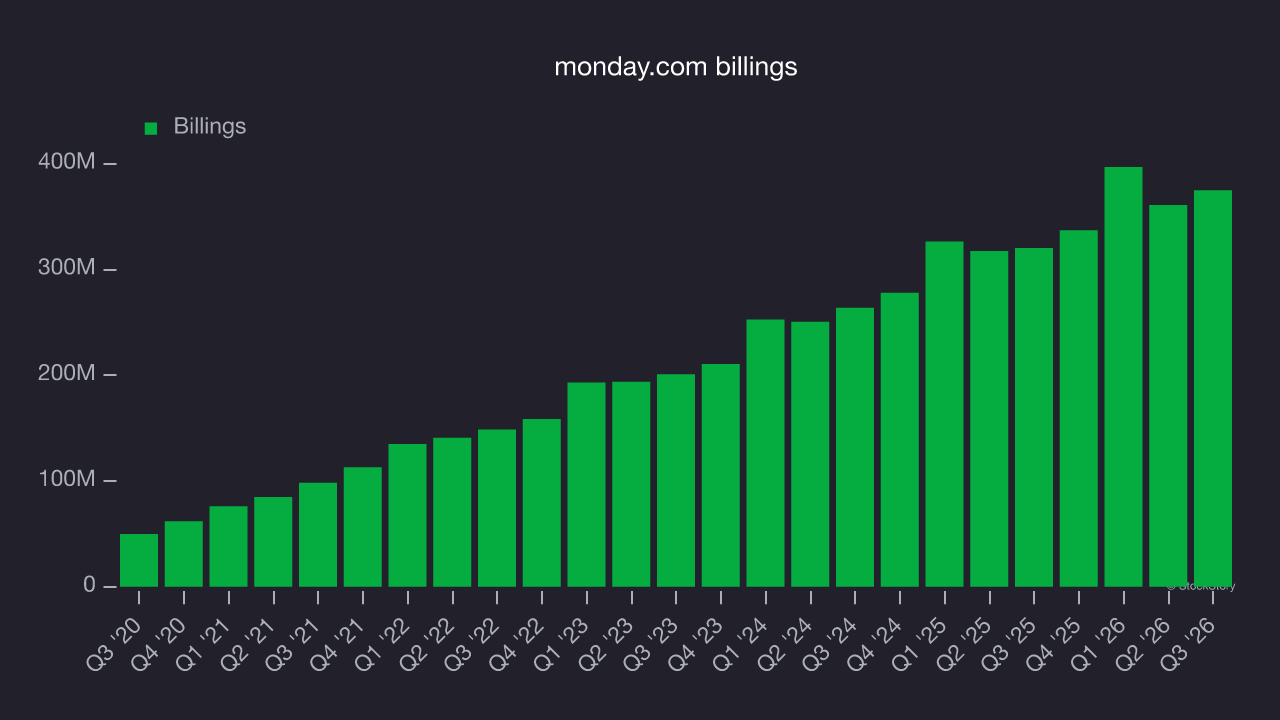
Enterprise customer base
This quarter, monday.com reported 5,038 enterprise customers paying more than $50,000 annually, an increase of 204 from the previous quarter. That represents considerably fewer contract wins than last quarter but is about in line with the pace over the previous year, suggesting the company still has steady sales momentum despite the weaker quarter.
Key takeaways from monday.com’s Q3 results
monday.com’s revenue beat Wall Street’s consensus estimates, and adjusted operating income came in well ahead of analysts’ consensus expectations. But slightly below-consensus revenue guidance for next quarter and a decline in net revenue retention made this a weaker quarter overall. Shares tumbled 5% to $83.49 immediately after the report.
monday.com’s latest quarter was underwhelming. One earnings report doesn’t define a company’s quality, though, so let’s examine the stock at its current price. The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation when deciding whether to invest. For more on those factors, read our full research report here (it’s free).