
Electronics manufacturing services company Sanmina (NASDAQ: SANM) reported calendar Q3 2026 (fiscal Q4 2026) results beating Wall Street’s revenue expectations, as revenue rose 84% year on year to $3.86 billion. In addition, next quarter’s revenue guidance ($3.95 billion at the midpoint) was a positive surprise, coming in 11.2% above analysts’ consensus estimates. Its non-GAAP profit of $4.43 per share was 35.5% above analysts’ consensus estimates.
For more on Sanmina, read our full research report for free.
Sanmina (SANM) Q3 CY2026 highlights:
- Revenue $3.86 billion vs S&P analyst consensus of $3.48 billion (84% year-on-year growth, 10.8% beat)
- Adjusted EPS $4.43 vs S&P analyst consensus of $3.27 (35.5% beat)
- Adjusted operating income $348.1 million vs analysts’ consensus estimates of $266.9 million (9% margin, 30.4% beat)
- Revenue guidance $3.95 billion at the midpoint for Q4 CY2026, above analysts’ consensus estimates of $3.55 billion
- Adjusted EPS guidance $16.50 at the midpoint for fiscal 2027, beating analysts’ consensus estimates by 17.2%
- Operating margin 6%, in line with the same quarter last year
- Free cash flow margin 2.2%, down from 6.5% in the same quarter last year
- Market capitalization $7.22 billion
"Our fiscal 2026 results were exceptional. Revenue grew 79%, non-GAAP operating profit increased 130%, and non-GAAP diluted earnings per share more than doubled compared to a year ago. These results reflect our disciplined execution, robust financial management, and targeted diversification across and within our customers and end markets. Additionally, we generated strong cash flow from operations of $944 million, which provided the flexibility to fund strategic investments in new capabilities and capacity, further strengthening our position in the market while maintaining a very healthy balance sheet."
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Sanmina grew its revenue at a strong 16.6% compounded annual growth rate. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
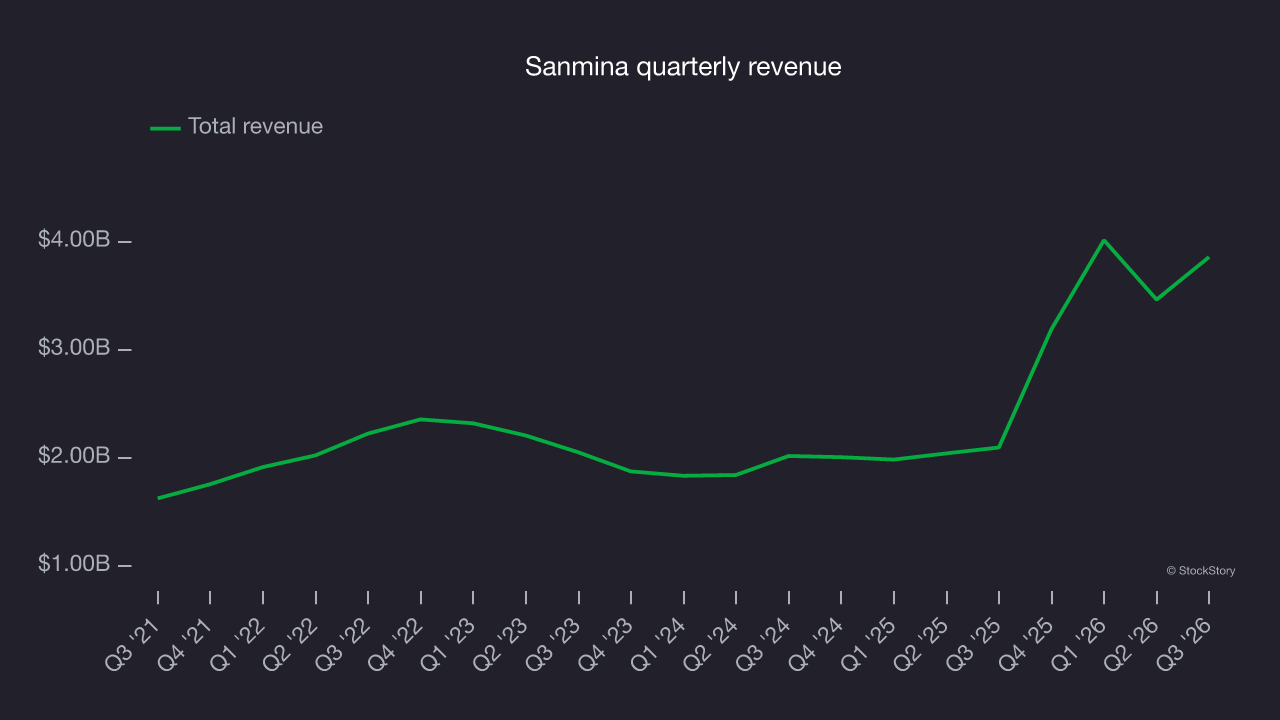
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Sanmina’s annualized revenue growth of 38.5% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 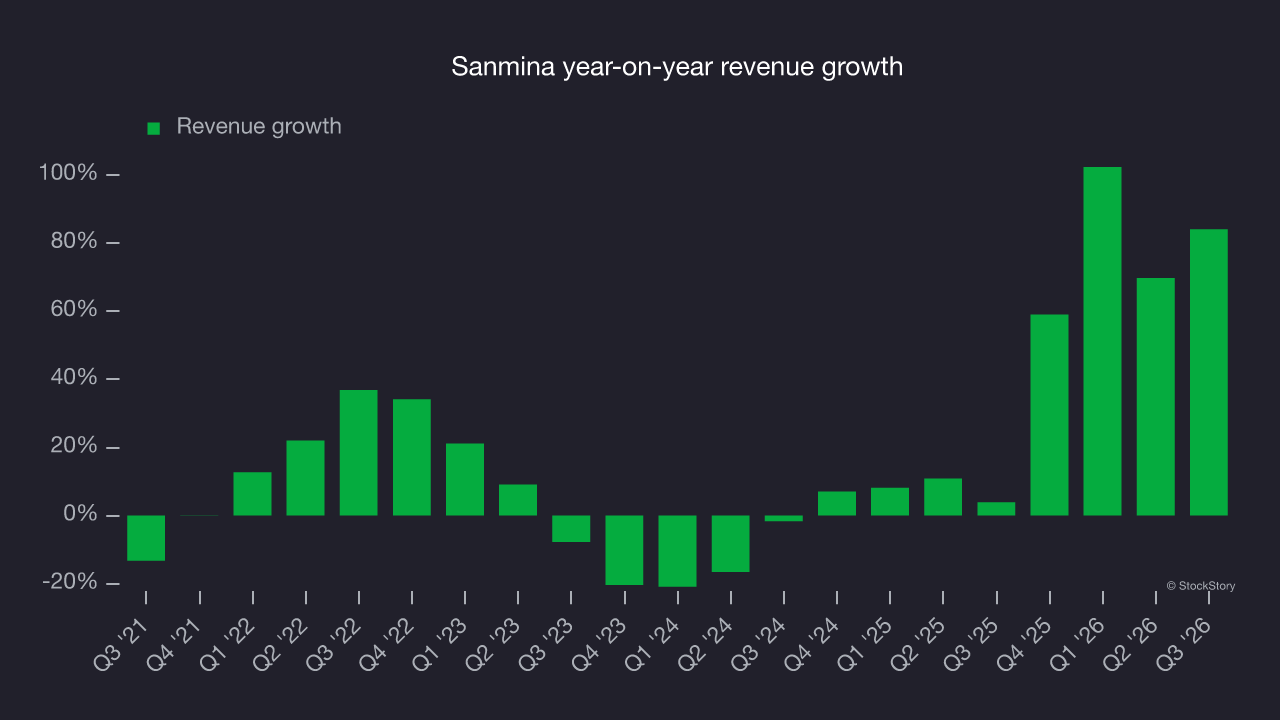
This quarter, Sanmina reported year-on-year revenue growth of 84%, and its $3.86 billion of revenue beat Wall Street’s consensus estimates by 10.8%. Management is guiding for a 23.8% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 11.9% over the next 12 months, according to S&P, a deceleration versus the last two years. Still, this projection is strong given its scale and implies the market expects success for its products and services.
Operating margin
Over the last five years, Sanmina’s operating margin rose by 1.2 percentage points. This improvement shows its costs declined relative to revenue. Its trailing 12-month operating margin was 5.7%.
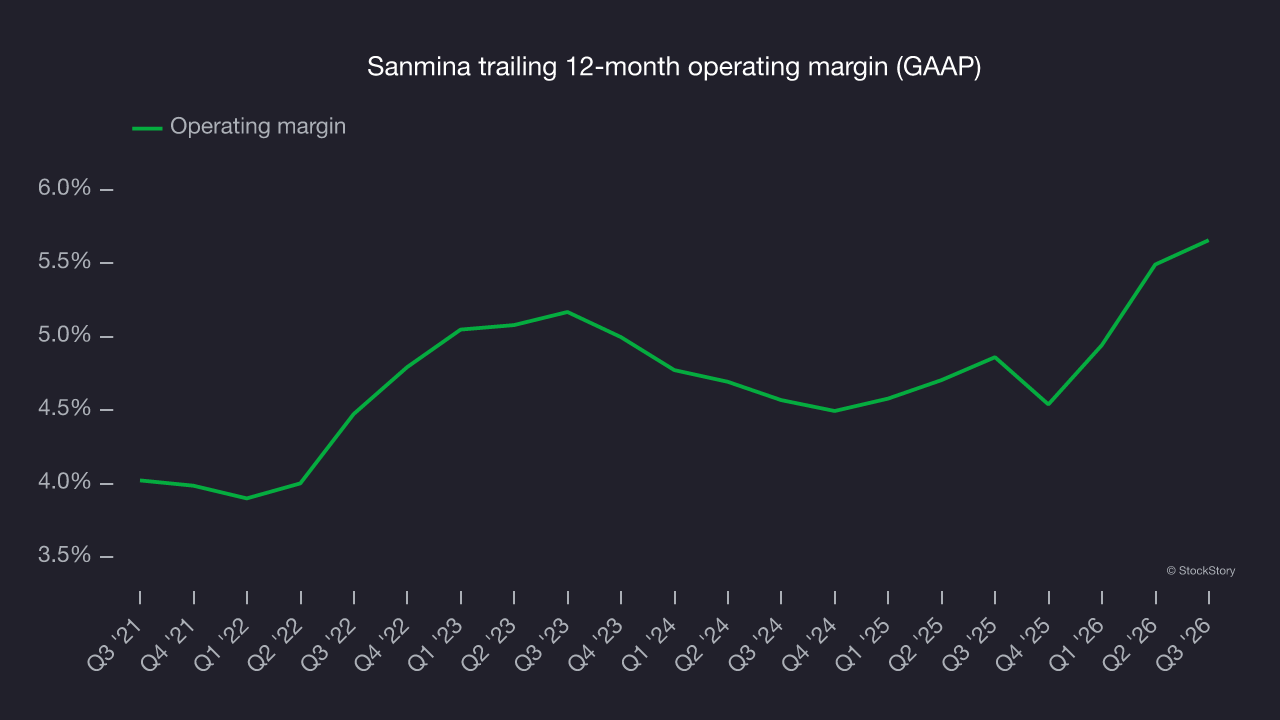
In Q3, Sanmina generated an operating profit margin of 6%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Sanmina’s EPS grew at a 27.3% compounded annual growth rate over the last five years, higher than its 16.6% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
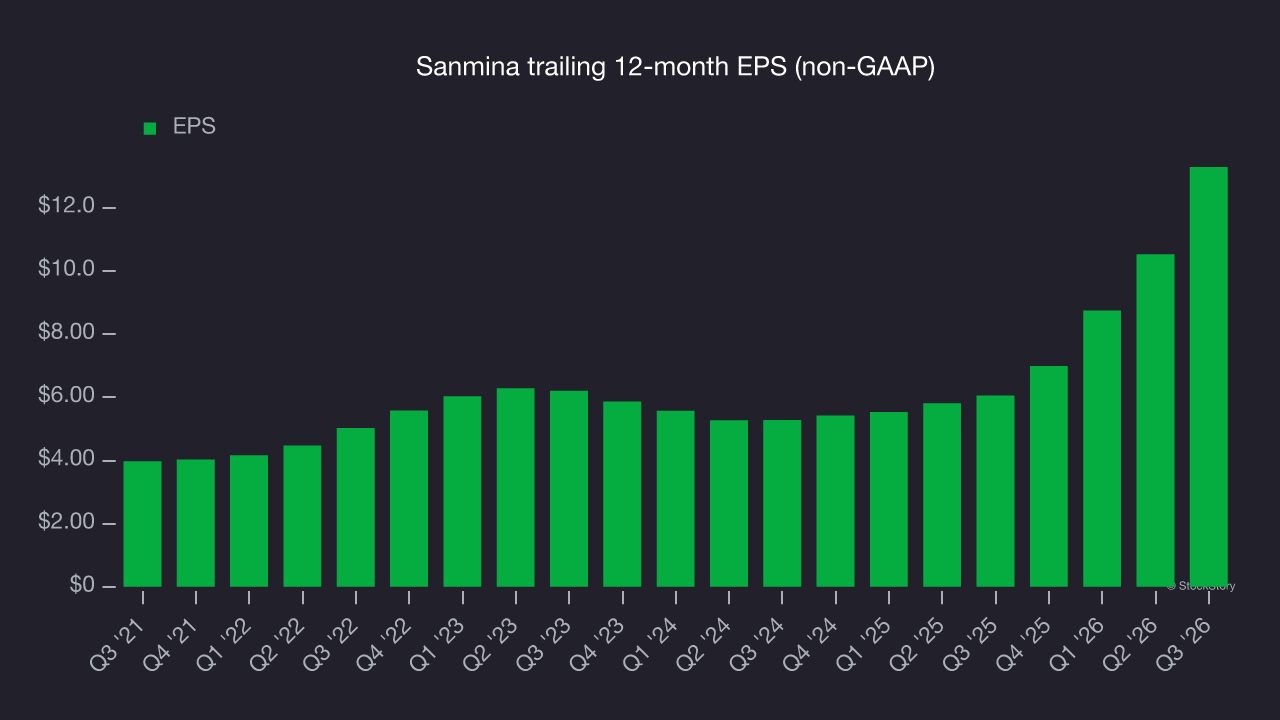
Diving into Sanmina’s quality of earnings can give us a better understanding of its performance. As we mentioned earlier, Sanmina’s operating margin was flat this quarter but expanded by 1.2 percentage points over the last five years. On top of that, its share count shrank by 18%. These are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 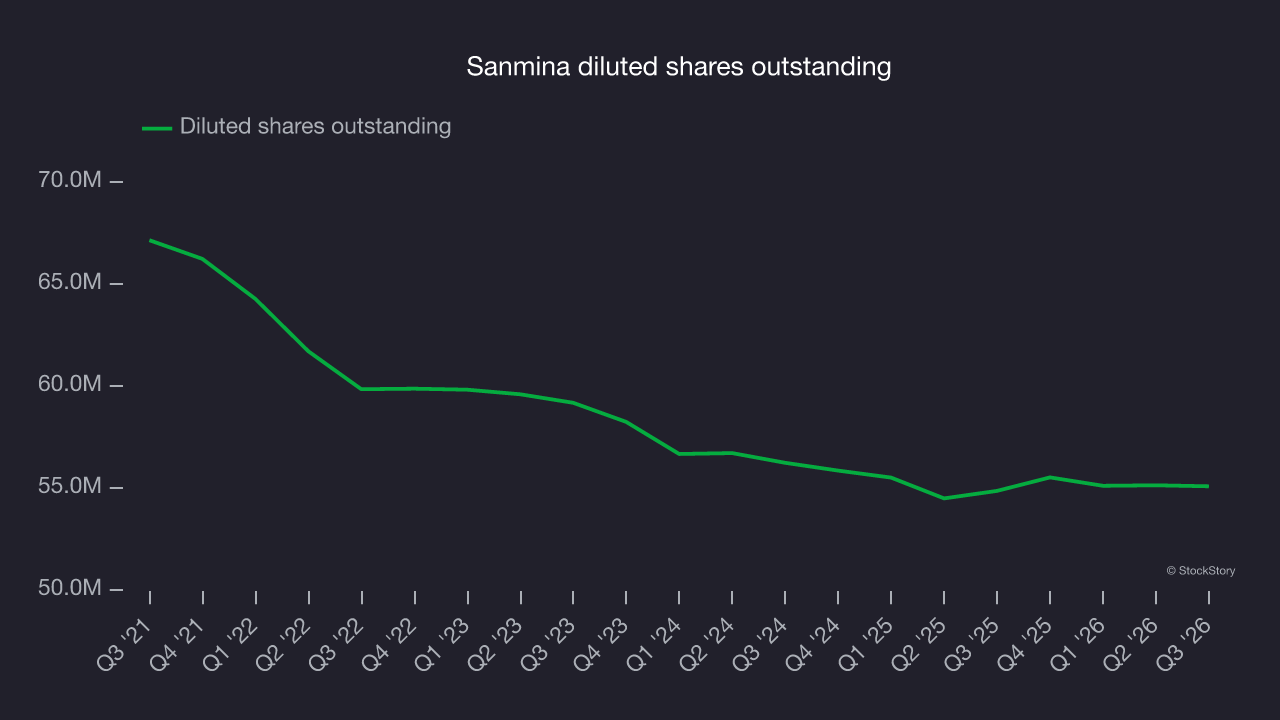
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Sanmina, its two-year annual EPS growth of 58.6% was higher than its five-year trend. That acceleration is a positive sign, particularly given the already high base.
In Q3, Sanmina reported adjusted EPS of $4.43, up from $1.67 in the same quarter last year. The result was well above analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects Sanmina’s full-year EPS to grow 2.3% from $13.28 to $13.59, according to S&P.
Key takeaways from Sanmina’s Q3 results
Strong EPS guidance for next quarter, well ahead of analysts’ consensus estimates, was a highlight of Sanmina’s report. EPS also topped Wall Street’s consensus estimates, giving the quarter some clear positives. Shares soared 19.8% to $179.28 immediately after the release.
Sanmina had a solid quarter, but the investment case depends on the bigger picture. The latest quarter matters, but longer-term business quality and valuation matter more when deciding whether to invest in the stock. For more on Sanmina, read the full research report here (it’s free).