Digital vehicle marketplace OPENLANE (NYSE: OPLN) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue up 12.6% year on year to $561.2 million. Its non-GAAP profit of $0.43 per share was 13.6% above analysts’ consensus estimates.
For more on OPENLANE, read our free full research report.
OPENLANE (OPLN) Q3 2026 highlights:
- Revenue $561.2 million vs S&P analysts’ consensus estimates of $554.1 million (12.6% year-on-year growth, 1.3% beat)
- Adjusted EPS $0.43 vs S&P analysts’ consensus estimates of $0.38 (13.6% beat)
- Adjusted EBITDA $106.8 million vs analysts’ consensus estimates of $101.9 million (19% margin, 4.9% beat)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $1.48 at the midpoint, a 2.4% increase
- EBITDA guidance $395 million at the midpoint for the full year, in line with analysts’ consensus expectations
- Operating margin 12.5%, up from 11% in the same quarter last year
- Free cash flow margin 14.8%, down from 28.2% in the same quarter last year
- Market capitalization $4.77 billion
"The positive momentum OPENLANE sustained in the third quarter reinforces the strength of our strategy and the differentiated value we deliver to the market," said Peter Kelly, CEO of OPENLANE. "We grew consolidated revenue by 13%, delivered Adjusted EBITDA of $107 million and grew marketplace GMV by 38% to $10 billion. Our US dealer volumes grew 22%, meaningfully outpacing the industry, while our commercial business accelerated from the upward inflection of off-lease volumes. And we believe the recent changes to our competitive landscape provide OPENLANE with a unique opportunity to gain additional market share."
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years.
With $2.14 billion in revenue over the past 12 months, OPENLANE is a mid-sized business services company, which sometimes brings disadvantages compared to larger competitors benefiting from better economies of scale. On the positive side, it can still achieve high growth rates because it’s working from a smaller revenue base.
OPENLANE grew its revenue at a decent 5.7% compounded annual growth rate over the last five years. This shows its offerings generated slightly more demand than the average business services company.
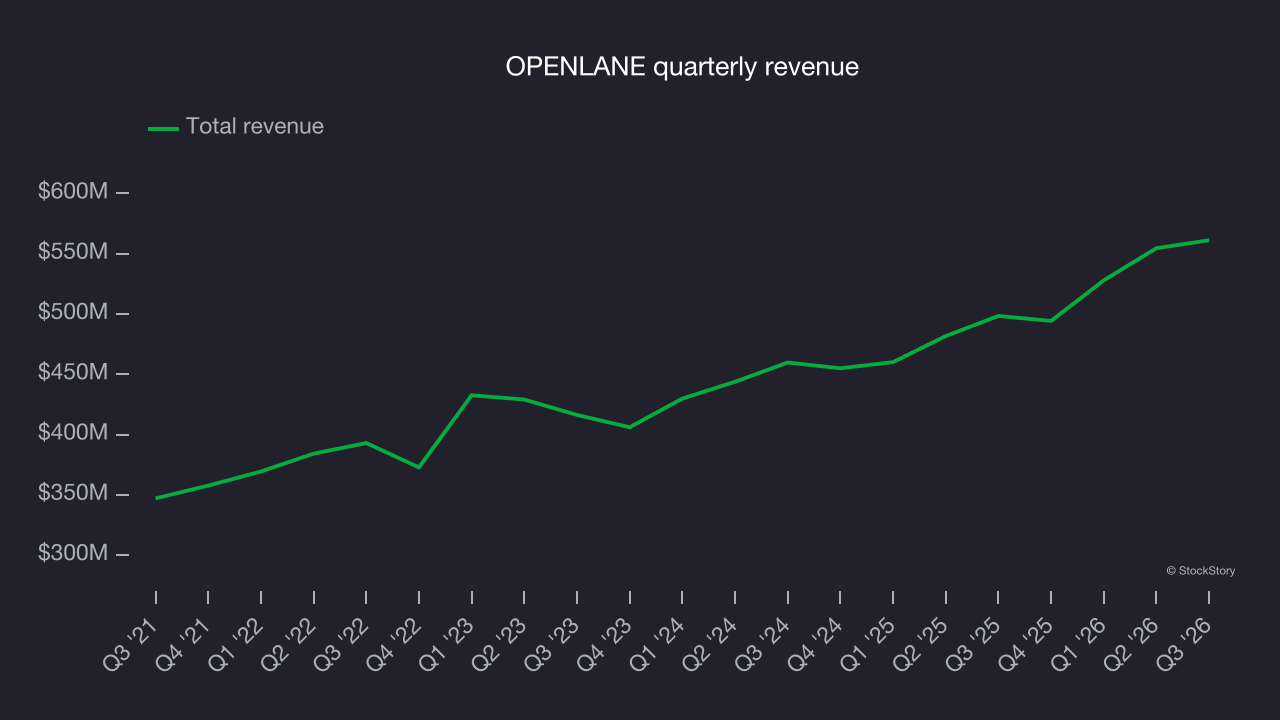
Long-term growth matters most, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. OPENLANE’s annualized revenue growth of 10.9% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 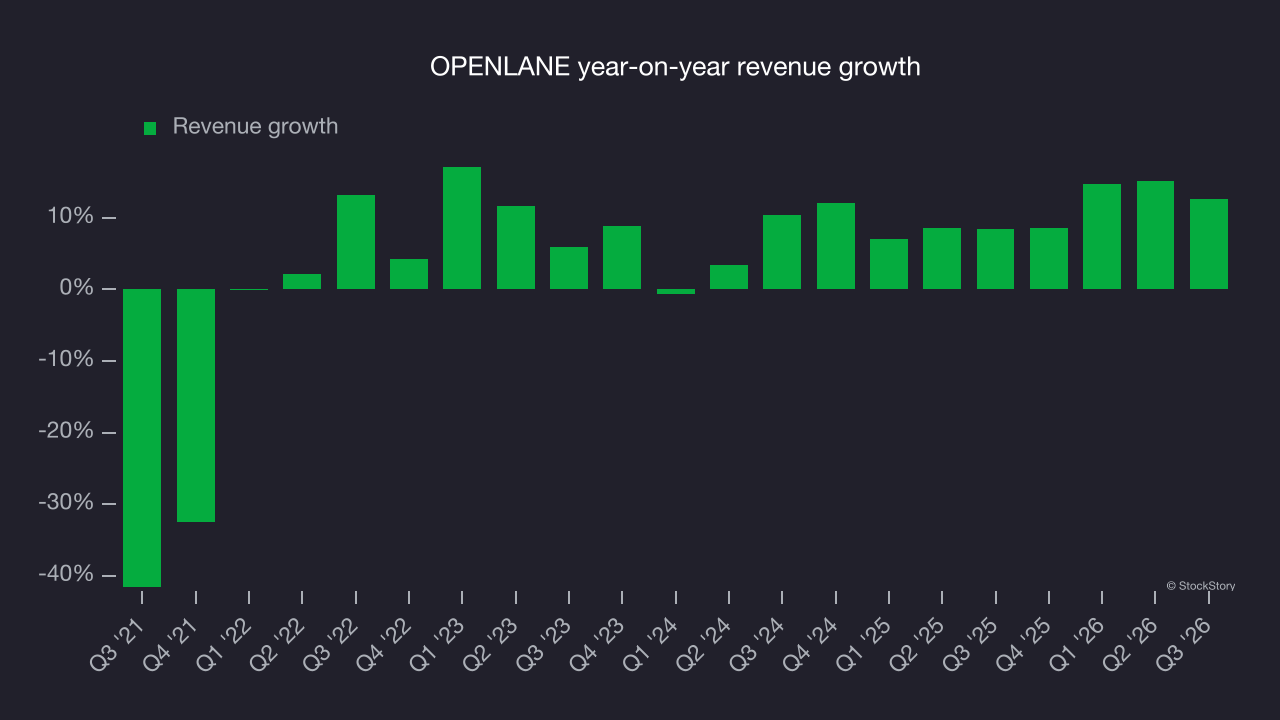
This quarter, OPENLANE reported year-on-year revenue growth of 12.6%, and its $561.2 million in revenue exceeded Wall Street’s consensus estimates by 1.3%.
Looking ahead, sell-side analysts expect revenue to grow 9.8% over the next 12 months, according to S&P, similar to its two-year rate. Still, this projection is healthy and indicates the market sees success for its products and services.
Adjusted operating margin
Adjusted operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies because it excludes non-recurring expenses, interest on debt and taxes.
OPENLANE was profitable over the last five years but held back by its large cost base. Its average adjusted operating margin of 8.5% was weak for a business services company.
On the positive side, OPENLANE’s adjusted operating margin rose by 4 percentage points over the last five years, as its revenue growth gave it operating leverage.
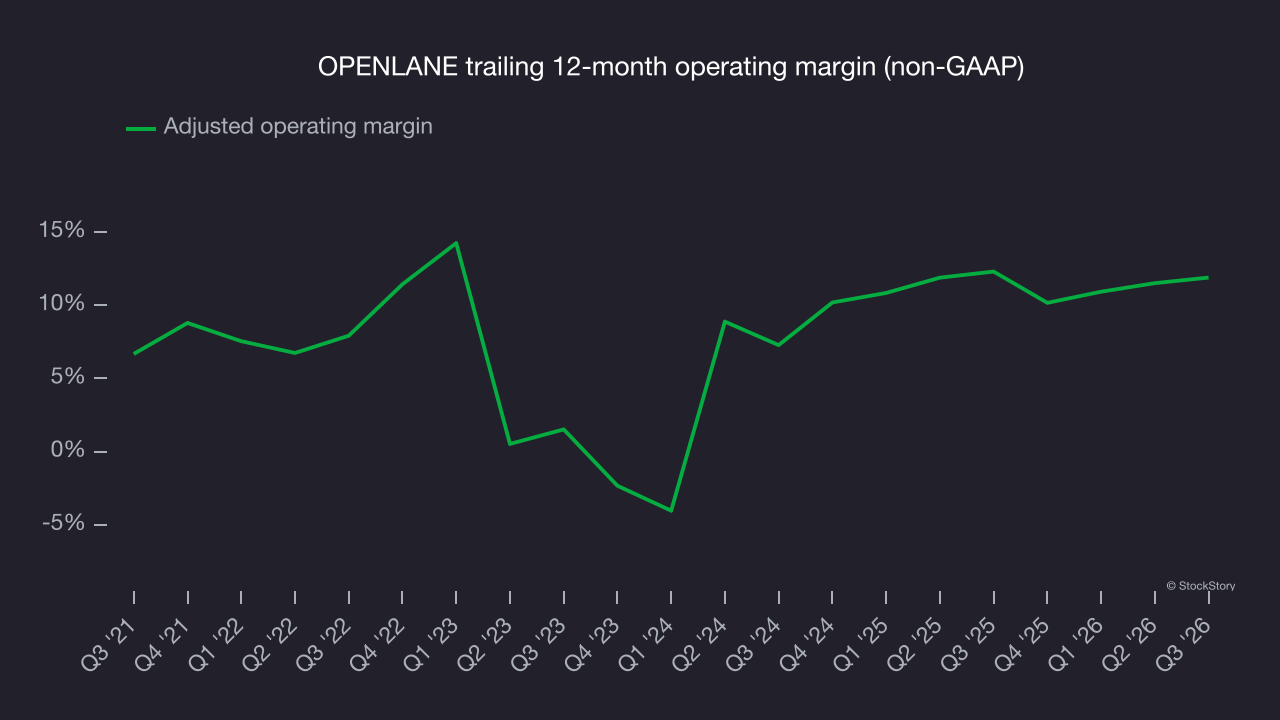
This quarter, OPENLANE generated an adjusted operating margin of 12.5%, up 1.5 percentage points year on year. This improvement shows it was more efficient.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
OPENLANE’s EPS grew at a 16.4% compounded annual growth rate over the last five years, higher than its 5.7% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
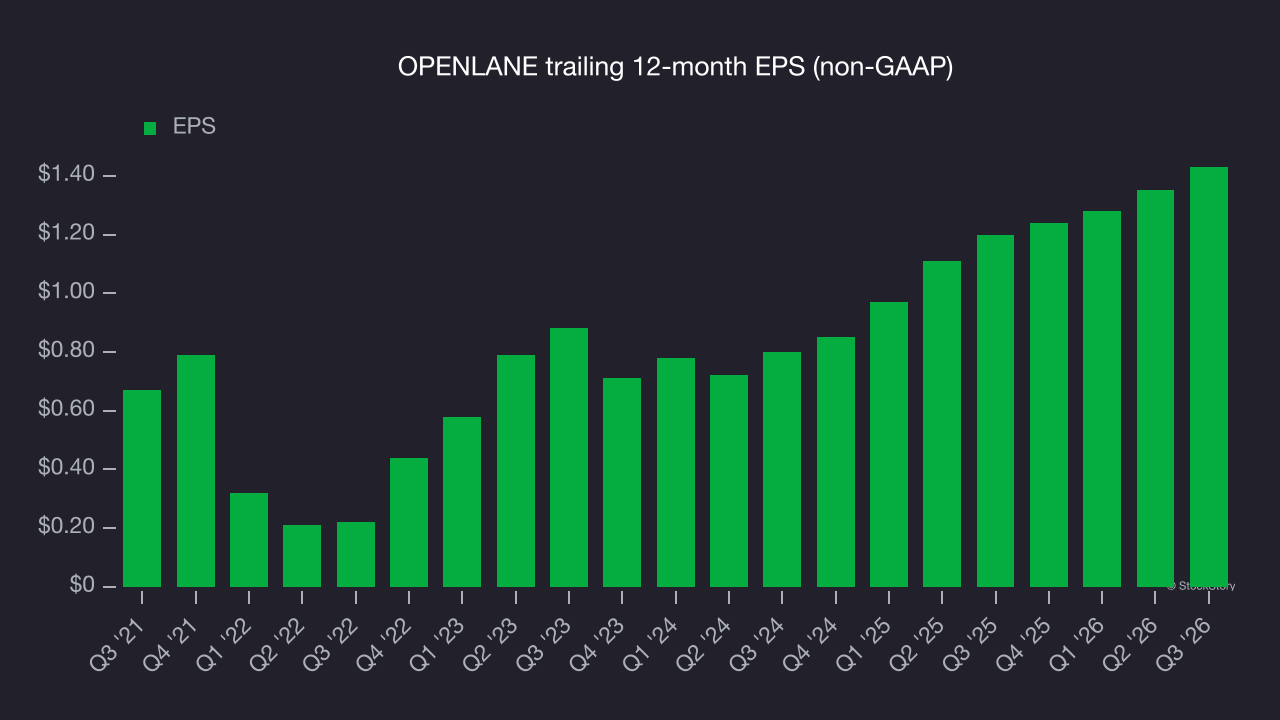
A closer look at OPENLANE’s earnings quality helps explain the drivers of its performance. As mentioned earlier, OPENLANE’s adjusted operating margin expanded by 4 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
As with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For OPENLANE, its two-year annual EPS growth of 33.7% was higher than its five-year trend. That acceleration is a positive sign, especially given the already high growth baseline.
In Q3, OPENLANE reported adjusted EPS of $0.43, up from $0.35 in the same quarter last year. EPS came in well above analysts’ consensus estimates, a solid result for shareholders. Over the next 12 months, Wall Street expects OPENLANE’s full-year EPS to grow 15.8% from $1.43 to $1.66, according to S&P.
Key takeaways from OPENLANE’s Q3 results
OPENLANE delivered a solid quarter, with EPS above analysts’ consensus estimates and full-year EPS guidance also ahead of Wall Street’s consensus. Shares remained flat at $38.99 immediately after the release.
OPENLANE may have had a good quarter, but that alone doesn’t make the stock a buy. The latest quarter is only one part of assessing longer-term business quality. Quality, when combined with valuation, can help determine if the stock is a buy. For more on OPENLANE, read the full research report here (it’s free).