
Wrapping up Q2 earnings, we look at the numbers and key takeaways for the gas and liquid handling stocks, including Helios (NYSE: HLIO) and its peers.
Gas and liquid handling companies possess the technical know-how and specialized equipment to handle valuable (and sometimes dangerous) substances. Lately, water conservation and carbon capture–which requires hydrogen and other gasses as well as specialized infrastructure–have been trending up, creating new demand for products such as filters, pumps, and valves. On the other hand, gas and liquid handling companies are at the whim of economic cycles. Consumer spending and interest rates, for example, can greatly impact the industrial production that drives demand for these companies’ offerings.
The 12 gas and liquid handling stocks we track reported a strong Q2. As a group, revenues beat analysts’ consensus estimates by 2% while next quarter’s revenue guidance was 0.8% below.
While some gas and liquid handling stocks have fared somewhat better than others, they have collectively declined. On average, share prices are down 5% since the latest earnings results.
Helios (NYSE: HLIO)
Founded on the principle of treating others as one wants to be treated, Helios (NYSE: HLIO) designs, manufactures, and sells motion and electronic control components for various sectors.
Helios reported revenues of $231.9 million, up 9.1% year on year. This print exceeded analysts’ expectations by 0.7%. Overall, it was a very strong quarter for the company with full-year EPS guidance exceeding analysts’ expectations and EPS guidance for next quarter exceeding analysts’ expectations.
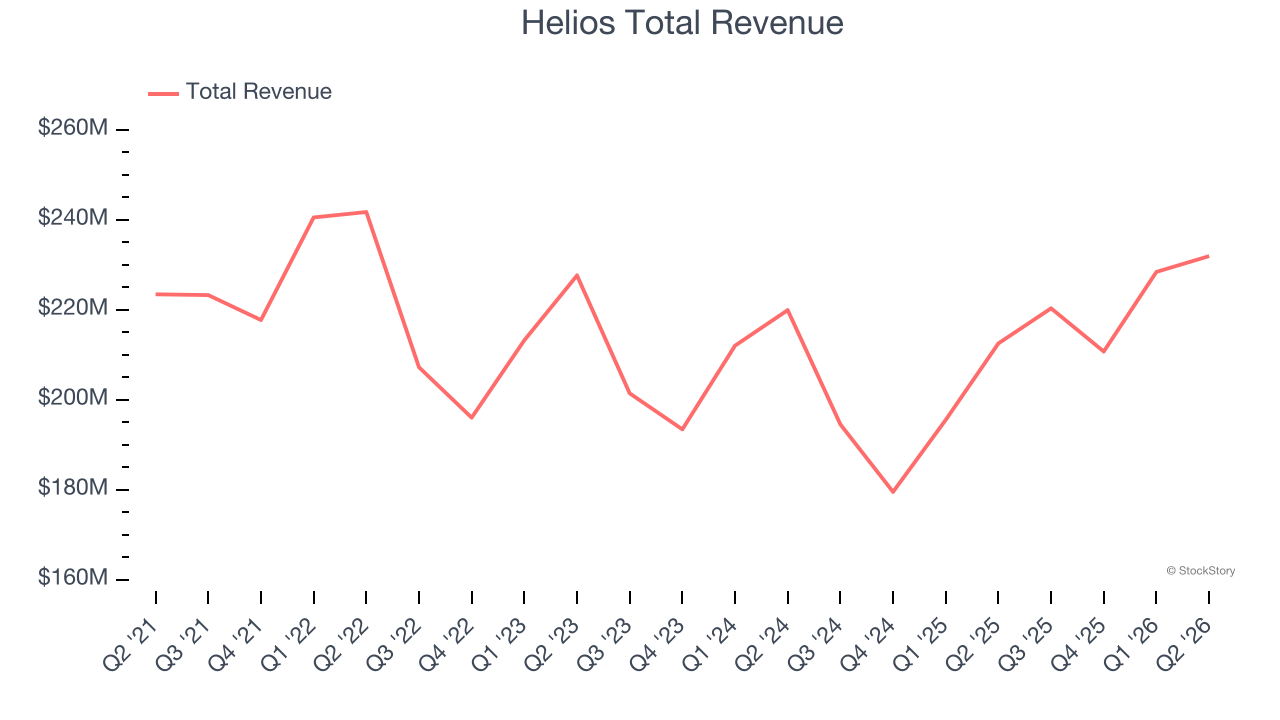
Helios delivered the weakest full-year guidance update in the group. Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 16.1% since reporting and currently trades at $68.36.
Is now the time to buy Helios? Access our full analysis of the earnings results here, it’s free.
Best Q2: SPX Technologies (NYSE: SPXC)
With roots dating back to 1912 as the Piston Ring Company, SPX Technologies (NYSE: SPXC) supplies specialized infrastructure equipment for HVAC systems and detection and measurement applications across industrial, commercial, and utility markets.
SPX Technologies reported revenues of $679 million, up 22.9% year on year, outperforming analysts’ expectations by 5.8%. The business had a stunning quarter with an impressive beat of analysts’ organic revenue estimates and a solid beat of analysts’ EBITDA estimates.
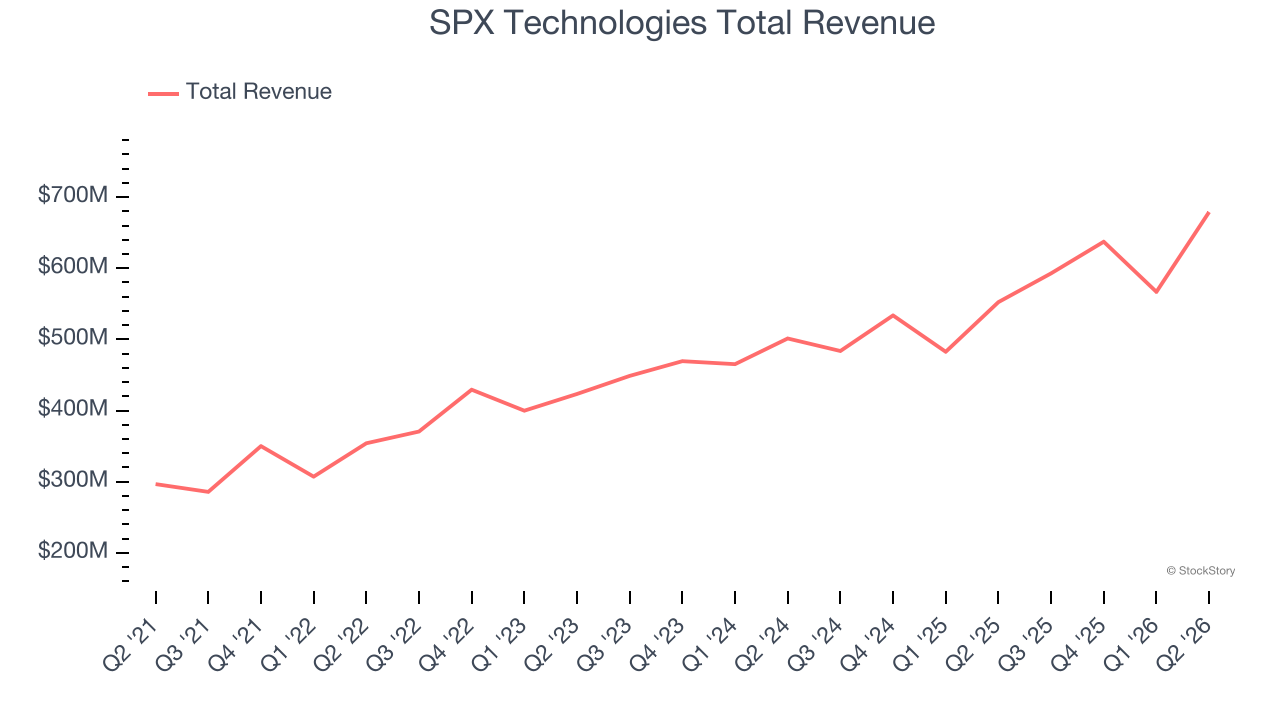
SPX Technologies pulled off the highest full-year guidance raise of the whole group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 13.5% since reporting. It currently trades at $172.46.
Is now the time to buy SPX Technologies? Access our full analysis of the earnings results here, it’s free.
Slowest Q2: Graco (NYSE: GGG)
Founded in 1926, Graco (NYSE: GGG) is an industrial company specializing in the development and manufacturing of fluid-handling systems and products.
Graco reported revenues of $590.6 million, up 3.3% year on year, falling short of analysts’ expectations by 3%. It was a slower quarter, leaving some shareholders looking for more.
Graco delivered the weakest performance against analyst estimates among its peers. Interestingly, the stock is up 4.4% since the results and currently trades at $77.16.
Read our full analysis of Graco’s results here.
Gorman-Rupp (NYSE: GRC)
Powering fluid dynamics since 1934, Gorman-Rupp (NYSE: GRC) has evolved from its Ohio origins into a global manufacturer and seller of pumps and pump systems.
Gorman-Rupp reported revenues of $186.1 million, up 3.9% year on year. This number came in 1.5% below analysts’ expectations. Zooming out, it was actually a satisfactory quarter as it put up an impressive beat of analysts’ EBITDA estimates.
The stock is down 6.3% since reporting and currently trades at $74.64.
Read our full, actionable report on Gorman-Rupp here, it’s free.
Flowserve (NYSE: FLS)
Manufacturing the largest pump ever built for nuclear power generation, Flowserve (NYSE: FLS) manufactures and sells flow control equipment for various industries.
Flowserve reported revenues of $1.17 billion, down 1.6% year on year. This print topped analysts’ expectations by 0.9%. Zooming out, it was a mixed quarter as it also recorded full-year EPS guidance beating analysts’ expectations but revenue guidance for next quarter missing analysts’ expectations significantly.
Flowserve had the weakest guidance update and slowest revenue growth in the group. The stock is up 7.6% since reporting and currently trades at $75.28.
Read our full, actionable report on Flowserve here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our 9 Best Market-Beating Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.