
Regional bank holding company CVB Financial (NASDAQ: CVBF) announced better-than-expected revenue in Q3 2026, with sales up 49% year on year to $195.6 million. Its GAAP profit of $0.44 per share was 11.4% above analysts’ consensus estimates.
Is now the time to buy CVB Financial? Find out by accessing our full research report, it’s free.
CVB Financial (CVBF) Q3 2026 highlights:
- Net Interest Income: $179.1 million vs analyst estimates of $175.4 million (54.9% year-on-year growth, 2.1% beat)
- Net Interest Margin: 3.9% vs analyst estimates of 3.7% (14.7 basis point beat)
- Revenue: $195.6 million vs analyst estimates of $193.3 million (49% year-on-year growth, 1.2% beat)
- Efficiency Ratio: 46.3% vs analyst estimates of 43.1% (318 basis point miss)
- EPS (GAAP): $0.44 vs analyst estimates of $0.40 (11.4% beat)
- Tangible Book Value per Share: $10.92 vs analyst estimates of $11.34 (flat year on year, 3.7% miss)
- Market Capitalization: $3.9 billion
David Brager, Chief Executive Officer of the Company, commented, “Our third-quarter results reflect solid financial performance, increased profitability, net interest margin expansion and disciplined expense management following the Heritage Bank of Commerce acquisition. The third quarter represented our 198th consecutive quarter of profitability. We remain focused on the integration, serving our customers and supporting our communities and associates as we extend our relationship-focused banking model across California’s major economic centers. We are grateful for the continued trust of our customers and the dedication of our associates.”
Company overview
With roots dating back to 1974 and a focus on serving small and medium-sized businesses, CVB Financial (NASDAQ: CVBF) operates Citizens Business Bank, providing banking, lending, and trust services to businesses and individuals across California.
Sales growth
In general, banks make money from two primary sources. The first is net interest income, which is interest earned on loans, mortgages, and investments in securities minus interest paid out on deposits. The second source is non-interest income, which can come from bank account, credit card, wealth management, investment banking, and trading fees. Regrettably, CVB Financial’s revenue grew at a tepid 6.7% compounded annual growth rate over the last five years. This fell short of our benchmark for the banking sector and is a tough starting point for our analysis.
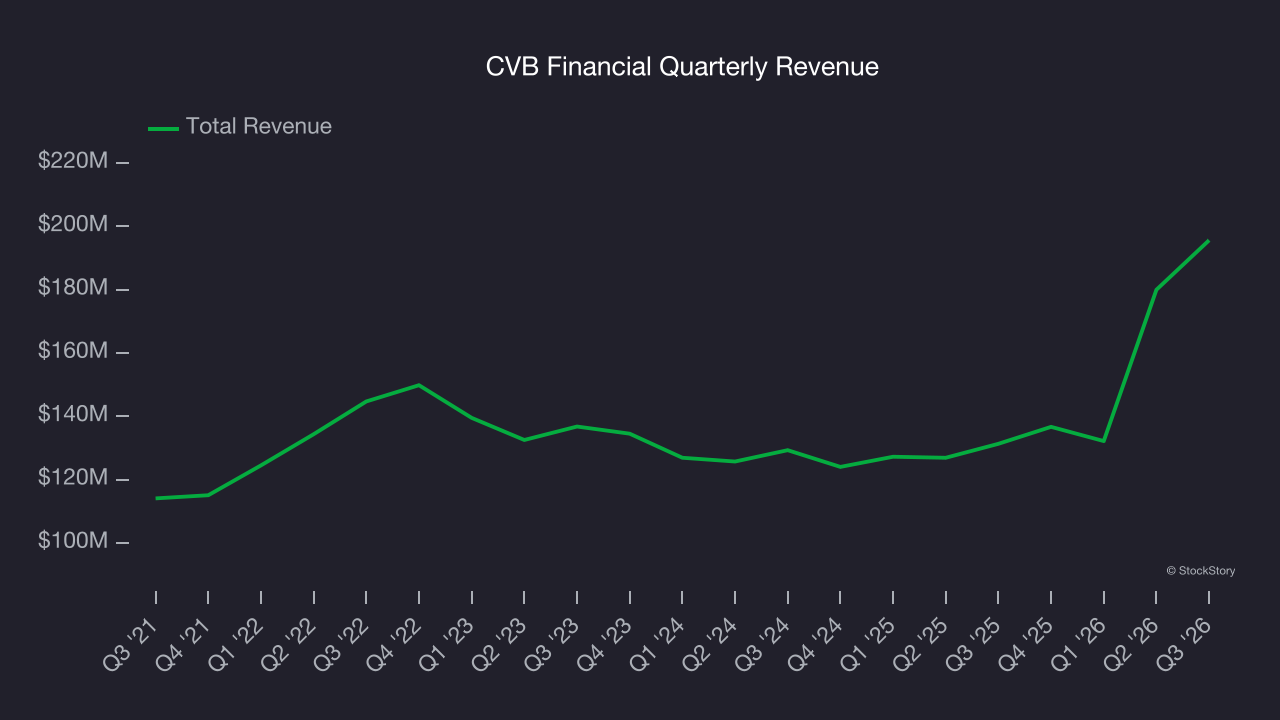
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. CVB Financial’s annualized revenue growth of 11.7% over the last two years is above its five-year trend, suggesting some bright spots. 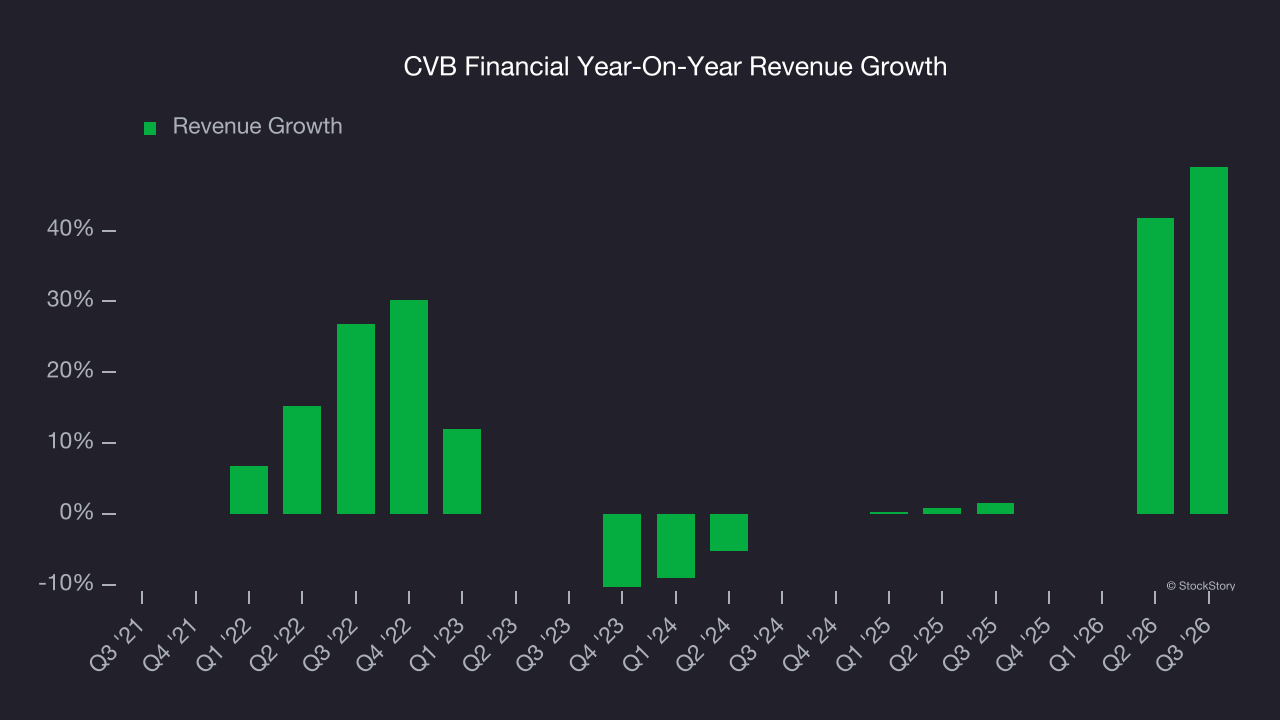 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, CVB Financial reported magnificent year-on-year revenue growth of 49%, and its $195.6 million of revenue beat Wall Street’s estimates by 1.2%.
Net interest income made up 76.1% of the company’s total revenue during the last five years, meaning lending operations are CVB Financial’s largest source of revenue.
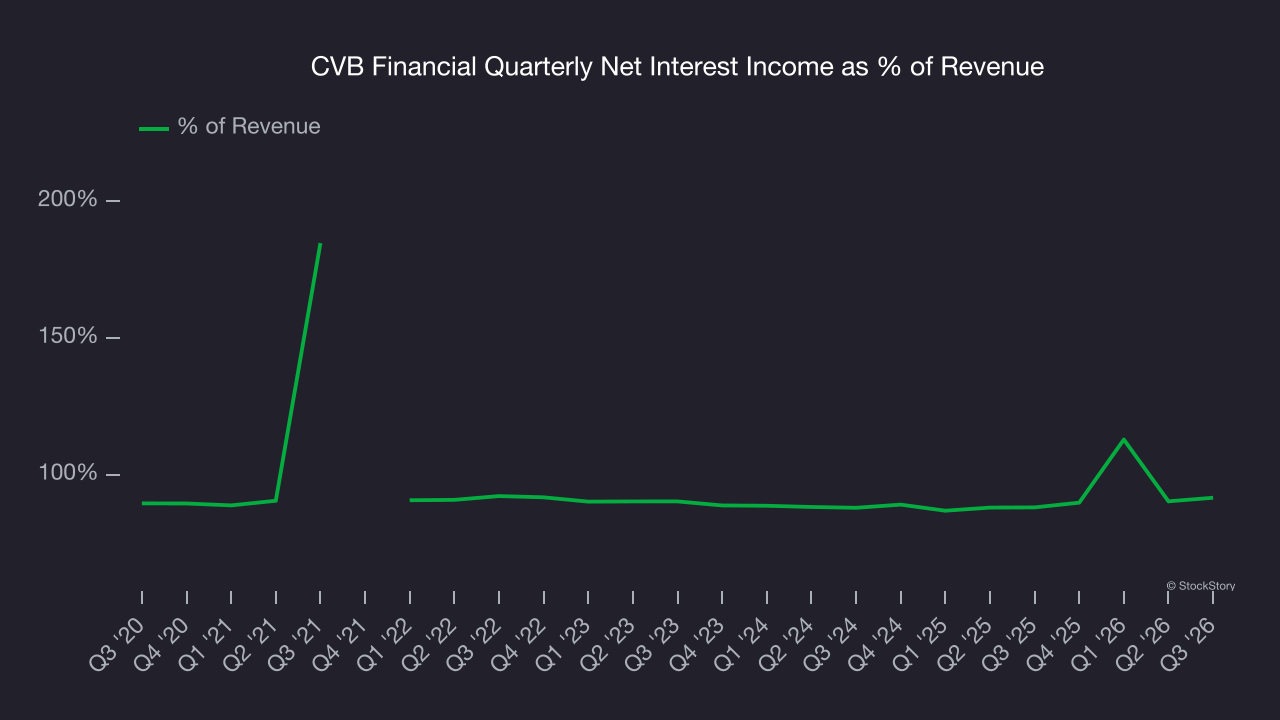 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
Our experience and research show the market cares primarily about a bank’s net interest income growth as non-interest income is considered a lower-quality and non-recurring revenue source.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Tangible book value per share (TBVPS)
Banks operate as balance sheet businesses, with profits generated through borrowing and lending activities. Valuations reflect this reality, emphasizing balance sheet strength and long-term book value compounding ability.
This is why we consider tangible book value per share (TBVPS) the most important metric to track for banks. TBVPS represents the real, liquid net worth per share of a bank, excluding intangible assets that have debatable value upon liquidation. Other (and more commonly known) per-share metrics like EPS can sometimes be murky due to M&A or accounting rules allowing for loan losses to be spread out.
CVB Financial’s TBVPS grew at a sluggish 1.5% annual clip over the last five years. However, TBVPS growth has accelerated recently, growing by 3.6% annually over the last two years from $10.17 to $10.92 per share.
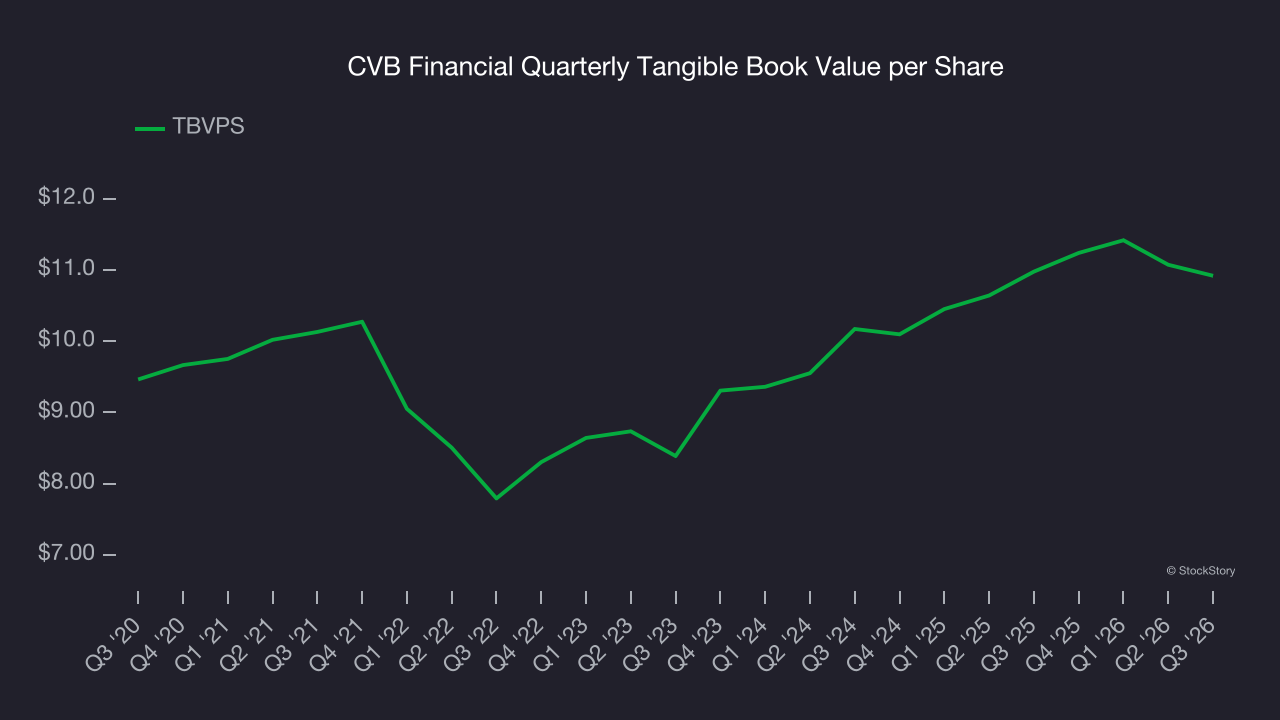
Over the next 12 months, Consensus estimates call for CVB Financial’s TBVPS to grow by 15.7% to $12.63, solid growth rate.
Key takeaways from CVB Financial’s Q3 results
It was good to see CVB Financial beat analysts’ EPS expectations this quarter. We were also happy its net interest income outperformed Wall Street’s estimates. On the other hand, its tangible book value per share missed. Overall, this print had some key positives. The stock remained flat at $22.21 immediately following the results.
So should you invest in CVB Financial right now? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).