
Restaurant company Darden (NYSE: DRI) met Wall Street’s revenue expectations in Q3 CY2026, with sales up 5.1% year on year to $3.2 billion. Its GAAP profit of $2.04 per share was 1.3% below analysts’ consensus estimates.
Is now the time to buy Darden? Find out by accessing our full research report, it’s free.
Darden (DRI) Q3 CY2026 Highlights:
- Revenue: $3.2 billion vs analyst estimates of $3.21 billion (5.1% year-on-year growth, in line)
- EPS (GAAP): $2.04 vs analyst expectations of $2.07 (1.3% miss)
- EPS (GAAP) guidance for the full year is $11.23 at the midpoint, roughly in line with what analysts were expecting
- Operating Margin: 10%, down from 11.1% in the same quarter last year
- Free Cash Flow Margin: 3.2%, down from 5.5% in the same quarter last year
- Locations: 2,218 at quarter end, up from 2,165 in the same quarter last year
- Same-Store Sales rose 3.1% year on year (4.7% in the same quarter last year)
- Market Capitalization: $24.26 billion
"The first quarter was a solid start to our fiscal year with each of our segments delivering positive same-restaurant sales," said Darden President & CEO Rick Cardenas. "The performance across our portfolio reinforces the importance of having distinctive brands, each with a clear strategy, supported by Darden's scale and other competitive advantages. Looking ahead, our focus remains the same: operate our restaurants at a high level, strengthen guest loyalty, invest in our people and brands, and deploy capital in ways that support long-term shareholder value."
Company Overview
Founded in 1968 as Red Lobster, Darden (NYSE: DRI) is a leading American restaurant company that owns and operates a portfolio of popular restaurant brands.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years.
With $13.37 billion in revenue over the past 12 months, Darden is one of the most widely recognized restaurant chains and benefits from customer loyalty, a luxury many don’t have. Its scale also gives it negotiating leverage with suppliers, enabling it to source its ingredients at a lower cost. However, its scale is a double-edged sword because there are only a finite of number places to build restaurants, making it harder to find incremental growth. For Darden to boost its sales, it likely needs to adjust its prices, launch new chains, or lean into foreign markets.
As you can see below, Darden grew its sales at a mediocre 6.5% compounded annual growth rate over the last seven years, but to its credit, it opened new restaurants and increased sales at existing, established dining locations.
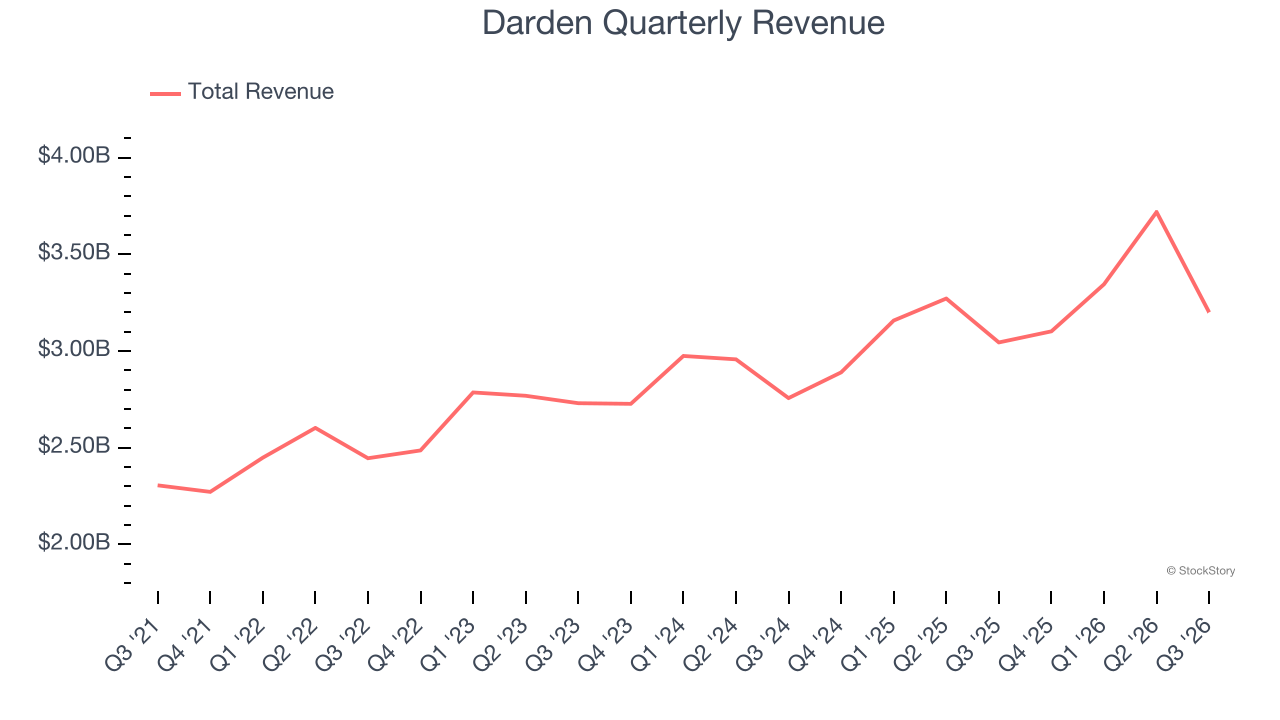
This quarter, Darden grew its revenue by 5.1% year on year, and its $3.2 billion of revenue was in line with Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 3.9% over the next 12 months, a slight deceleration versus the last seven years. This projection doesn’t excite us and suggests its menu offerings will face some demand challenges.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Restaurant Performance
Number of Restaurants
A restaurant chain’s total number of dining locations influences how much it can sell and how quickly revenue can grow.
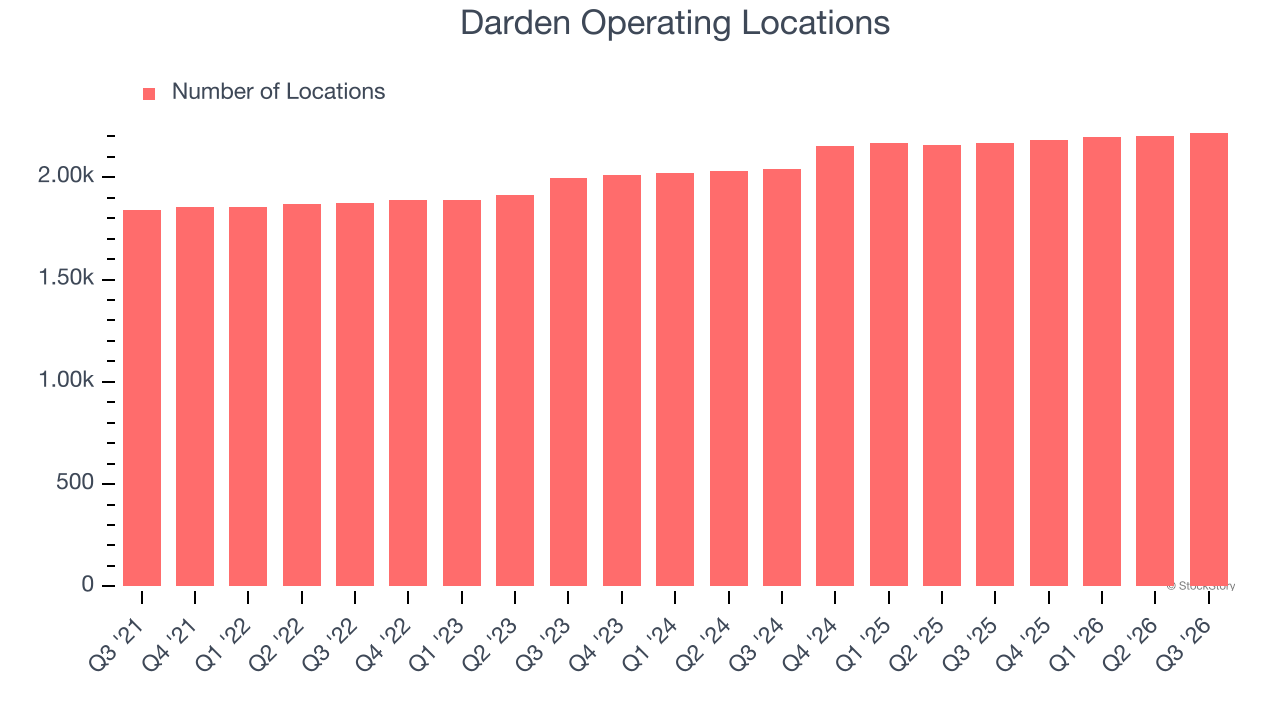
Darden operated 2,218 locations in the latest quarter. It has opened new restaurants at a rapid clip over the last two years, averaging 4.2% annual growth, much faster than the broader restaurant sector.
When a chain opens new restaurants, it usually means it’s investing for growth because there’s healthy demand for its meals and there are markets where its concepts have few or no locations.
Same-Store Sales
The change in a company’s restaurant base only tells one side of the story. The other is the performance of its existing locations, which informs management teams whether they should expand or downsize their physical footprints. Same-store sales gives us insight into this topic because it measures organic growth at restaurants open for at least a year.
Darden’s demand has been spectacular for a restaurant chain over the last two years. On average, the company has increased its same-store sales by an impressive 3.6% per year. This performance suggests its rollout of new restaurants is beneficial for shareholders. We like this backdrop because it gives Darden multiple ways to win: revenue growth can come from new restaurants or increased foot traffic and higher sales per customer at existing locations.
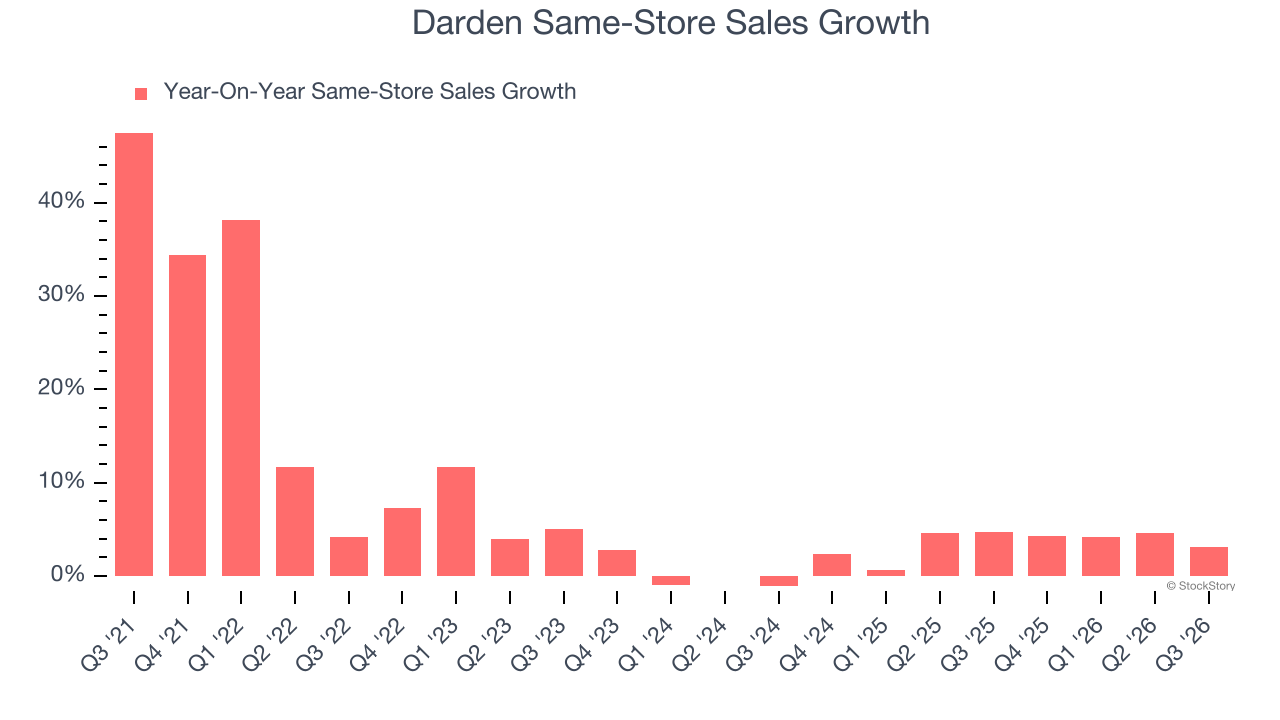
In the latest quarter, Darden’s same-store sales rose 3.1% year on year. This performance was more or less in line with its historical levels.
Key Takeaways from Darden’s Q3 Results
We struggled to find many positives in these results. Overall, this was a mixed quarter. The stock traded down 4.4% to $204.46 immediately following the results.
Is Darden an attractive investment opportunity at the current price? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).