
Offshore services provider Oceaneering International (NYSE: OII) reported Q3 2026 results beating Wall Street’s revenue expectations, with sales up 5.6% year on year to $784.6 million. Its non-GAAP profit of $0.50 per share was 15.1% below analysts’ consensus estimates.
Is now the time to buy Oceaneering? Find out by accessing our full research report, it’s free.
Oceaneering (OII) Q3 2026 highlights:
- Revenue: $784.6 million vs analyst estimates of $780.6 million (5.6% year-on-year growth, 0.5% beat)
- Adjusted EPS: $0.50 vs analyst expectations of $0.59 (15.1% miss)
- Adjusted EBITDA: $119.4 million vs analyst estimates of $117.4 million (15.2% margin, 1.7% beat)
- Operating Margin: 11.7%, in line with the same quarter last year
- Free Cash Flow Margin: 18.1%, up from 10.4% in the same quarter last year
- Market Capitalization: $4.39 billion
“Third-quarter bookings included meaningful awards across SSR, Manufactured Products, and Aerospace and Defense Technologies (ADTech). Together with our existing backlog and sales opportunities across our businesses, this provides a solid foundation as we enter 2027. Based on our current expectations, we are initiating full-year 2027 EBITDA guidance in the range of $430 million to $480 million.”
Company overview
Deploying a fleet of 250 tethered underwater robots around the globe, Oceaneering International (NYSE: OII) provides remotely operated underwater vehicles and subsea equipment for offshore energy exploration.
Revenue growth
Cyclical industries such as Energy can make mediocre companies look great for a time, but a long-term view reveals which businesses can actually withstand and adapt to changing conditions. Unfortunately, Oceaneering’s 9.8% annualized revenue growth over the last five years was mediocre. This fell short of our benchmark for the energy upstream and integrated energy sector and is a tough starting point for our analysis.
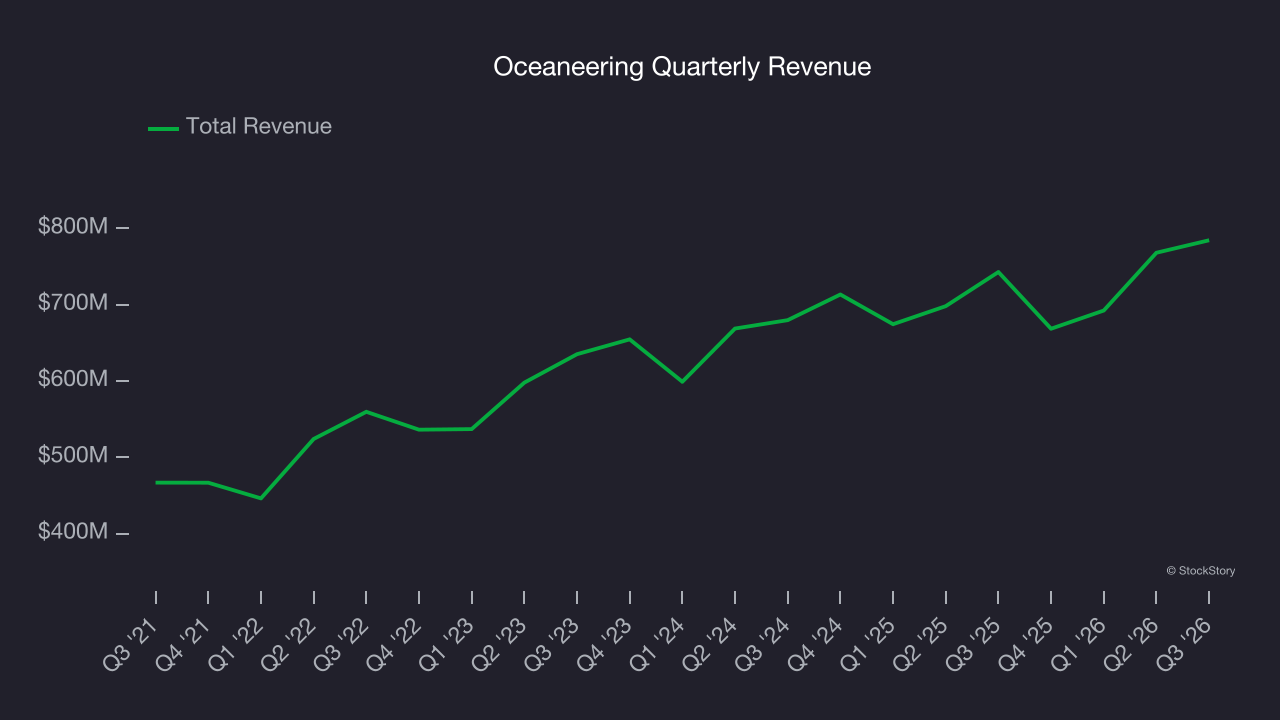
Within Energy, a singular timeframe, even if it’s quite long-term, only sheds light on how well a company rode the last commodity cycle. To better assess whether a company compounds through cycles, we validate our view with an even longer, ten-year view. Oceaneering’s annualized revenue growth of 1.5% over the last ten years is below its five-year trend, but we still think the results were respectable.
This quarter, Oceaneering reported year-on-year revenue growth of 5.6%, and its $784.6 million of revenue exceeded Wall Street’s estimates by 0.5%.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Adjusted EBITDA margin
Adjusted EBITDA margin strips out accounting distortions tied to depletion and historical drilling spend, providing a clearer view of the cash-generating power of the underlying asset base before financing and reinvestment decisions.
Oceaneering was profitable over the last five years but held back by its large cost base. Its average EBITDA margin of 12.9% was among the worst in the energy upstream and integrated energy sector.
On the plus side, Oceaneering’s EBITDA margin rose by 3.5 percentage points over the last year, as its sales growth gave it operating leverage.
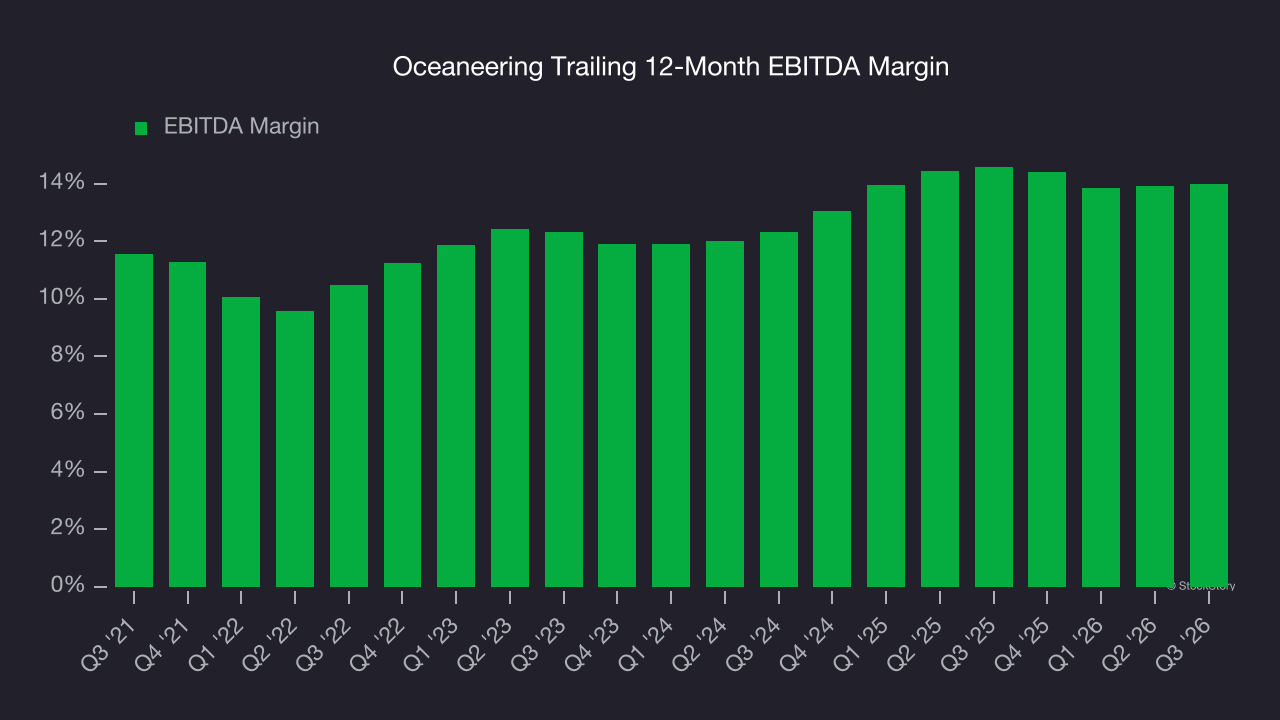
This quarter, Oceaneering generated an EBITDA margin profit margin of 15.2%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable. This adjusted EBITDA beat Wall Street’s estimates by 1.7%.
Cash is king
As mentioned above, adjusted EBITDA ignores capital structure and drilling expenditure decisions. These are two huge aspects of an Energy producer, so in order to understand a comprehensive picture of business quality, an investor needs to account for these. Said differently, adjusted EBITDA margins could be solid but free cash flow is abysmal because decline rates of the asset are extreme and the drilling is expensive. Free cash flow tells you about not only the economics of the production that has happened but how much it costs to stay in business as well (further drilling or extraction).
Oceaneering has shown mediocre cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 5.3%, below what we’d expect for an upstream and integrated energy business.
Absolute FCF margin levels matter but so does stability of free cash flow. All else equal, we’d prefer a 25.0% average free cash flow margin that is quite steady no matter how commodity prices behave rather than extremely high margins when times are good and negative ones when they’re tough.
Oceaneering’s ratio of quarterly free cash flow volatility to WTI crude price volatility over the past five years was 18.1 (lower is better), indicating that its cash generation is far more sensitive to commodity-price swings than most peers. This elevated volatility limits its access to capital in downturns and makes it unlikely to act as a consolidator when weaker competitors come under pressure.
You may be asking why we wait until the free cash flow line to perform this stability analysis versus commodity prices. Why not compare revenue or EBITDA to WTI in the case of Oceaneering? Because what ultimately matters is not how much revenue or profit you earn when prices are high but how much cash you can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging prowess to growth and maintenance capex to management behavior during good times and bad.
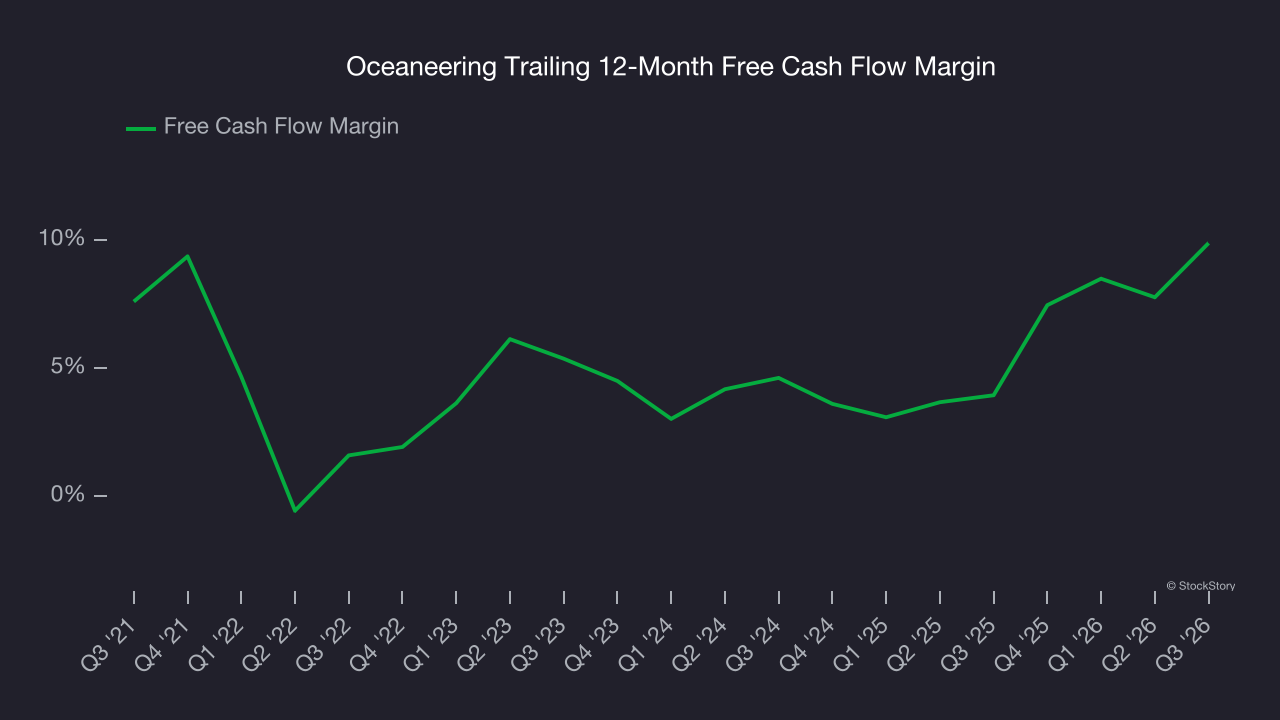
Oceaneering’s free cash flow clocked in at $141.9 million in Q3, equivalent to a 18.1% margin. This result was good as its margin was 7.7 percentage points higher than in the same quarter last year, building on its favorable historical trend.
Key takeaways from Oceaneering’s Q3 results
It was good to see Oceaneering narrowly top analysts’ revenue expectations this quarter. We were also happy its EBITDA outperformed Wall Street’s estimates. On the other hand, its EPS missed. Overall, this quarter could have been better. The stock traded down 4.5% to $42.06 immediately following the results.
Oceaneering may have had a tough quarter, but does that actually create an opportunity to invest right now? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).