Auto parts and accessories retailer AutoZone (NYSE: AZO) fell short of the market’s revenue expectations in Q3 CY2026, but sales rose 5.6% year on year to $6.59 billion. Its GAAP profit of $56.05 per share was 4% above analysts’ consensus estimates.
Is now the time to buy AutoZone? Find out by accessing our full research report, it’s free.
AutoZone (AZO) Q3 CY2026 Highlights:
- Revenue: $6.59 billion vs analyst estimates of $6.7 billion (5.6% year-on-year growth, 1.6% miss)
- EPS (GAAP): $56.05 vs analyst estimates of $53.89 (4% beat)
- Operating Margin: 20%, in line with the same quarter last year
- Free Cash Flow Margin: 10.4%, up from 8.2% in the same quarter last year
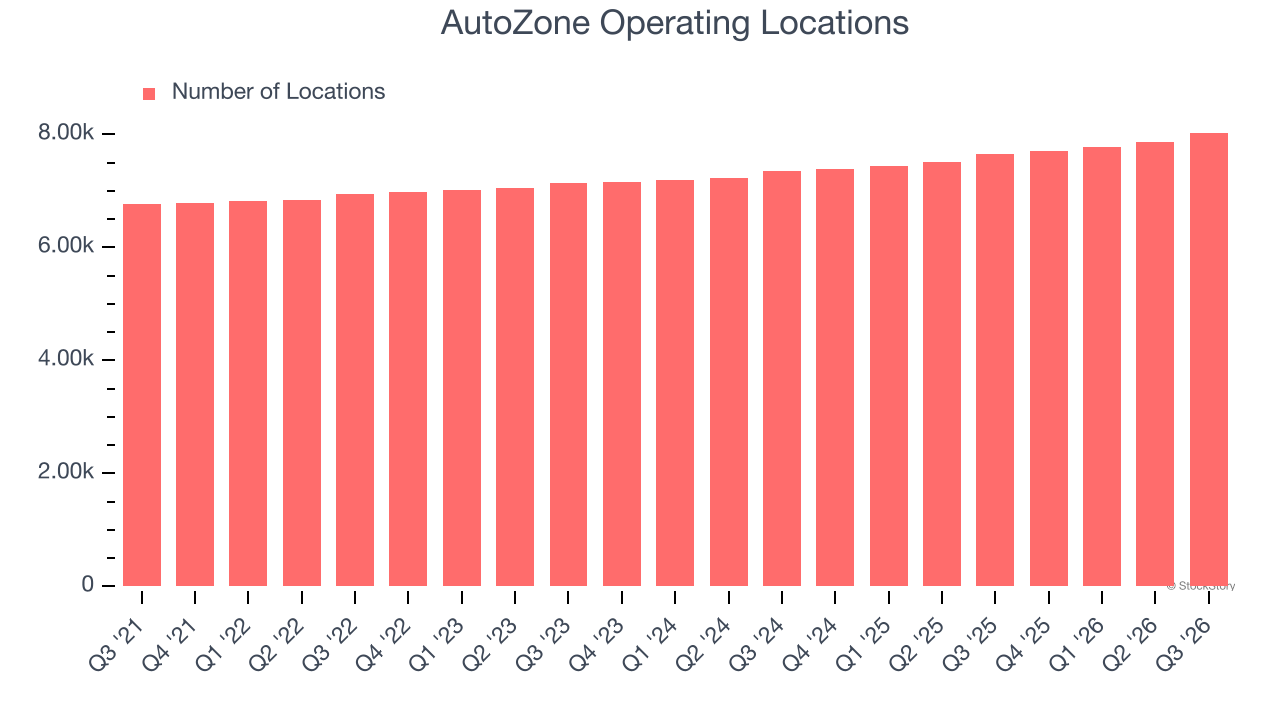
- Locations: 8,031 at quarter end, up from 7,657 in the same quarter last year
- Same-Store Sales rose 2.7% year on year (4.5% in the same quarter last year)
- Market Capitalization: $45.76 billion
“I want to thank our entire organization for delivering another quarter of sales and earnings growth. In spite of a difficult selling environment the first eight weeks of our quarter, we remained committed to executing on our strategies to grow both our domestic and international businesses. Over the last eight weeks of the quarter our sales results strengthened, and we feel we are well positioned for sales growth in fiscal 2027. We opened 175 new stores this past quarter, which included 16 new Mega Hub stores in the U.S. We continue to improve our inventory offering for both the do-it-yourself and professional customers. We continue to improve our speed of delivery and are intently focused on exceptional customer service. Based on the data we have, we continued to gain share and we expect sales in each of the three countries in which we operate to accelerate in the new fiscal year. As always, we will remain committed to a disciplined approach of driving shareholder value,” said Phil Daniele, President and Chief Executive Officer.
Company Overview
Aiming to be a one-stop shop for the DIY customer, AutoZone (NYSE: AZO) is an auto parts and accessories retailer that sells everything from car batteries to windshield wiper fluid to brake pads.
Revenue Growth
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years.
With $20.34 billion in revenue over the past 12 months, AutoZone is one of the larger companies in the consumer retail industry and benefits from a well-known brand that influences purchasing decisions. However, its scale is a double-edged sword because there is only so much real estate to build new stores, placing a ceiling on its growth. For AutoZone to boost its sales, it likely needs to adjust its prices or lean into foreign markets.
As you can see below, AutoZone grew its sales at a tepid 5.2% compounded annual growth rate over the last three years, but to its credit, it opened new stores and increased sales at existing, established locations.
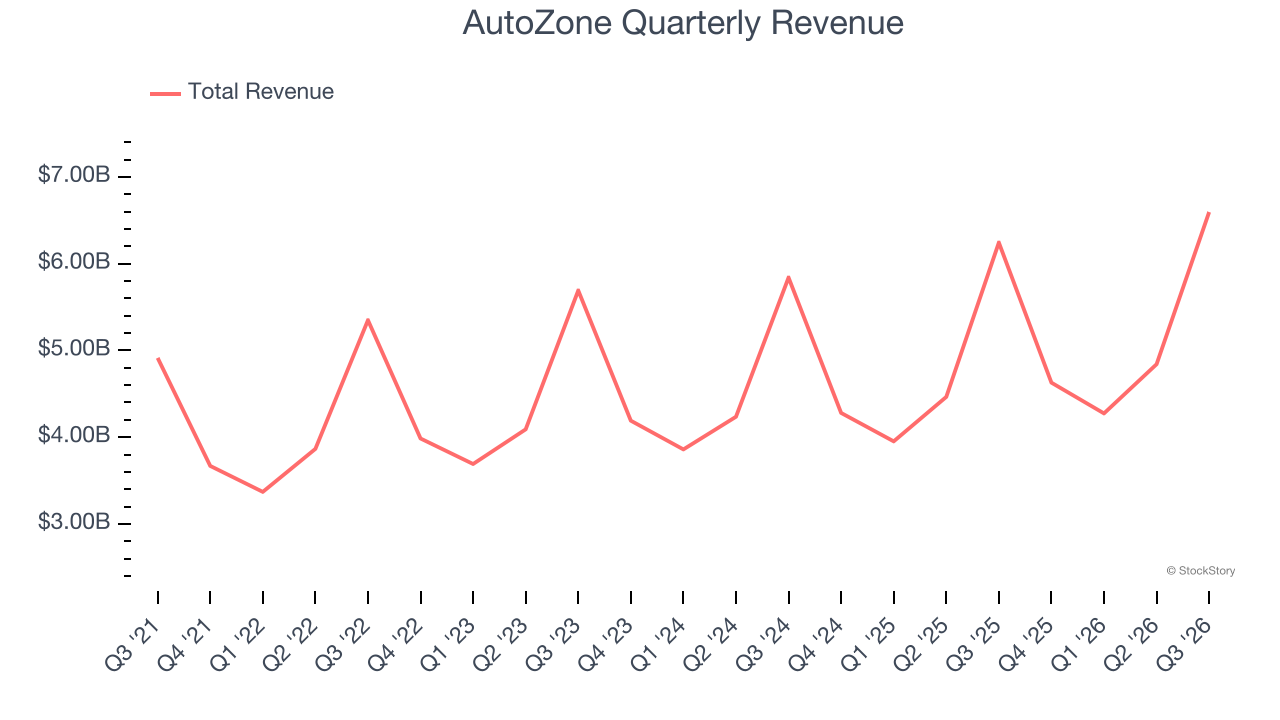
This quarter, AutoZone’s revenue grew by 5.6% year on year to $6.59 billion, missing Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 8.2% over the next 12 months, an acceleration versus the last three years. This projection is particularly healthy for a company of its scale and suggests its newer products will fuel better top-line performance.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Store Performance
Number of Stores
A retailer’s store count often determines how much revenue it can generate.
AutoZone operated 8,031 locations in the latest quarter. It has opened new stores at a rapid clip over the last two years, averaging 4.1% annual growth, much faster than the broader consumer retail sector.
When a retailer opens new stores, it usually means it’s investing for growth because demand is greater than supply, especially in areas where consumers may not have a store within reasonable driving distance.
Same-Store Sales
The change in a company’s store base only tells one side of the story. The other is the performance of its existing locations and e-commerce sales, which informs management teams whether they should expand or downsize their physical footprints. Same-store sales is an industry measure of whether revenue is growing at those existing stores and is driven by customer visits (often called traffic) and the average spending per customer (ticket).
AutoZone’s demand has been spectacular for a retailer over the last two years. On average, the company has increased its same-store sales by an impressive 3.4% per year. This performance suggests its rollout of new stores is beneficial for shareholders. We like this backdrop because it gives AutoZone multiple ways to win: revenue growth can come from new stores, e-commerce, or increased foot traffic and higher sales per customer at existing locations.
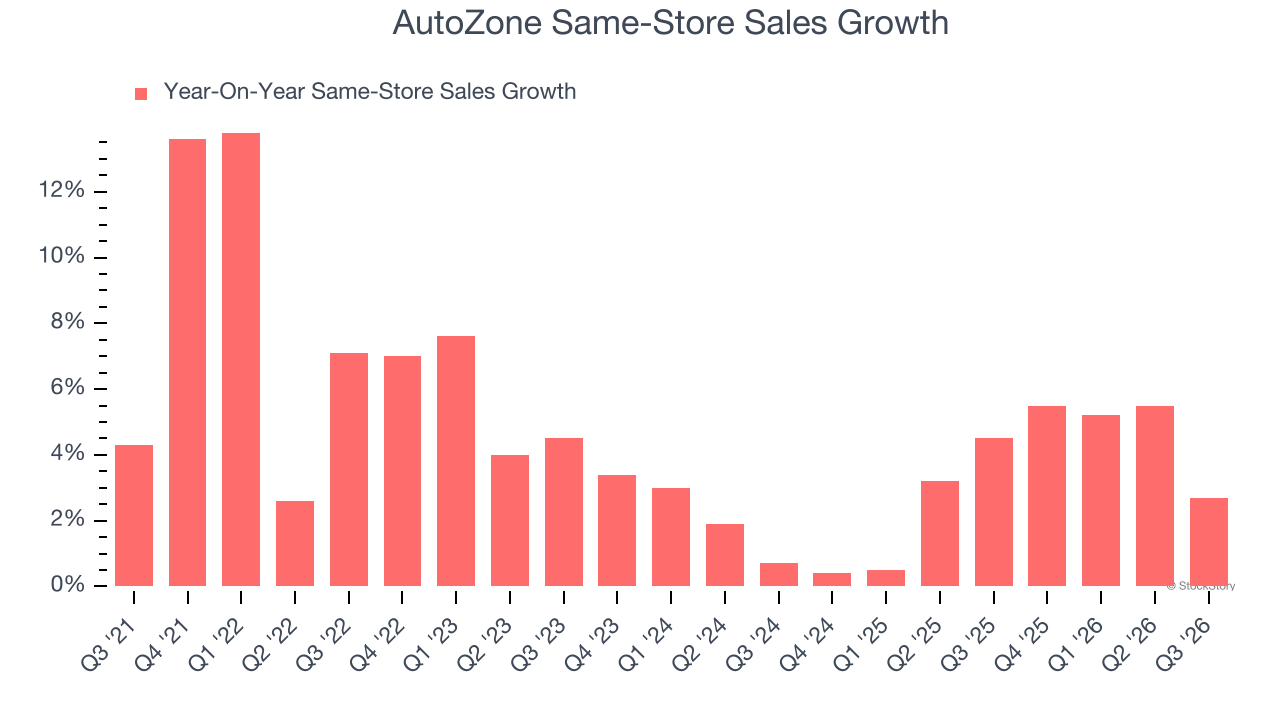
In the latest quarter, AutoZone’s same-store sales rose 2.7% year on year. This performance was more or less in line with its historical levels.
Key Takeaways from AutoZone’s Q3 Results
We enjoyed seeing AutoZone beat analysts’ gross margin expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. On the other hand, its revenue missed. Overall, this was a weaker quarter. The stock traded up 1.1% to $2,833 immediately after reporting.
Big picture, is AutoZone a buy here and now? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).