
Regal Rexnord has gotten torched over the last six months - since April 2026, its stock price has dropped 29.3% to $150.78 per share. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Regal Rexnord, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why is Regal Rexnord not exciting?
Despite the more favorable entry price, we’re passing on Regal Rexnord for now. Here are three reasons why there are better opportunities than RRX, plus one stock we’d rather own.
1. Revenue tumbling downwards
We at StockStory place the most emphasis on long-term growth, but within industrials, a stretched historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. Regal Rexnord’s recent performance marks a sharp pivot from its five-year trend as its revenue has shown annualized declines of 2.4% over the last two years. 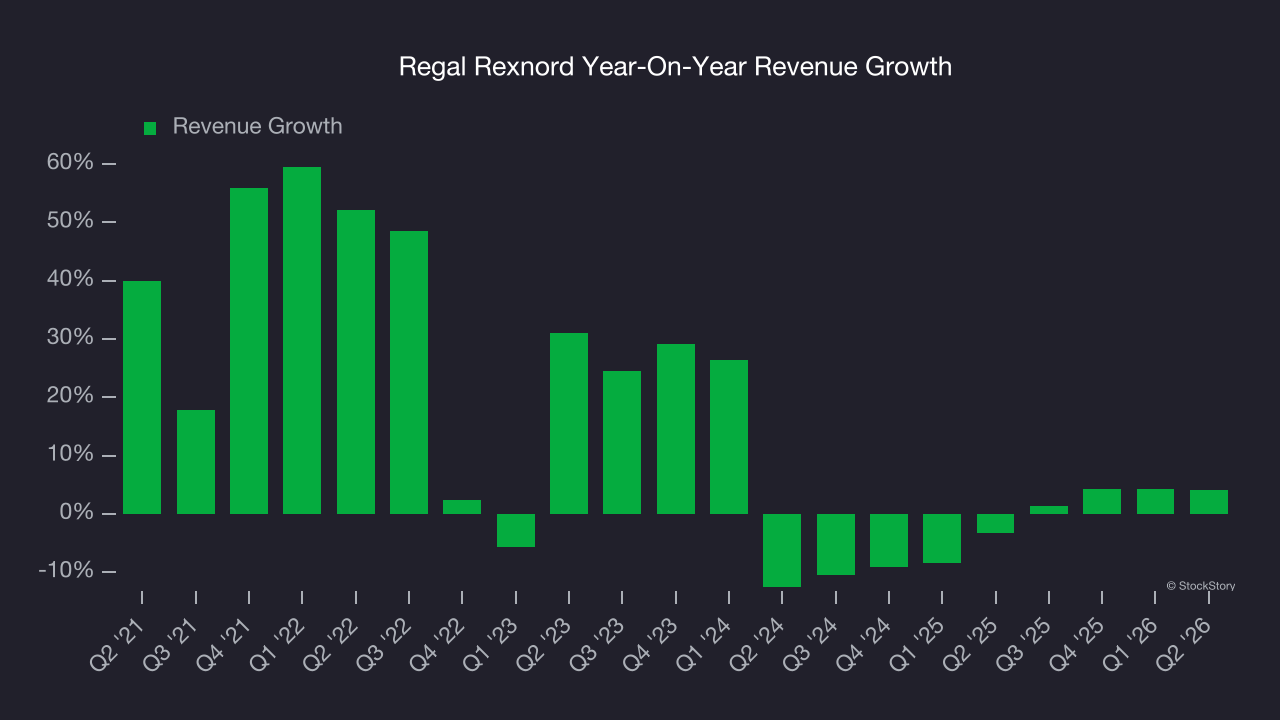
2. Core business falling behind as demand plateaus
We can better understand engineered components and systems companies by analyzing their organic revenue. This metric gives visibility into Regal Rexnord’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, Regal Rexnord failed to grow its organic revenue. This performance was underwhelming and implies it may need to improve its products, pricing, or go-to-market strategy. It also suggests Regal Rexnord might have to lean into acquisitions to accelerate growth, which isn’t ideal because M&A can be expensive and risky (integrations often disrupt focus). 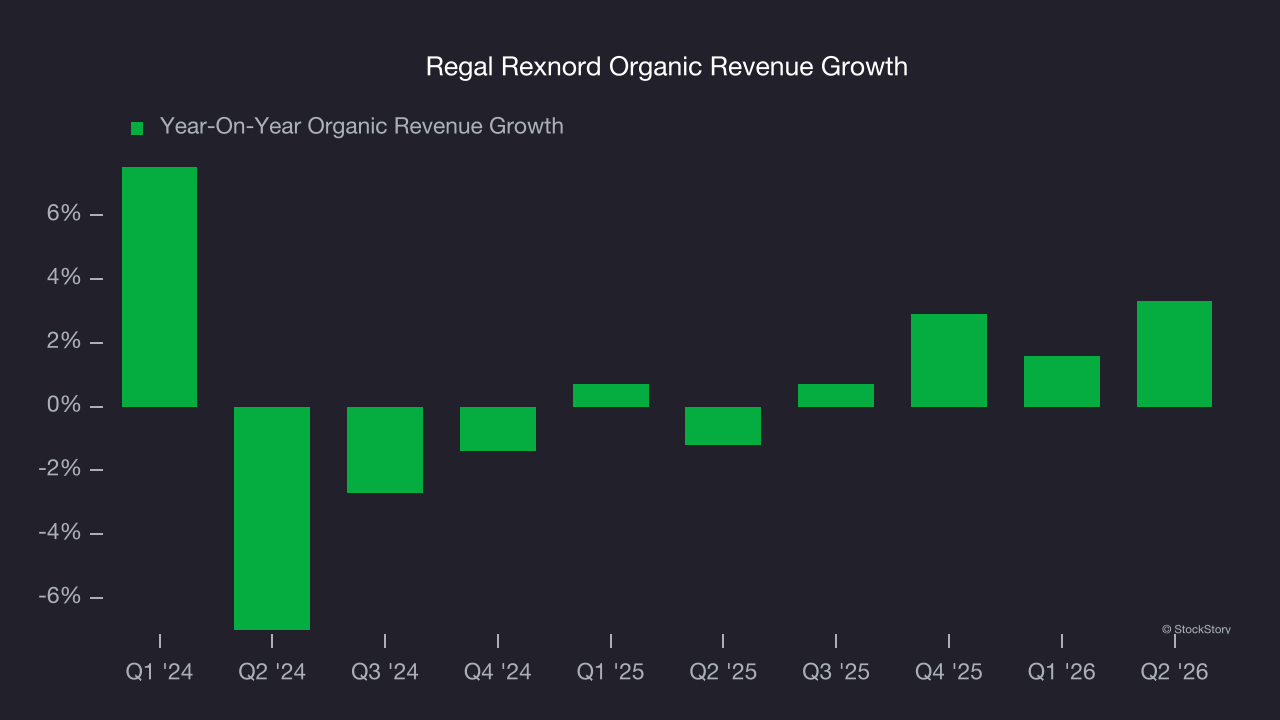
3. Previous growth initiatives haven’t impressed
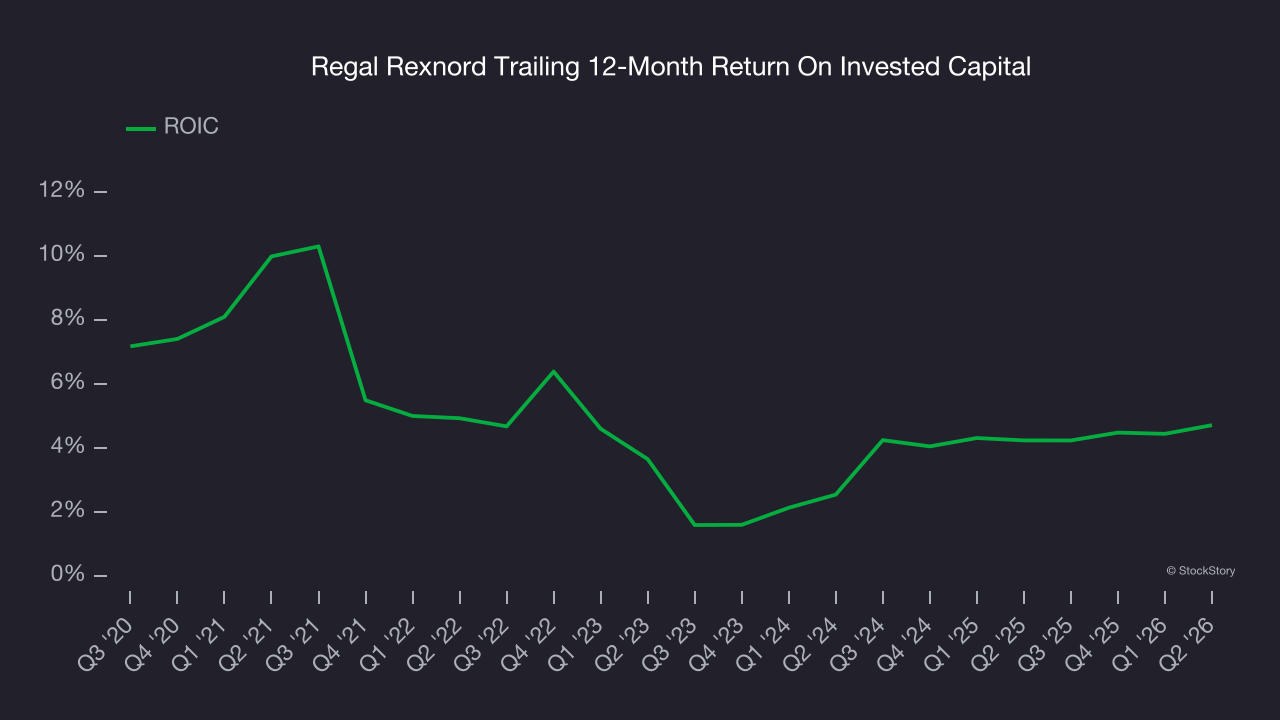
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
Regal Rexnord historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 4%, lower than the typical cost of capital (how much it costs to raise money) for industrials companies.
Final judgment
Regal Rexnord’s business quality ultimately falls short of our standards. After the recent drawdown, the stock trades at 12.7× forward P/E (or $150.78 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re fairly confident there are better stocks to buy right now. Let us point you toward the most entrenched endpoint security platform on the market.
Stocks we would buy instead of Regal Rexnord
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.