
Appian has been on fire lately. In the past six months alone, the company’s stock price has rocketed 129%, reaching $49.88 per share. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy Appian, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why is Appian not exciting?
We’re glad investors have benefited from the price increase, but we’re sitting this one out for now. Here are three reasons we avoid APPN, plus one stock we’d rather own.
1. Projected revenue growth is slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Appian’s revenue to rise by 12.2%, according to S&P, a deceleration versus its 19.2% annualized growth for the past five years. This projection doesn’t excite us and indicates its products and services will face some demand challenges.
2. Long payback periods delay returns
The customer acquisition cost (CAC) payback period represents the months required to recover the cost of acquiring a new customer. Essentially, it’s the break-even point for sales and marketing investments. A shorter CAC payback period is ideal, as it implies better returns on investment and business scalability.
Appian’s recent customer acquisition efforts haven’t yielded returns as its CAC payback period was negative this quarter, meaning its incremental sales and marketing investments outpaced its revenue. The company’s inefficiency indicates it operates in a competitive market and must continue investing to grow.
3. Operating margin rising, profits up
Many software businesses adjust their profits for stock-based compensation (SBC), but we prioritize GAAP operating margin because SBC is a real expense used to attract and retain engineering and sales talent. This metric shows how much revenue remains after accounting for all core expenses — everything from the cost of goods sold to sales and R&D.
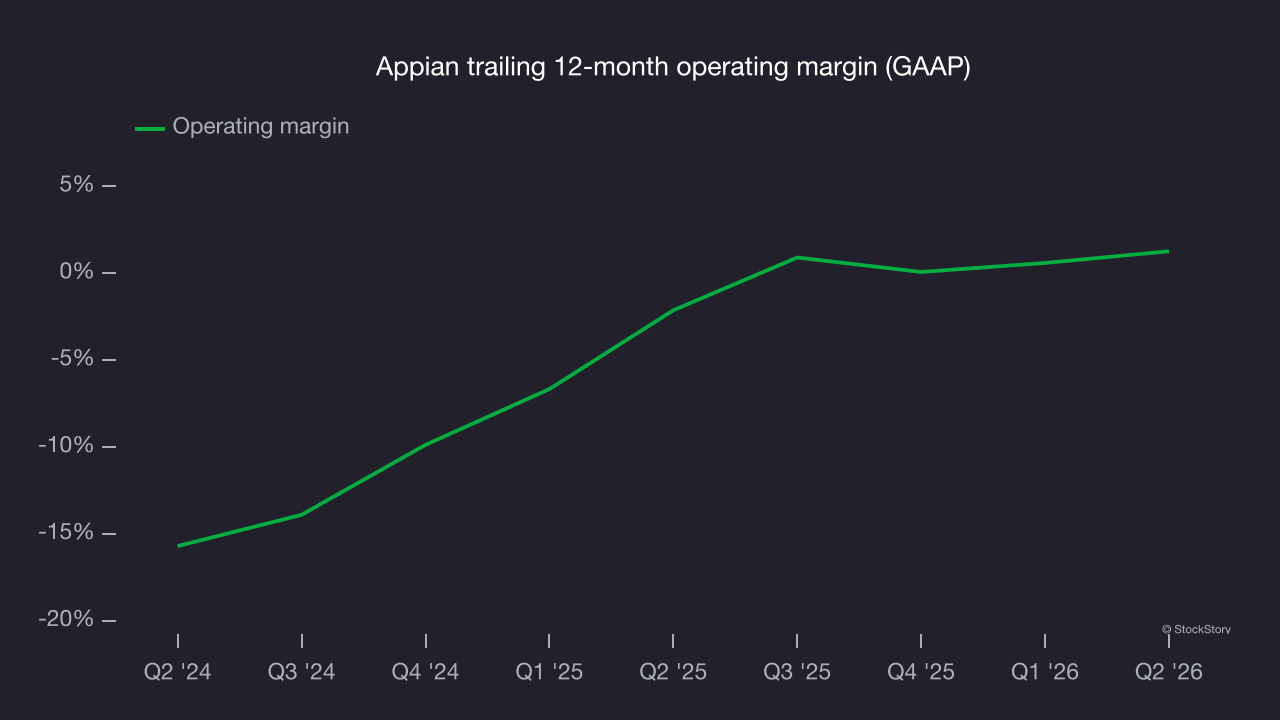
Analyzing the trend in its profitability, Appian’s operating margin rose by 3.4 percentage points over the last two years, as its sales growth gave it operating leverage. Its operating margin for the trailing 12 months was 1.3%.
Final judgment
Appian isn’t a terrible business, but it isn’t one of our picks. Following the recent surge, the stock trades at 4.2× forward price-to-sales (or $49.88 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re fairly confident there are better stocks to buy right now. We’d suggest looking at an all-weather company that owns household favorite Taco Bell.
High-quality stocks for all market conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.