What a fantastic six months it’s been for Wayfair. Shares of the company have skyrocketed 52.3%, hitting $106.25. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Wayfair, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Wayfair Not Exciting?
We’re glad investors have benefited from the price increase, but we don’t have much confidence in Wayfair. Here are three reasons we avoid W, plus one stock we’d rather own.
1. Declining Active Customers Reflect Product Weakness
As an online retailer, Wayfair generates revenue growth by expanding its number of users and the average order size in dollars.
Wayfair struggled with new customer acquisition over the last two years as its active customers have declined by 2.2% annually to 21.7 million in the latest quarter. This performance isn’t ideal because internet usage is secular, meaning there are typically unaddressed market opportunities. If Wayfair wants to accelerate growth, it likely needs to enhance the appeal of its current offerings or innovate with new products. 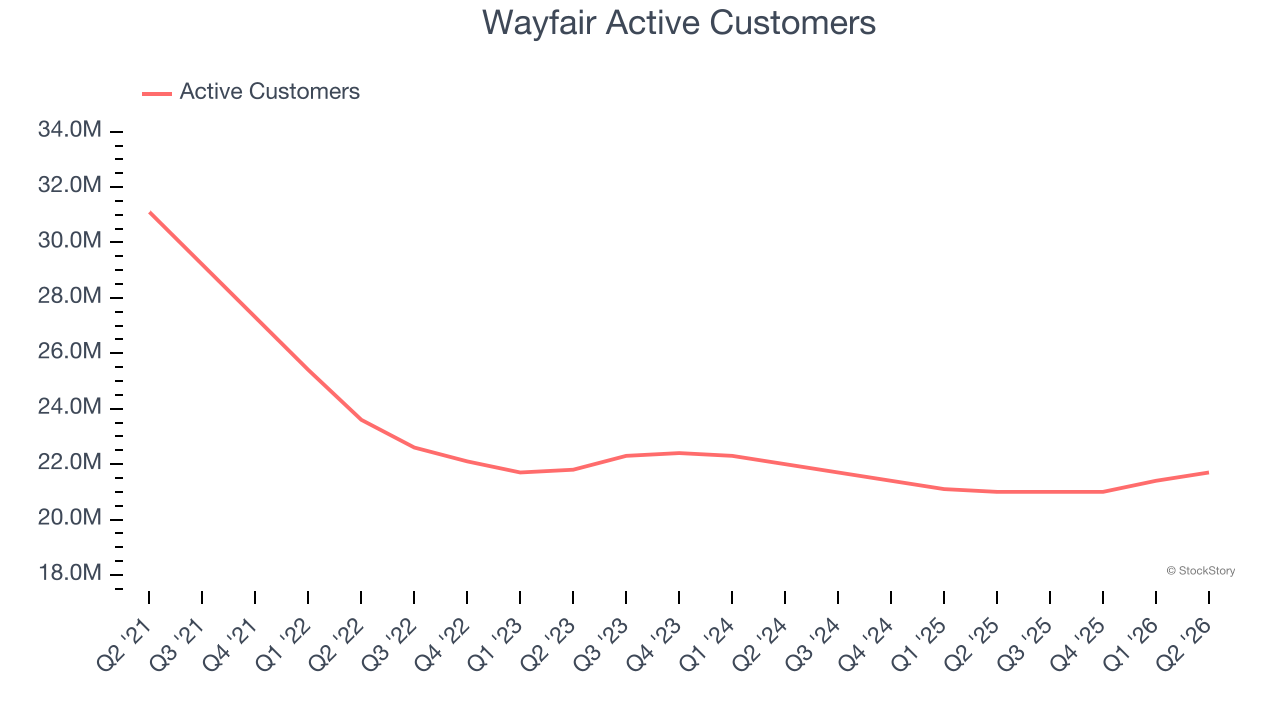
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Wayfair’s revenue to rise by 7.3%. While this projection indicates its newer products and services will fuel better top-line performance, it is still below the sector average.
3. Low Gross Margin Reveals Weak Structural Profitability
For online retail (separate from online marketplaces) businesses like Wayfair, gross profit tells us how much money the company gets to keep after covering the base cost of its products and services, which typically include the cost of acquiring the products sold, shipping and fulfillment, customer service, and digital infrastructure.
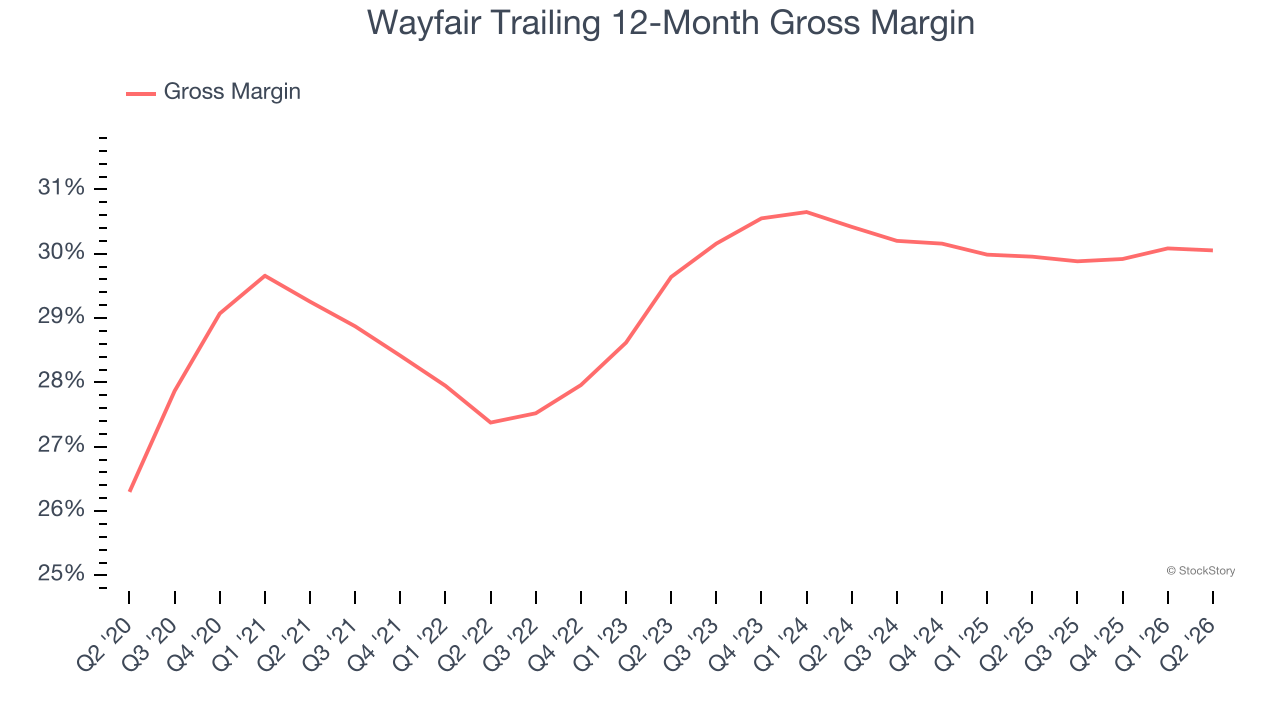
Wayfair’s unit economics are far below other consumer internet companies because it must carry inventories as an online retailer. This means it has relatively higher capital intensity than a pure software business like Meta or Airbnb and signals it operates in a competitive market. As you can see below, it averaged a 30% gross margin over the last two years. Said differently, Wayfair had to pay a chunky $69.99 to its service providers for every $100 in revenue.
Final Judgment
Wayfair’s business quality ultimately falls short of our standards. Following the recent rally, the stock trades at 17.4× forward EV/EBITDA (or $106.25 per share). This valuation tells us a lot of optimism is priced in - we think there are better opportunities elsewhere. We’d suggest looking at an all-weather company that owns household favorite Taco Bell.
Stocks We Would Buy Instead of Wayfair
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.