
The past six months have been a windfall for The Cheesecake Factory’s shareholders. The company’s stock price has jumped 81.8%, hitting $106.84 per share. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now the time to buy The Cheesecake Factory, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is The Cheesecake Factory Not Exciting?
We’re glad investors have benefited from the price increase, but we’re passing on The Cheesecake Factory for now. Here are three reasons why there are better opportunities than CAKE, plus one stock we’d rather own.
1. Same-Store Sales Falling Behind Peers
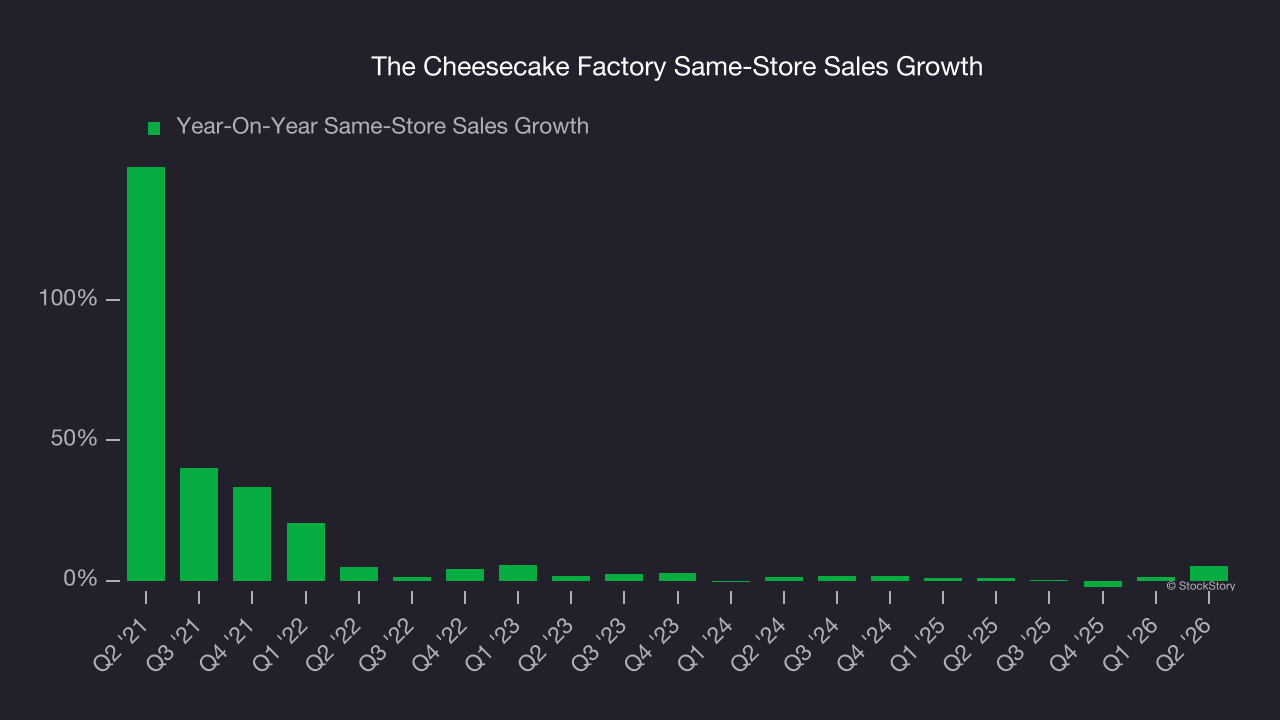
Same-store sales show the change in sales at restaurants open for at least a year. This is a key performance indicator because it measures organic growth.
The Cheesecake Factory’s demand within its existing dining locations has been relatively stable over the last two years but was below most restaurant chains. On average, the company’s same-store sales have grown by 1.2% per year.
2. Weak Operating Margin Could Cause Trouble
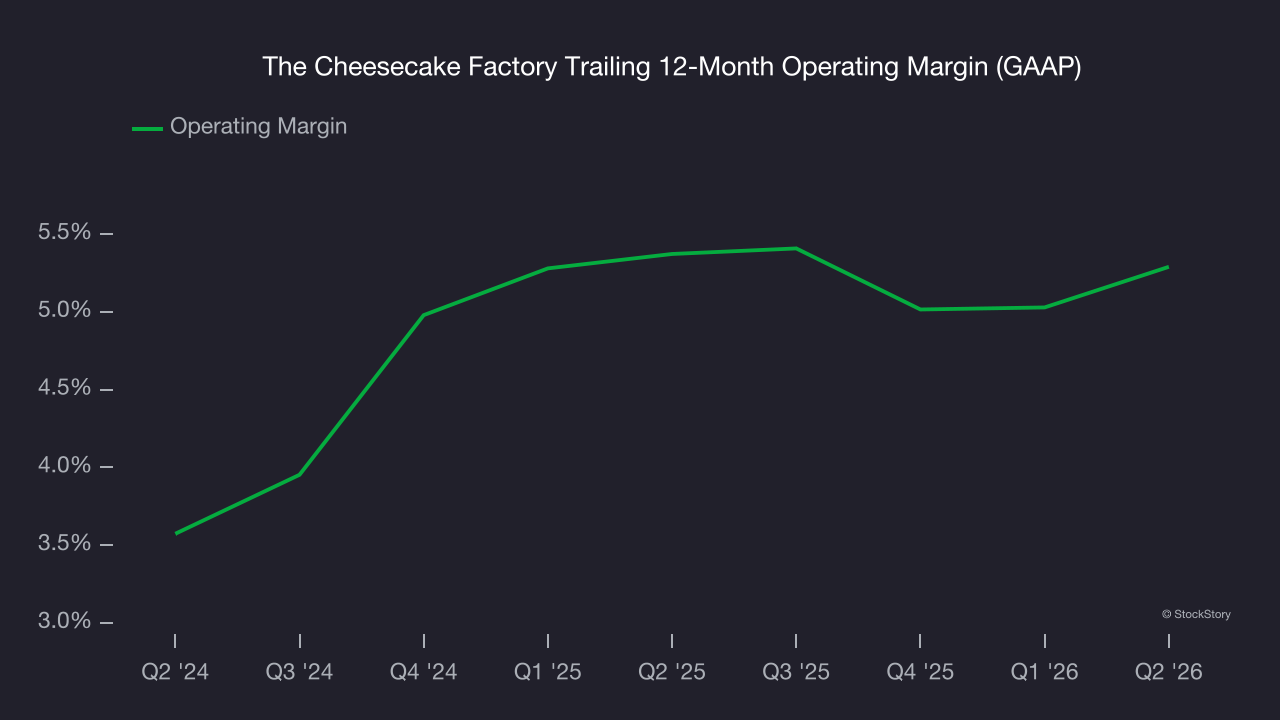
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
The Cheesecake Factory’s operating margin has more or less stayed the same over the last 12 months , averaging 5.3% over the last two years. This profitability was paltry for a restaurant business and caused by its suboptimal cost structure.
3. High Debt Levels Increase Risk
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
The Cheesecake Factory’s $2.08 billion of debt exceeds the $195.2 million of cash on its balance sheet. Furthermore, its 5× net-debt-to-EBITDA ratio (based on its EBITDA of $346.2 million over the last 12 months) shows the company is overleveraged.
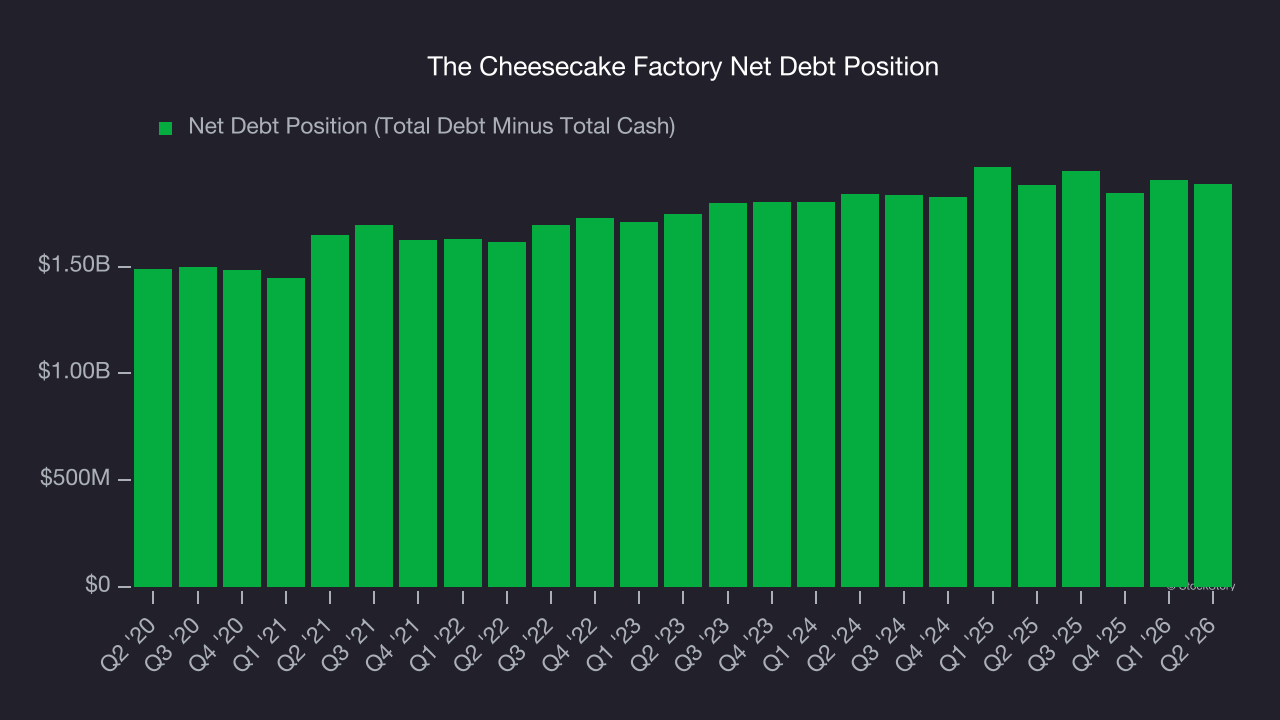
At this level of debt, incremental borrowing becomes increasingly expensive and credit agencies could downgrade the company’s rating if profitability falls. The Cheesecake Factory could also be backed into a corner if the market turns unexpectedly – a situation we seek to avoid as investors in high-quality companies.
We hope The Cheesecake Factory can improve its balance sheet and remain cautious until it increases its profitability or pays down its debt.
Final Judgment
The Cheesecake Factory isn’t a terrible business, but it doesn’t pass our quality test. Following the recent surge, the stock trades at 22.8× forward P/E (or $106.84 per share). Investors with a higher risk tolerance might like the company, but we don’t really see a big opportunity at the moment. We’re fairly confident there are better investments elsewhere. We’d suggest looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
Stocks We Like More Than The Cheesecake Factory
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.