Online travel agency Expedia (NASDAQ: EXPE) beat Wall Street’s revenue expectations in Q3 2026, with revenue up 11.9% year on year to $4.94 billion. The company expects next quarter’s revenue to be around $3.72 billion, close to analysts’ consensus estimates. Its non-GAAP profit of $9.39 per share was 5.6% above analysts’ consensus estimates.
For more on Expedia, read our full research report for free.
Expedia (EXPE) Q3 2026 highlights:
- Revenue $4.94 billion vs S&P analysts’ consensus estimates of $4.73 billion (11.9% year-on-year growth, 4.4% beat)
- Adjusted EPS $9.39 vs S&P analysts’ consensus estimates of $8.89 (5.6% beat)
- Adjusted EBITDA $1.69 billion vs analysts’ consensus estimates of $1.55 billion (34.2% margin, 9% beat)
- Revenue guidance $3.72 billion at the midpoint for Q4 2026, roughly in line with what analysts were expecting
- EBITDA guidance $855 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $917.3 million
- Operating margin 26.9%, up from 23.5% in the same quarter last year
- Free cash flow -$1.40 billion, down from $1.28 billion in the previous quarter
- Room nights booked 115.7 million, up 7.5 million year on year
- Market capitalization $34.3 billion
“We exceeded the high end of our guidance in the quarter, reflecting resilient travel demand and strong execution,” said Ariane Gorin, CEO of Expedia Group. “We continue to deliver traveler value through more personalized and rewarding product experiences, improve supply across our marketplace, and advance our strategy to build the one-stop travel platform for B2B partners. AI is opening further opportunities across our business, enhancing internal productivity and creating new sources of growth. Our progress and the results we delivered demonstrate the differentiation of our platform and reinforce our confidence in our ability to deliver value for all our stakeholders.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Expedia’s revenue grew at a mediocre 8.9% annualized rate over the last three years, falling short of our standard for the consumer internet sector.
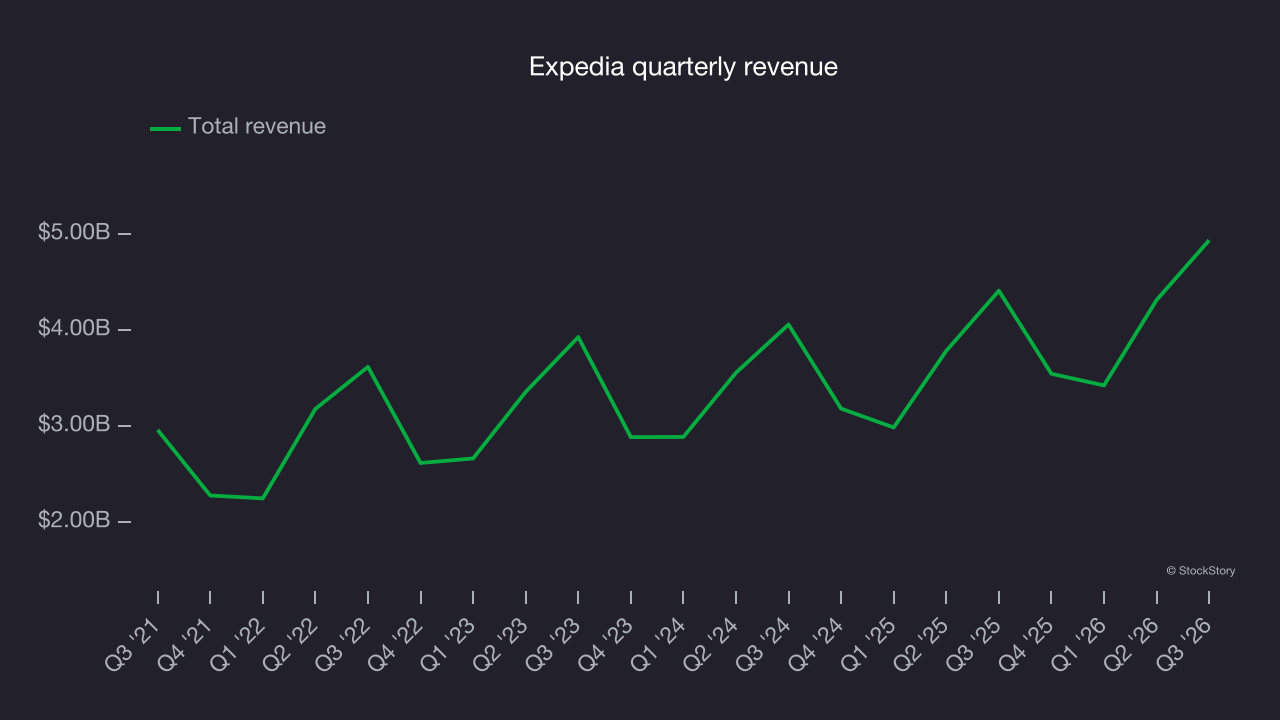
This quarter, Expedia reported year-on-year revenue growth of 11.9%, and its $4.94 billion of revenue exceeded Wall Street’s consensus estimates by 4.4%. Company management is currently guiding for a 4.9% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 4.9% over the next 12 months, according to S&P, a deceleration versus the last three years. This projection is underwhelming and suggests its products and services will see some demand headwinds.
Room nights booked
Booking growth
As an online travel company, Expedia generates revenue growth by increasing both the number of stays (or experiences) booked and the commission charged on those bookings.
Over the last two years, Expedia’s room nights booked, a key performance metric for the company, increased by 7.9% annually to 115.7 million in the latest quarter. This growth rate is decent for a consumer internet business and indicates its offerings appeal to users. 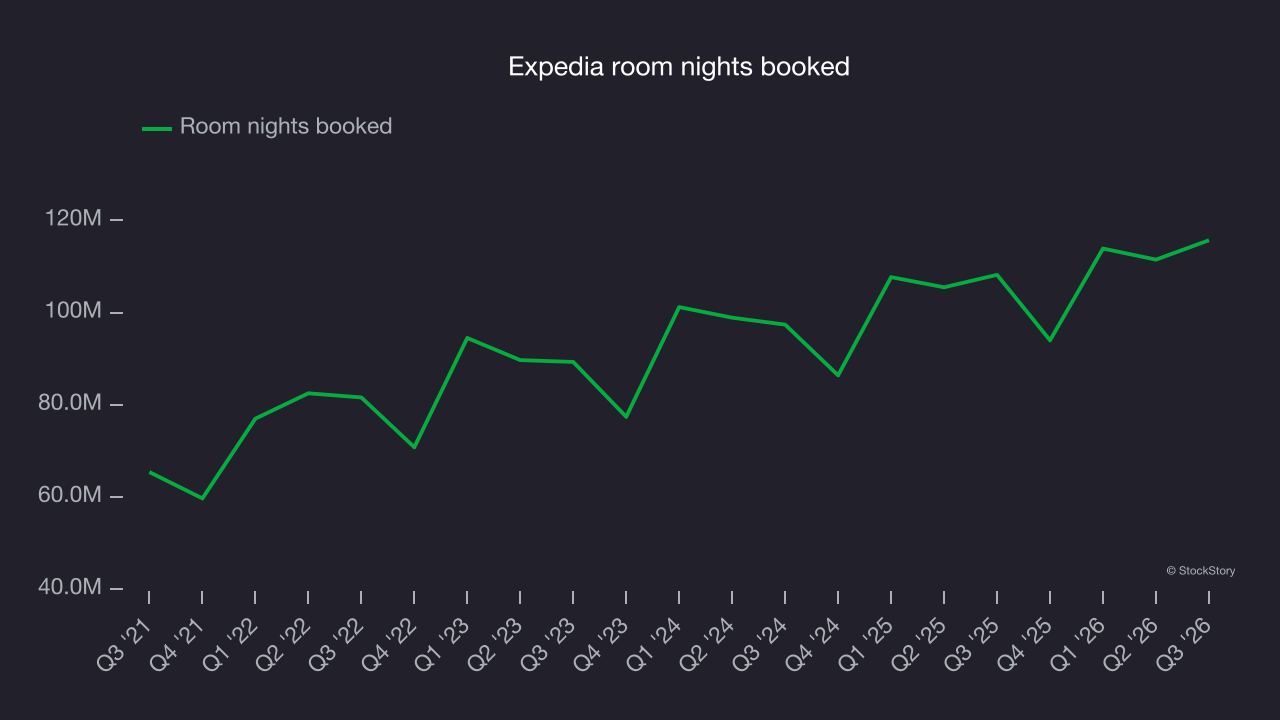
In Q3, Expedia added 7.5 million room nights booked, leading to 6.9% year-on-year growth. The quarterly growth rate is similar to its two-year result, suggesting its new initiatives aren’t accelerating booking growth yet.
Revenue per booking
Average revenue per booking, or ARPB, is a critical metric to track because it not only measures how much users book on its platform but also the commission that Expedia can charge.
Expedia’s ARPB growth has been subpar over the last two years, averaging 2.1%, but the increase in room nights booked is more relevant for assessing long-term business potential. If Expedia tries boosting ARPB through more aggressive monetization, it’s unclear whether bookings can continue growing at the current pace. 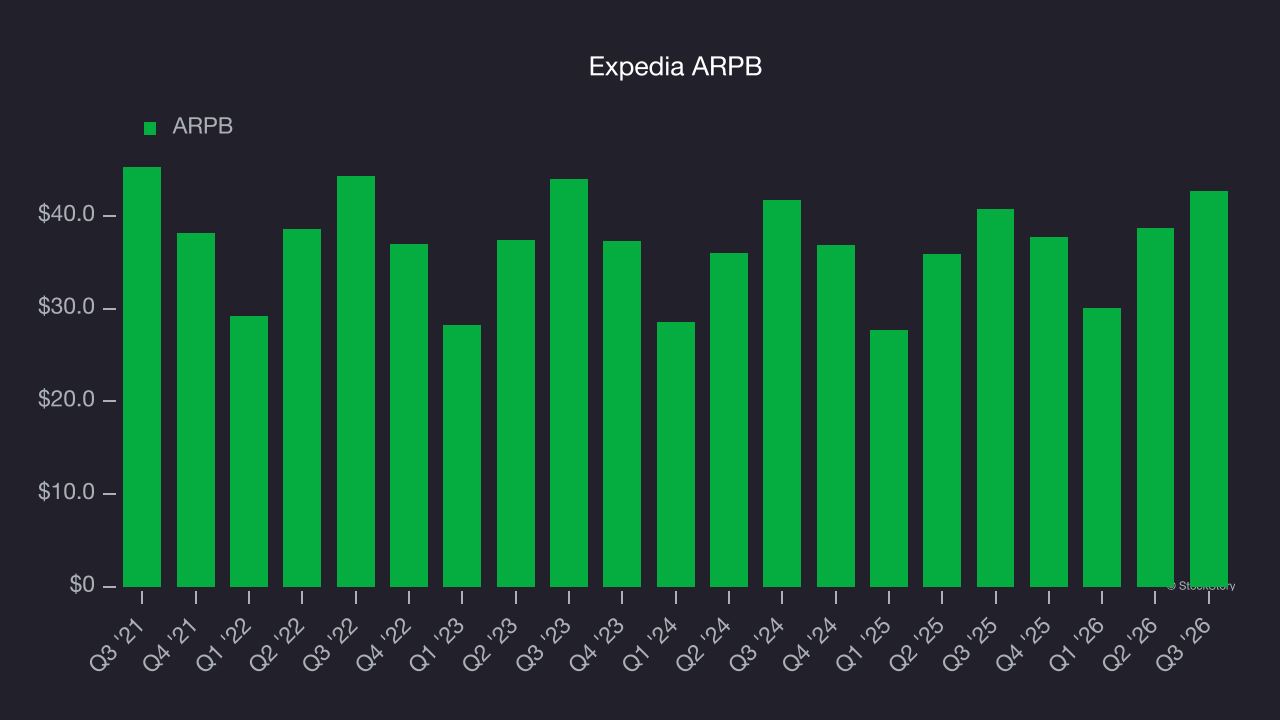
This quarter, Expedia’s ARPB reached $42.68. It grew by 4.7% year on year, slower than its booking growth.
Key takeaways from Expedia’s Q3 results
Expedia’s sizable EBITDA beat and better-than-expected revenue gave Q3 some clear positives, but the outlook was less encouraging: EBITDA guidance for next quarter missed consensus estimates, and revenue guidance was in line with Wall Street’s consensus. That made for a mixed quarter overall. Investors were likely hoping for more, and shares tumbled 8.6% to $293.44 immediately after reporting.
Expedia’s latest quarterly results matter when deciding whether to invest, but longer-term business quality and valuation matter more. Read the full research report here (it’s free).