Customer platform provider HubSpot (NYSE: HUBS) announced better-than-expected revenue in Q3 2026, with revenue up 17.1% year on year to $947.6 million. On the other hand, next quarter’s revenue guidance of $946 million was less impressive, coming in 1.9% below analysts’ consensus estimates. Its non-GAAP profit of $3.81 per share was 16.4% above analysts’ consensus estimates.
For more on HubSpot, read our free full research report.
HubSpot (HUBS) Q3 2026 highlights:
- Revenue $947.6 million vs S&P analysts’ consensus estimates of $925.1 million (17.1% year-on-year growth, 2.4% beat)
- Adjusted EPS $3.81 vs S&P analysts’ consensus estimates of $3.27 (16.4% beat)
- Adjusted operating income $214.2 million vs analysts’ consensus estimates of $188.2 million (22.6% margin, 13.8% beat)
- Revenue guidance $946 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $964.8 million
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $13.60 at the midpoint, a 2.5% increase
- Operating margin 7.6%, up from 1.4% in the same quarter last year
- Free cash flow margin 19.8%, up from 18.4% in the previous quarter
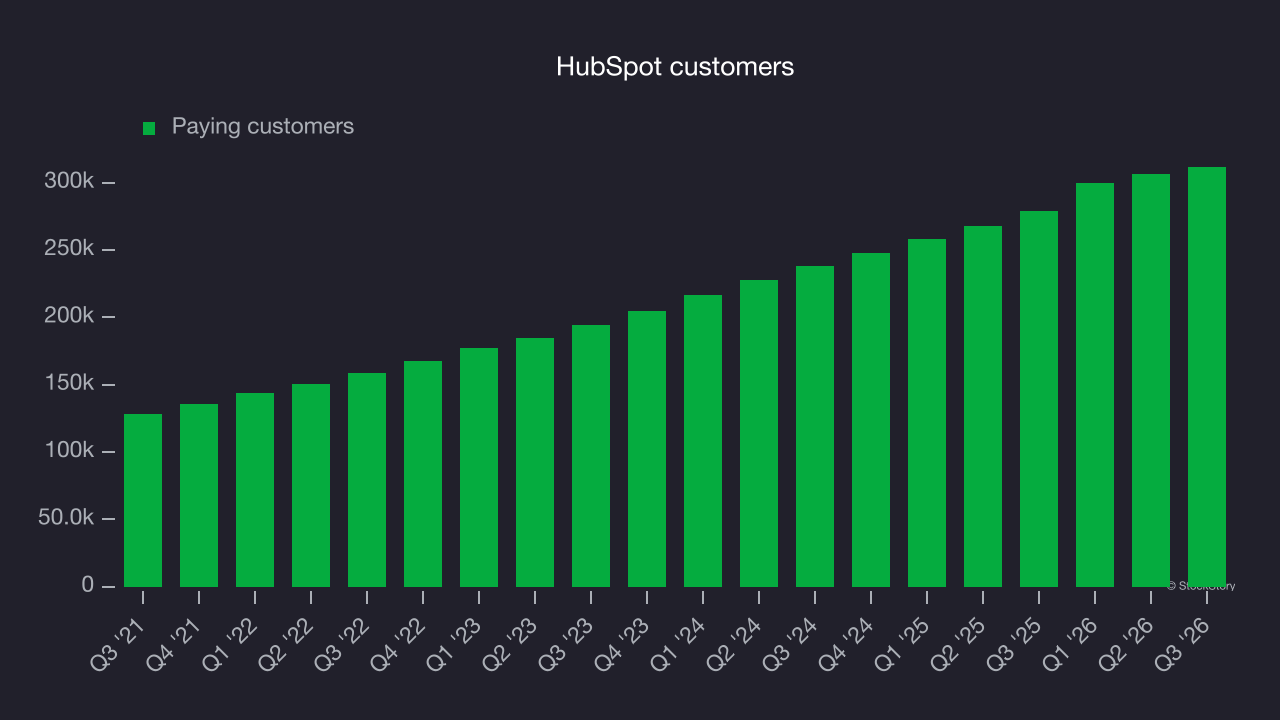
- Customers 311,704, up from 306,446 in the previous quarter
- Billings $924.3 million at quarter end, up 15% year on year
- Market capitalization $11.28 billion
“We are still in the early stages of a massive shift with AI, and we’re transforming HubSpot to lead in the Outcomes Era," said Yamini Rangan, Chief Executive Officer at HubSpot. “AI is fundamentally changing software, from tools that help people do work to agents that do the work and deliver outcomes. We're transforming our product, pricing, go-to-market, and how we operate to capture this opportunity, and we made meaningful progress across these areas this quarter.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. HubSpot’s 24.8% annualized revenue growth over the last five years was solid. Its growth beat the average software company and shows its offerings resonate with customers.
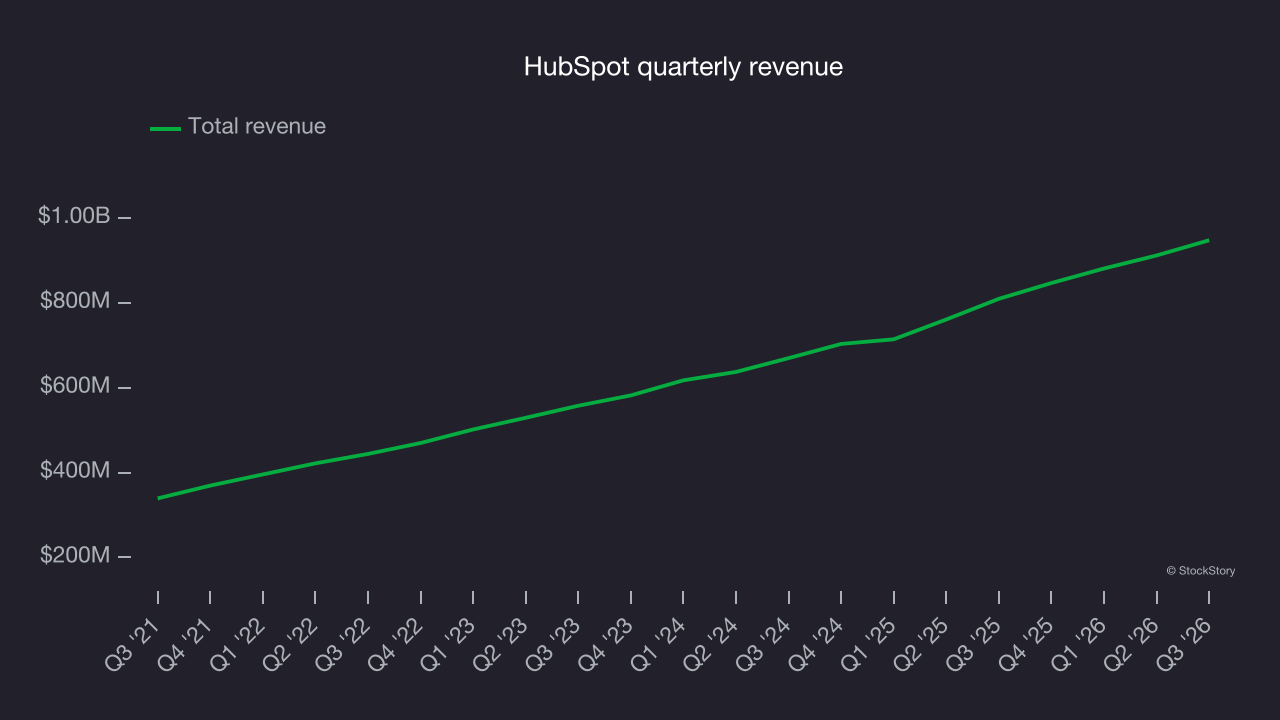
Long-term growth matters most, but within software, a half-decade historical view may miss recent innovations or disruptive industry trends. HubSpot’s annualized revenue growth of 19.6% over the last two years is below its five-year trend, but the results still suggest healthy demand.
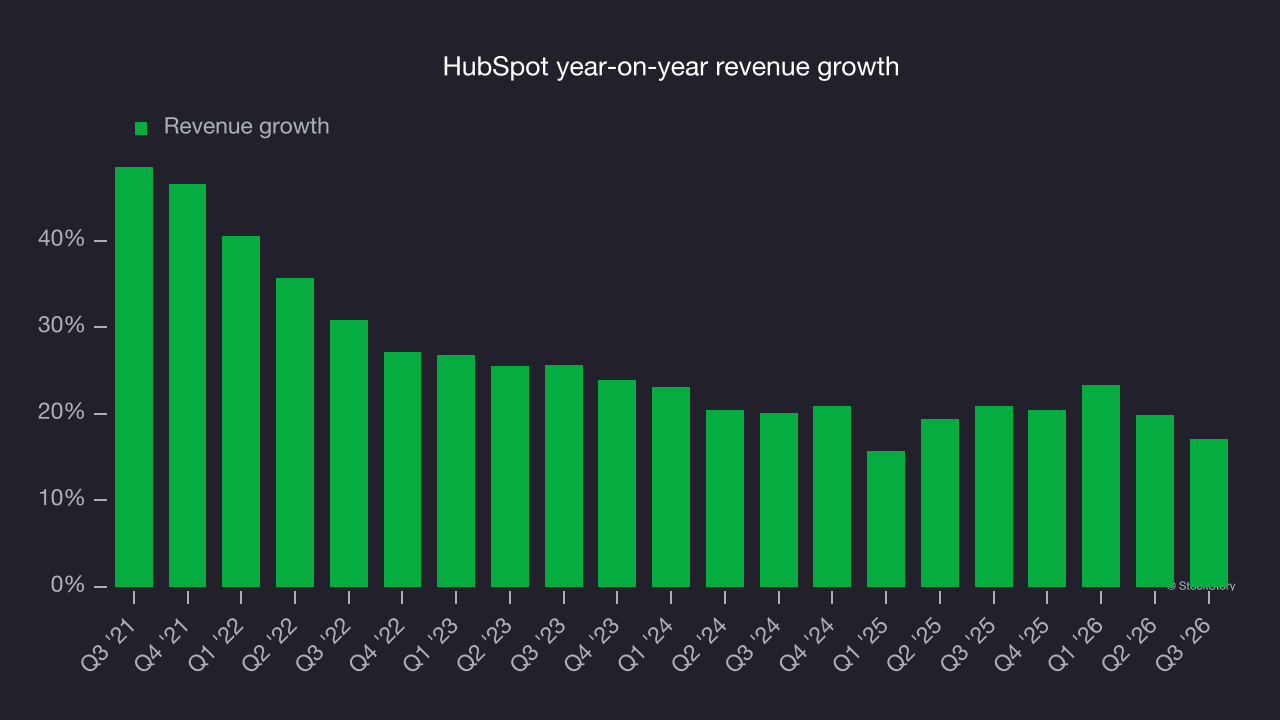
This quarter, HubSpot reported year-on-year revenue growth of 17.1%, and its $947.6 million in revenue exceeded Wall Street’s consensus estimates by 2.4%. Management is guiding for an 11.7% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 13.1% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and suggests its products and services will face some demand challenges. At least the company is tracking well in other measures of financial health.
Billings
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
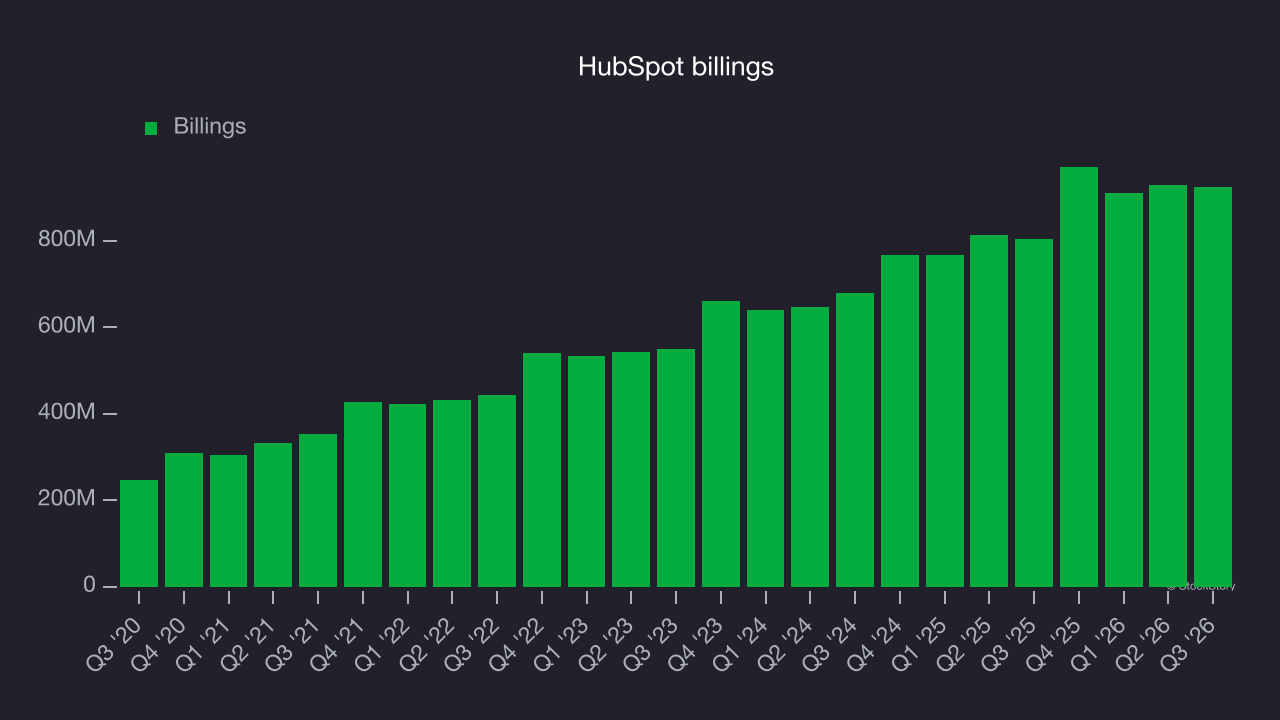
HubSpot’s billings totaled $924.3 million in Q3, and over the last four quarters, growth was solid, averaging 18.7% year-on-year increases. This performance aligned with its total revenue growth, indicating healthy customer demand. The cash collected from customers also enhances liquidity and supports future investment and growth.
Customer base
HubSpot reported 311,704 customers at the end of the quarter, a sequential increase of 5,258. That increase was smaller than in previous quarters, but one quarter should not carry too much weight given its billings growth over the last year.
Key takeaways from HubSpot’s Q3 results
HubSpot’s outlook was uneven: Full-year EPS guidance exceeded Wall Street’s consensus estimates, but revenue and EPS guidance for next quarter fell short. Despite adjusted operating income beating analysts’ consensus expectations by a wide margin, this was a mixed quarter overall. Shares fell 4.2% to $207.05 immediately after the report.
An investment decision on HubSpot should consider the bigger picture of valuation, business quality and the latest earnings. Read the full research report here (it’s free).