Go-to-market intelligence provider ZoomInfo (NASDAQ: GTM) reported revenue ahead of Wall Street’s expectations in Q3 2026, but revenue fell by 2.9% year on year to $308.8 million. Guidance for next quarter’s revenue was better than expected at $295.5 million at the midpoint, 1.2% above analysts’ consensus estimates. Its non-GAAP profit of $0.29 per share was in line with analysts’ consensus estimates.
For more on ZoomInfo, read our free full research report.
ZoomInfo (GTM) Q3 2026 highlights:
- Revenue $308.8 million vs S&P analysts’ consensus estimates of $299.7 million (2.9% year-on-year decline, 3% beat)
- Adjusted EPS $0.29 vs S&P analysts’ consensus estimates of $0.29 (in line)
- Adjusted operating income $119.1 million vs analysts’ consensus estimates of $114.3 million (38.6% margin, 4.2% beat)
- Revenue guidance $295.5 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $291.9 million
- Adjusted EPS guidance Management slightly raised its full-year adjusted EPS guidance to $1.13 at the midpoint
- Operating margin 7.6%, down from 21.2% in the same quarter last year
- Free cash flow margin 28.2%, down from 34.6% in the previous quarter
- Market capitalization $1.23 billion
“ZoomInfo is central to how leading GTM teams and their AI agents get work done, and our headless context layer is now grounding AI agents across dozens of platforms our customers already use,” said Henry Schuck, ZoomInfo Founder and CEO. “Our largest customers continue to invest and grow with us, with our million dollar customer cohort the strongest it has ever been from an ACV and a logo perspective. We continue to prioritize a disciplined balance sheet as we have expanded our approach to capital allocation.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can report a good quarter or two, but the best consistently grow over time. Over the last five years, ZoomInfo grew its revenue at a 13.3% compounded annual growth rate. Though this growth is acceptable on an absolute basis, assessing the software sector requires more than just revenue growth, given the potential for significant earnings volatility. This means the bar for the sector is particularly high, reflecting the non-essential and hit-driven nature of the products and services offered. Additionally, the five-year compounded annual growth rate starts around Covid, when revenue was depressed then rebounded.
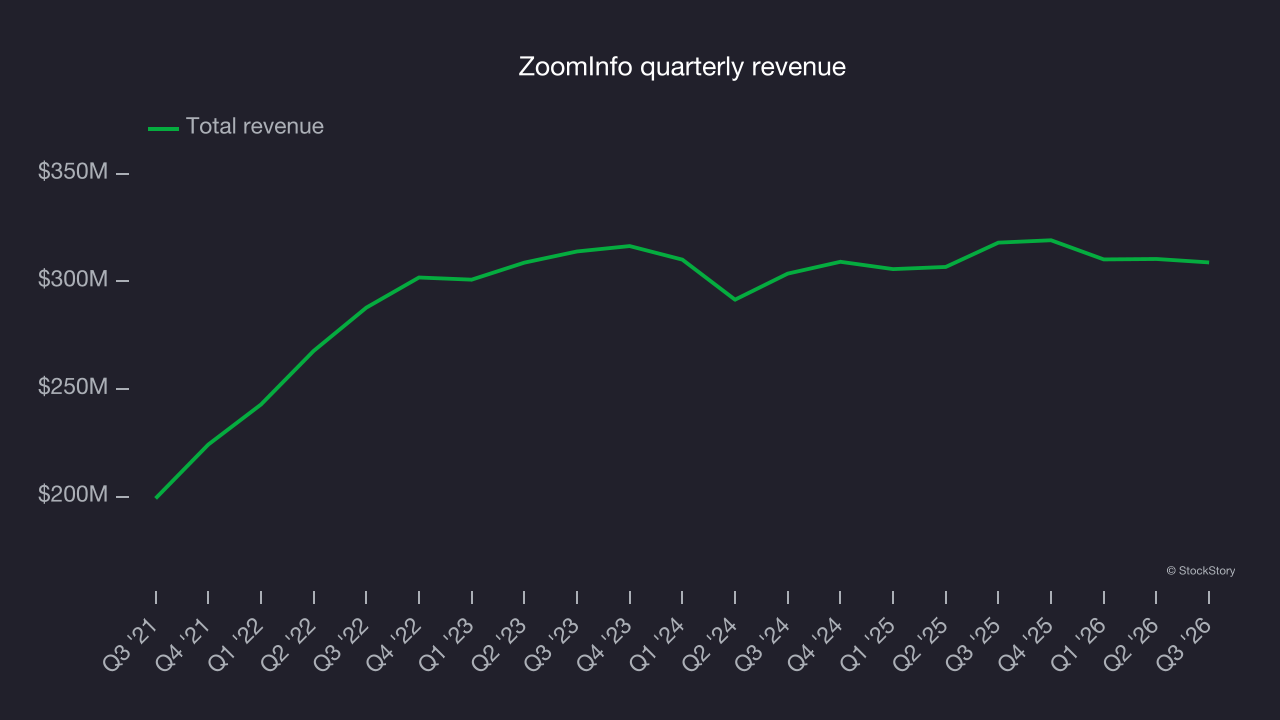
Long-term growth is the most important, but within software, a half-decade historical view may miss new innovations or demand cycles. ZoomInfo’s recent performance shows its demand has slowed as its annualized revenue growth of 1.1% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 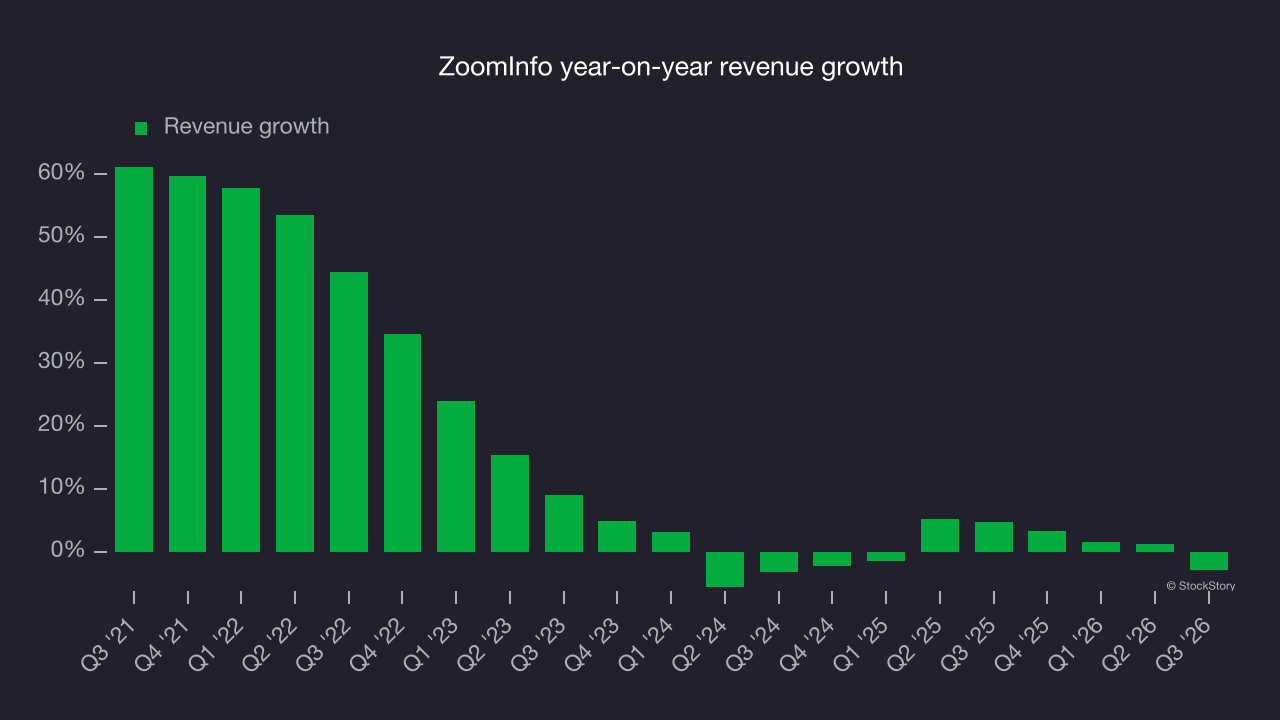
This quarter, ZoomInfo’s revenue fell by 2.9% year on year to $308.8 million but beat Wall Street’s consensus estimates by 3%. Company management is currently guiding for a 7.4% year-on-year decline in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to decline by 5.6% over the next 12 months, according to S&P, a deceleration versus the last two years. This uninspiring projection implies its products and services will face some demand headwinds.
Enterprise customer base
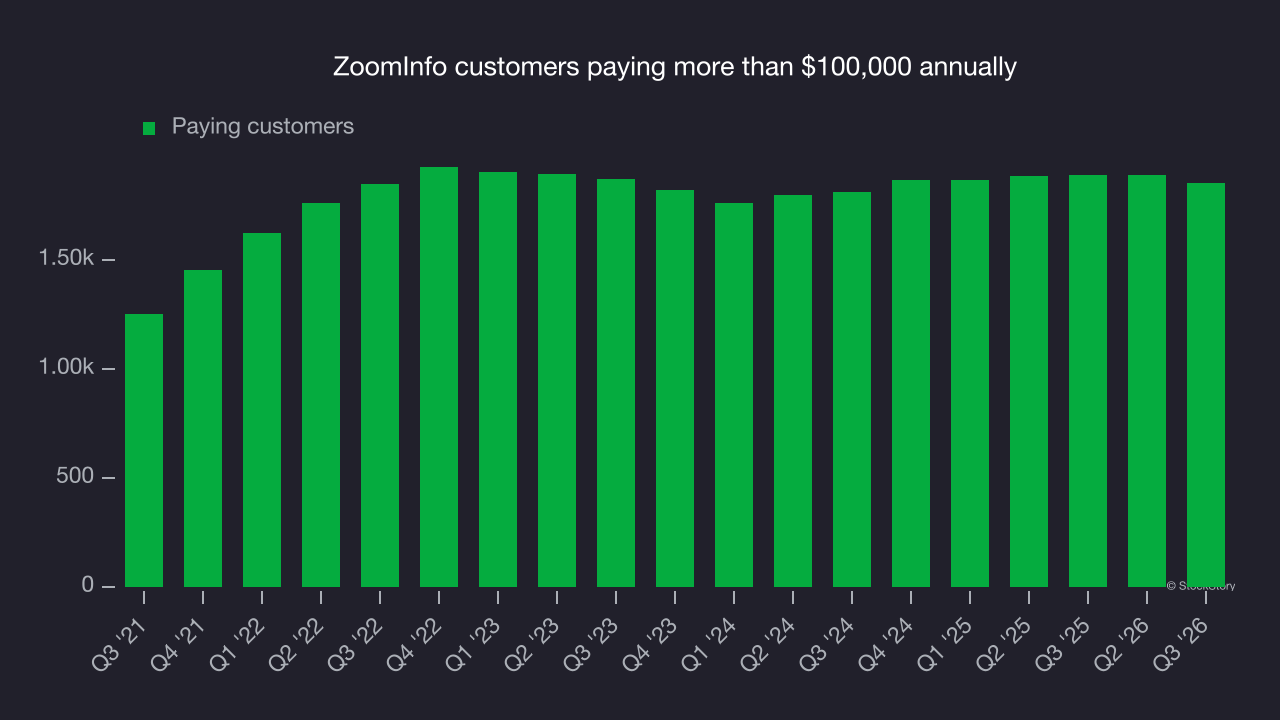
This quarter, ZoomInfo reported 1,851 enterprise customers paying more than $100,000 annually, a decrease of 40 from the previous quarter. Shareholders would likely want to see the company accelerate its revenue growth.
Key takeaways from ZoomInfo’s Q3 results
ZoomInfo’s Q3 results had some key positives: Adjusted operating income beat analysts’ consensus estimates, and EPS guidance for next quarter topped Wall Street’s consensus. Shares remained flat at $4.27 immediately after the release.
ZoomInfo reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. The latest quarter matters, but longer-term business quality and valuation matter more when deciding whether to invest in this stock. For more on ZoomInfo, read our full research report here (it’s free).