
Defense, intelligence, and IT solutions provider CACI International (NYSE: CACI) fell short of the market’s revenue expectations in calendar Q3 2026 (fiscal Q1 2027), but sales rose 8.2% year on year to $2.47 billion. On the other hand, the company’s outlook for the full year was close to analysts’ estimates with revenue guided to $10.8 billion at the midpoint. Its non-GAAP profit of $7.66 per share was 16% above analysts’ consensus estimates.
Is now the time to buy CACI? Find out by accessing our full research report, it’s free.
CACI (CACI) Q3 CY2026 highlights:
- Revenue: $2.47 billion vs analyst estimates of $2.51 billion (8.2% year-on-year growth, 1.4% miss)
- Adjusted EPS: $7.66 vs analyst estimates of $6.60 (16% beat)
- Adjusted EBITDA: $328.8 million vs analyst estimates of $292.2 million (13.3% margin, 12.5% beat)
- The company slightly lifted its revenue guidance for the full year to $10.8 billion at the midpoint from $10.75 billion
- Management slightly raised its full-year Adjusted EPS guidance to $33.63 at the midpoint
- Operating Margin: 10%, in line with the same quarter last year
- Free Cash Flow Margin: 5.4%, down from 6.7% in the same quarter last year
- Backlog: $34 billion at quarter end, in line with the same quarter last year
- Market Capitalization: $13.43 billion
"Our first quarter results represent a strong start to fiscal year 2027, highlighted by revenue and EBITDA growth, strong EBITDA margin, and healthy free cash flow. We also delivered a 2.0x book-to-bill and another quarter of double-digit funded backlog growth. Our mission proximity, software-defined approach, ability to invest ahead of customer need, and superior execution continue to differentiate CACI and drive our performance," said John Mengucci, CACI President and Chief Executive Officer. "Based on our results, large and growing backlog, and healthy pipeline, we are raising our fiscal year 2027 revenue and earnings profit outlook while reaffirming guidance for other financial metrics. We remain confident in our ability to drive long-term growth in free cash flow per share and deliver exceptional value for our customers and shareholders."
Company overview
Founded to commercialize SIMSCRIPT, CACI International (NYSE: CACI) offers defense, intelligence, and IT solutions to support national security and government transformation efforts.
Revenue growth
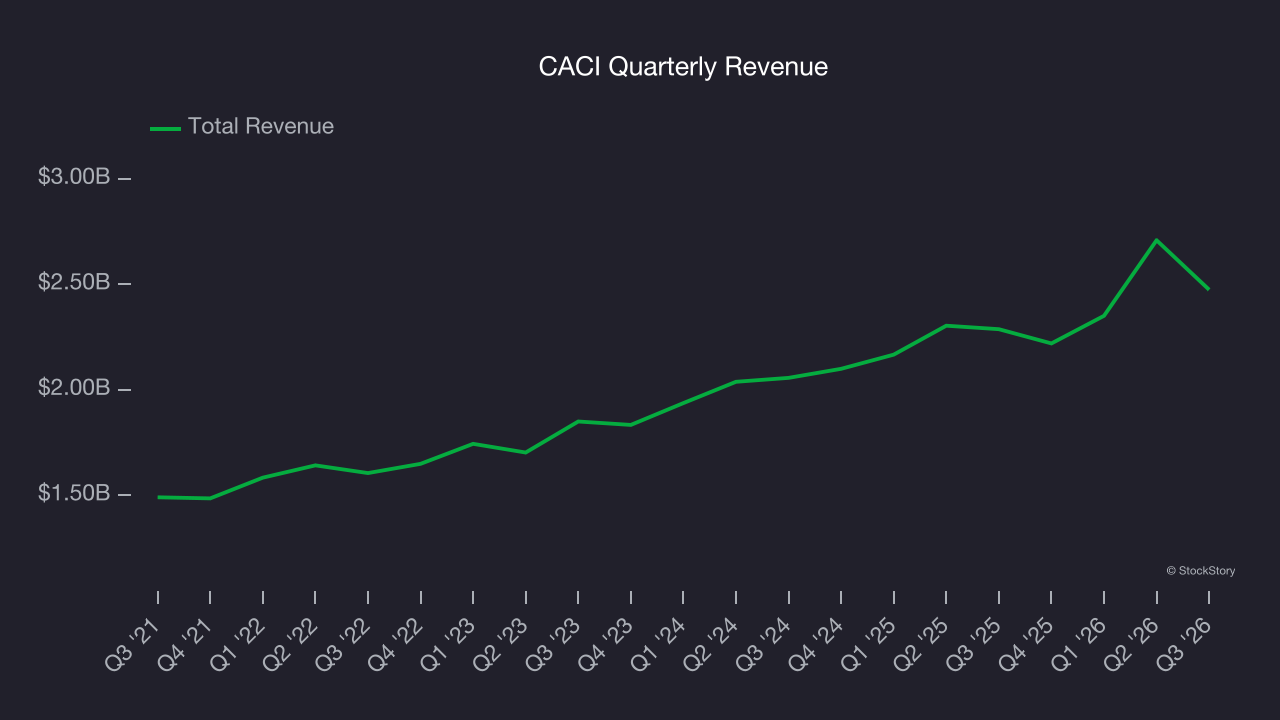
A company’s long-term sales performance can indicate its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Thankfully, CACI’s 9.9% annualized revenue growth over the last five years was solid. Its growth beat the average industrials company and shows its offerings resonate with customers, a helpful starting point for our analysis.
We at StockStory place the most emphasis on long-term growth, but within industrials, a half-decade historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. CACI’s annualized revenue growth of 11.4% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 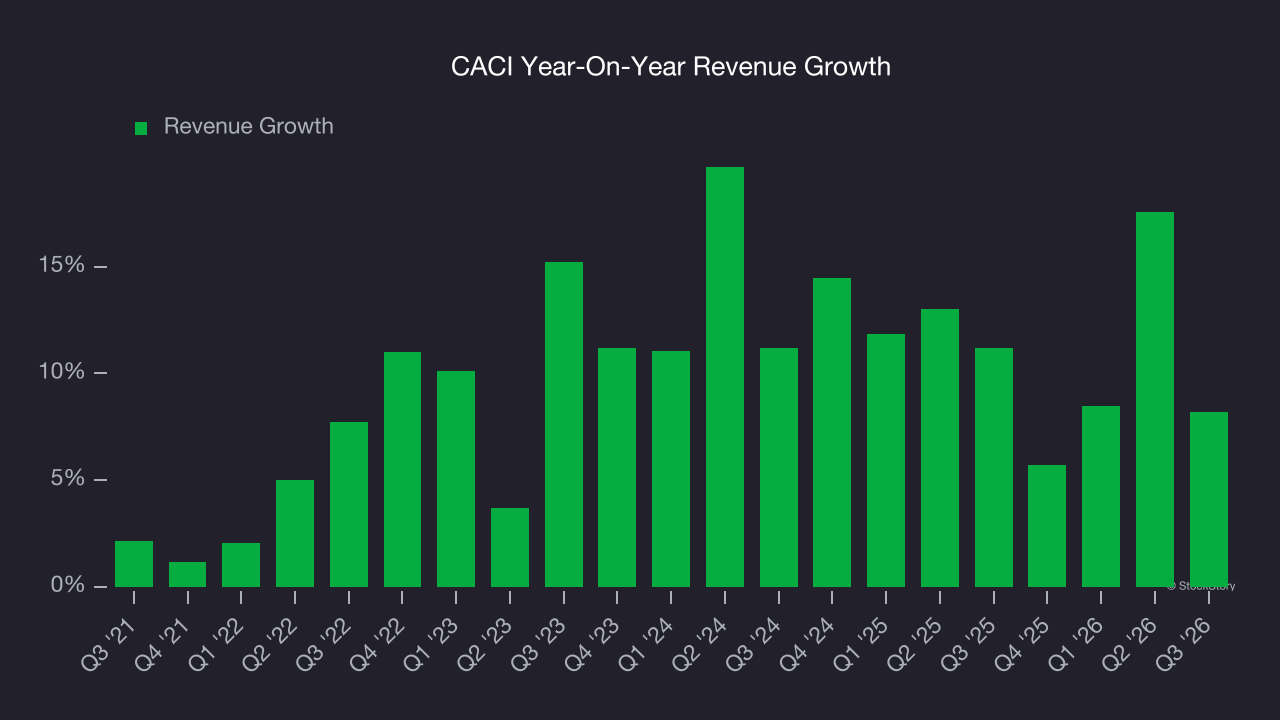
We can dig further into the company’s revenue dynamics by analyzing its backlog, or the value of its outstanding orders that have not yet been executed or delivered. CACI’s backlog reached $34 billion in the latest quarter and averaged 3% year-on-year growth over the last two years. Because this number is lower than its revenue growth, we can see the company fulfilled orders at a faster rate than it added new orders to the backlog. This implies CACI was operating efficiently but raises questions about the health of its sales pipeline. 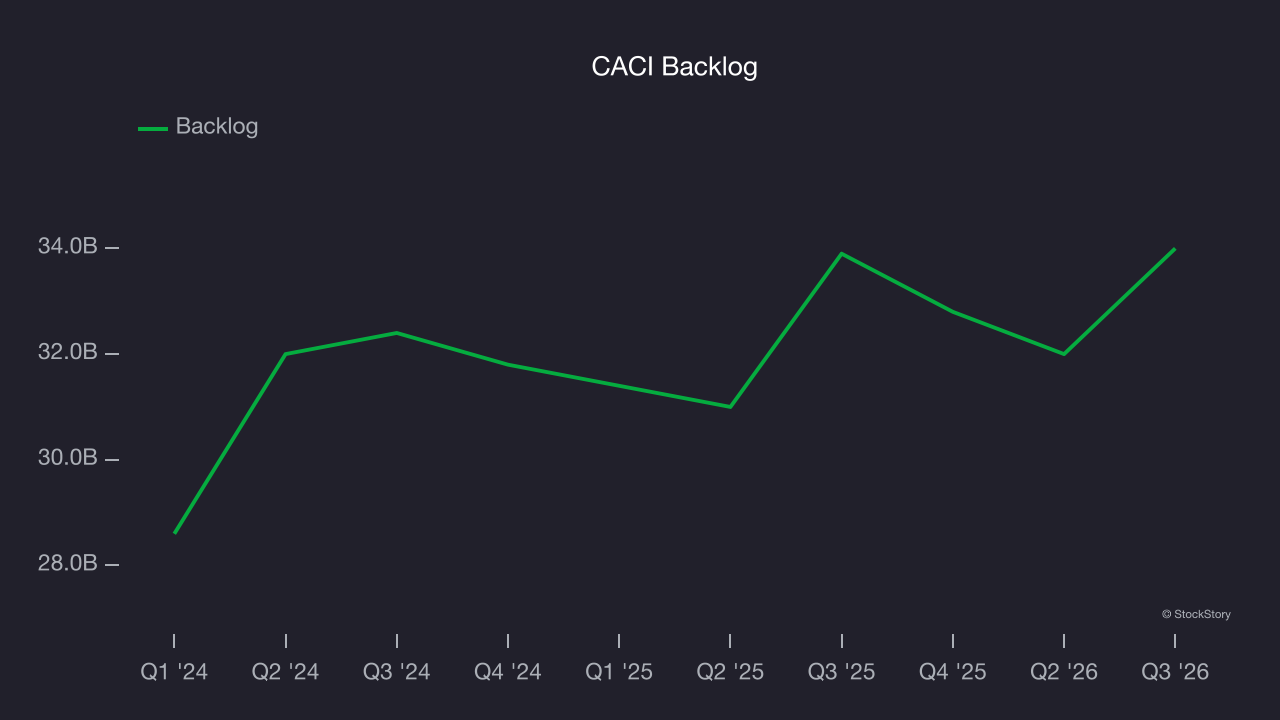
This quarter, CACI’s revenue grew by 8.2% year on year to $2.47 billion, missing Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 12.3% over the next 12 months, similar to its two-year rate. This projection is healthy and indicates the market sees success for its products and services.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Operating margin
CACI has done a decent job managing its cost base over the last five years. The company has produced an average operating margin of 8.9%, higher than the broader industrials sector.
Analyzing the trend in its profitability, CACI’s operating margin rose by 1.8 percentage points over the last five years, as its sales growth gave it operating leverage.
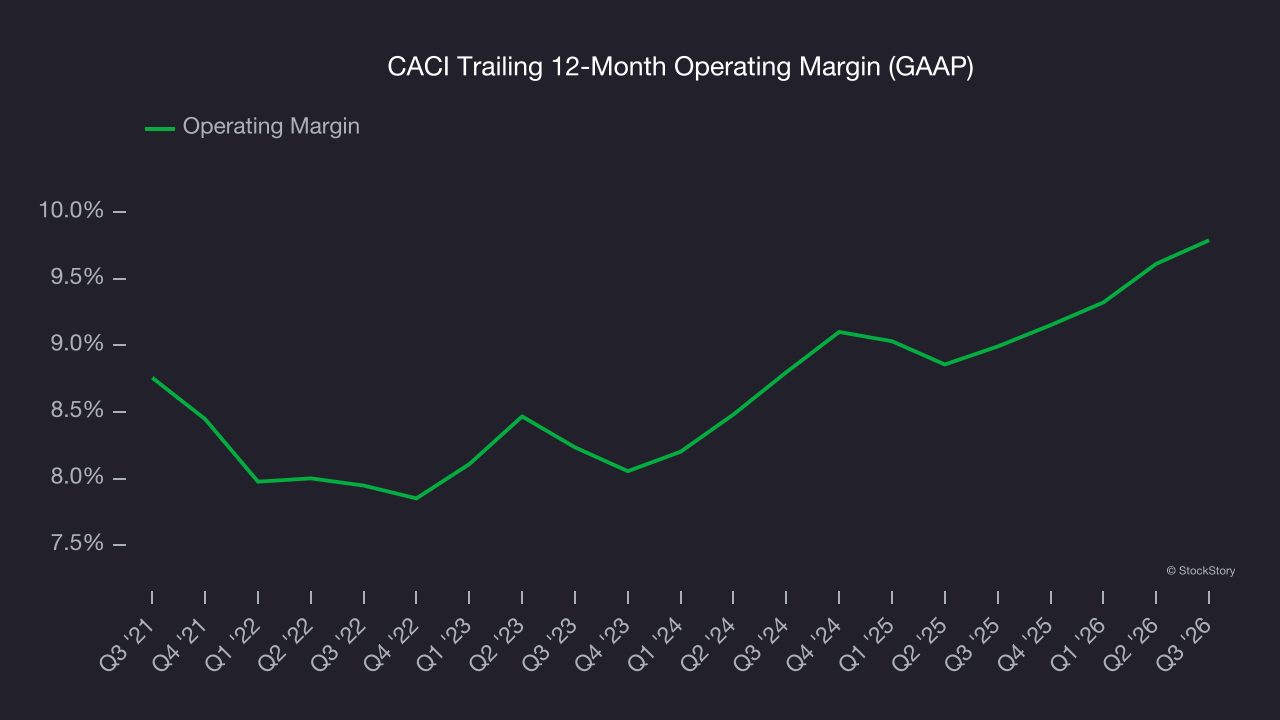
In Q3, CACI generated an operating margin profit margin of 10%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
CACI’s solid 10.1% annual EPS growth over the last five years aligns with its revenue performance. This tells us its incremental sales were profitable.
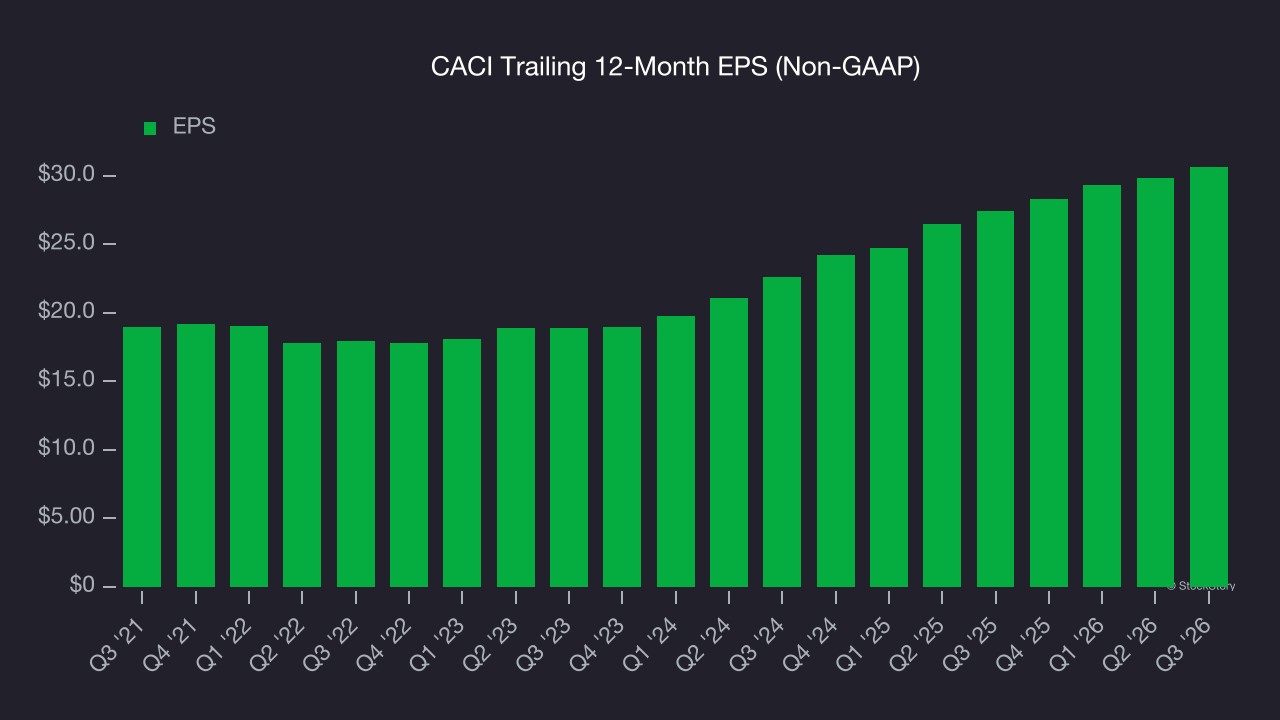
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
CACI’s two-year annual EPS growth of 16.4% was great and topped its 11.4% two-year revenue growth.
We can take a deeper look into CACI’s earnings to better understand the drivers of its performance. While we mentioned earlier that CACI’s operating margin was flat this quarter, a two-year view shows its margin has expanded. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, CACI reported adjusted EPS of $7.66, up from $6.85 in the same quarter last year. This print easily cleared analysts’ estimates, and shareholders should be content with the results. Over the next 12 months, Wall Street expects CACI’s full-year EPS to grow 13.7% from $30.65 to $34.84.
Key takeaways from CACI’s Q3 results
We were impressed by how significantly CACI blew past analysts’ EBITDA expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. On the other hand, its revenue slightly missed. Overall, this print had some key positives. The stock remained flat at $624.32 immediately after reporting.
CACI may have had a good quarter, but does that mean you should invest right now? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).