
Automotive technology company Visteon (NYSE: VC) will be announcing earnings results this Thursday morning. Here’s what investors should know.
Visteon met analysts’ revenue expectations last quarter, reporting revenues of $960 million, flat year on year. It was a softer quarter for the company, with a significant miss of analysts’ EBITDA estimates and a significant miss of analysts’ EPS estimates.
Is Visteon a buy or sell going into earnings? Read our full analysis here, it’s free for active Edge members.
This quarter, the market is expecting Visteon’s revenue to grow 1.7% year on year, a reversal from the 6.4% decrease it recorded in the same quarter last year.
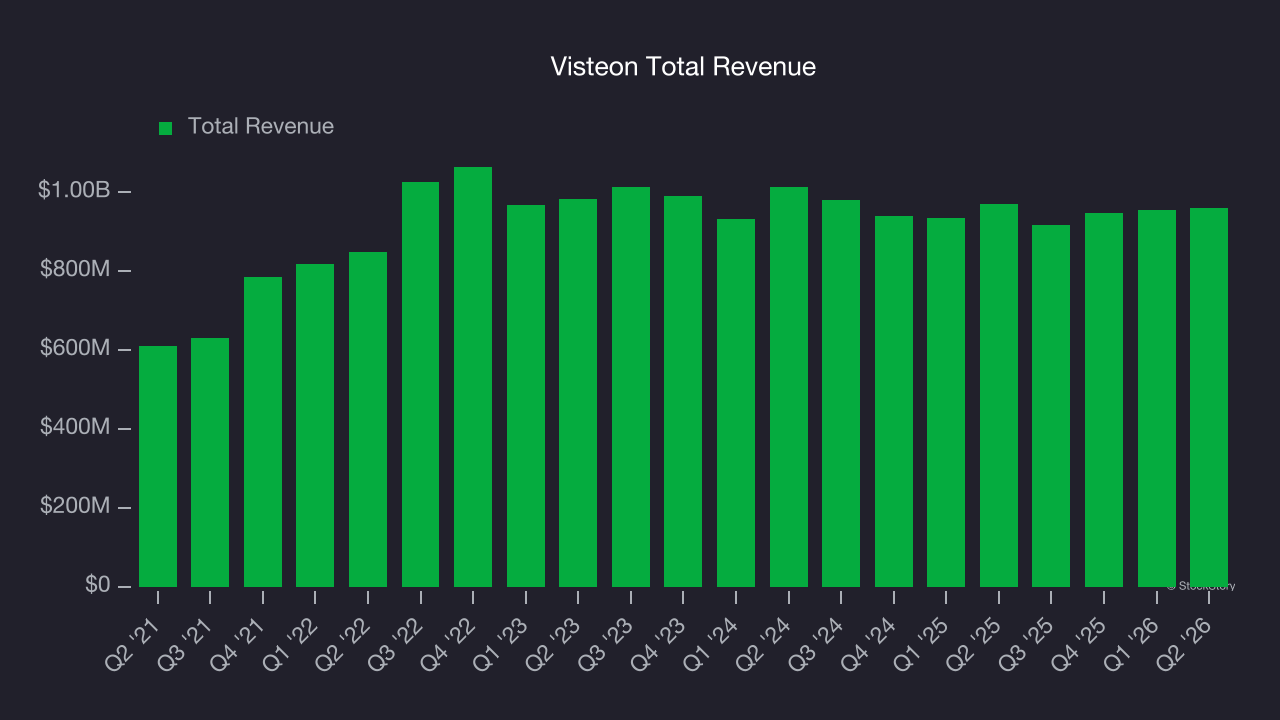
Analysts covering the company have generally reconfirmed their estimates over the last 30 days, suggesting they anticipate the business will stay the course heading into earnings. Visteon has missed Wall Street’s revenue estimates multiple times over the last two years.
Looking at Visteon’s peers in the industrials segment, some have already reported their Q3 results, giving us a hint as to what we can expect. General Motors delivered year-on-year revenue growth of 2.9%, beating analysts’ expectations by 2.7%, and Richardson Electronics reported revenues up 18.9%, topping estimates by 10.1%. Richardson Electronics’s stock price was unchanged following the results.
Read our full analysis of General Motors’s results here and Richardson Electronics’s results here.
Over the last year or so, investors' attention has moved from one major market theme to the next, spanning AI disruption and surging infrastructure investment to geopolitical tensions, interest rates, and the health of the broader economy. While some of the industrials stocks have shown solid performance in this choppy environment, the group has generally underperformed, with share prices down 5.1% on average over the last month. Visteon is down 4.3% during the same time and is heading into earnings with an average analyst price target of $119.80 (compared to the current share price of $87.92).
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.