
Water management solutions company Zurn Elkay (NYSE: ZWS) met Wall Street’s revenue expectations in Q3 2026, with revenue rising 8.7% year on year to $495.1 million. On the other hand, next quarter’s revenue guidance of $433.5 million was less impressive, coming in 1% below analysts’ consensus estimates. Its non-GAAP profit of $0.52 per share was 4.2% above analysts’ consensus estimates.
For more on Zurn Elkay, read our free full research report.
Zurn Elkay (ZWS) Q3 2026 highlights:
- Revenue $495.1 million vs S&P analysts’ consensus estimates of $492.8 million (8.7% year-on-year growth, in line)
- Adjusted EPS $0.52 vs S&P analysts’ consensus estimates of $0.50 (4.2% beat)
- Adjusted EBITDA $140.1 million vs analysts’ consensus estimates of $138.2 million (28.3% margin, 1.4% beat)
- Revenue guidance $433.5 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $438.1 million
- EBITDA guidance $121.5 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $118.9 million
- Operating margin 21.9%, up from 17% in the same quarter last year
- Free cash flow margin 20.7%, similar to the same quarter last year
- Organic revenue rose 7% year on year
- Market capitalization $8.18 billion
Adams continued, “Last quarter we announced the acquisition of Intellihot, which along with our Wilkins backflow are key components of the hot water loop. Earlier this month, we continued to build out our presence in the hot water loop with the entrance into the digital master mixing valve market with internally developed new products that we believe will allow us to take meaningful, profitable share in the category over the next several years. These breakthrough initiatives are part of our continued focus to leverage our significant competitive advantages into adjacencies. In 2026 alone, we believe we’ve expanded our served markets by roughly $400 million. While we’re encouraged with our progress, we are also aware that we must continue to be nimble in finding pockets of growth to offset the general uncertainty that exists within our served markets and the broader economy.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Over the last five years, Zurn Elkay grew its revenue at a strong 16.1% compounded annual growth rate. Its growth beat the average industrials company and shows its offerings resonate with customers.
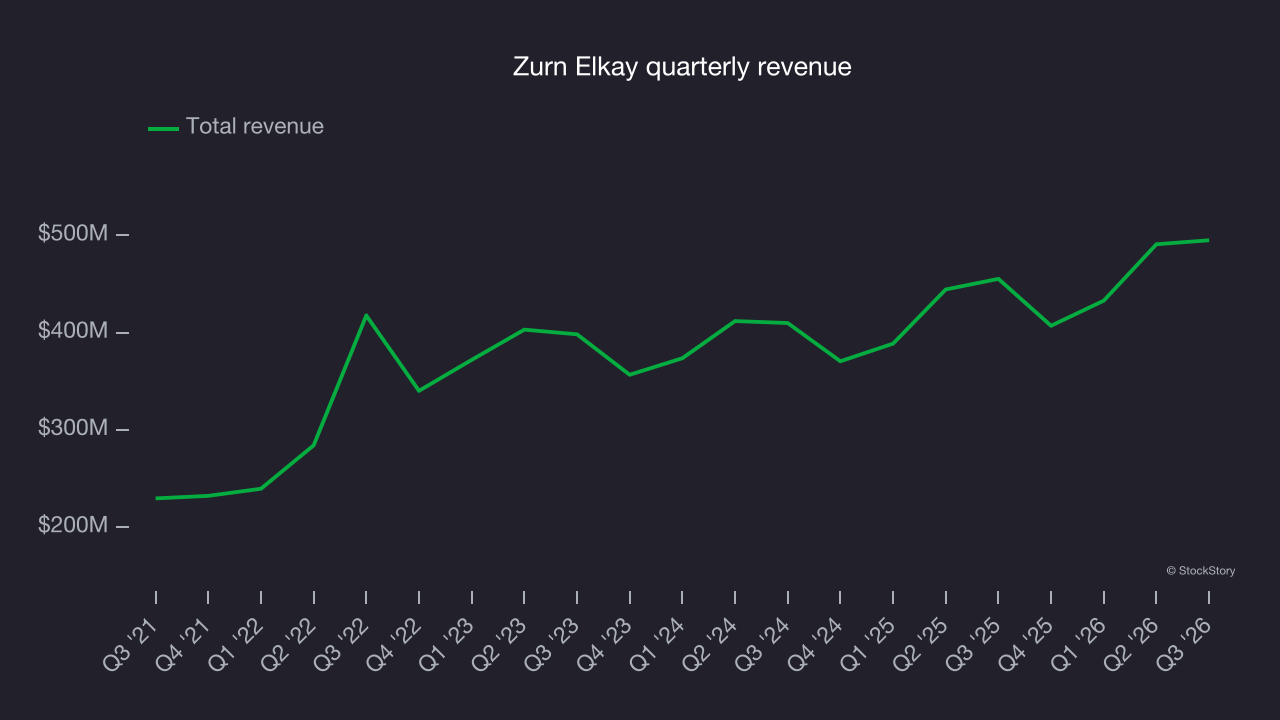
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Zurn Elkay’s annualized revenue growth of 8.5% over the last two years is below its five-year trend, but the results were still respectable. 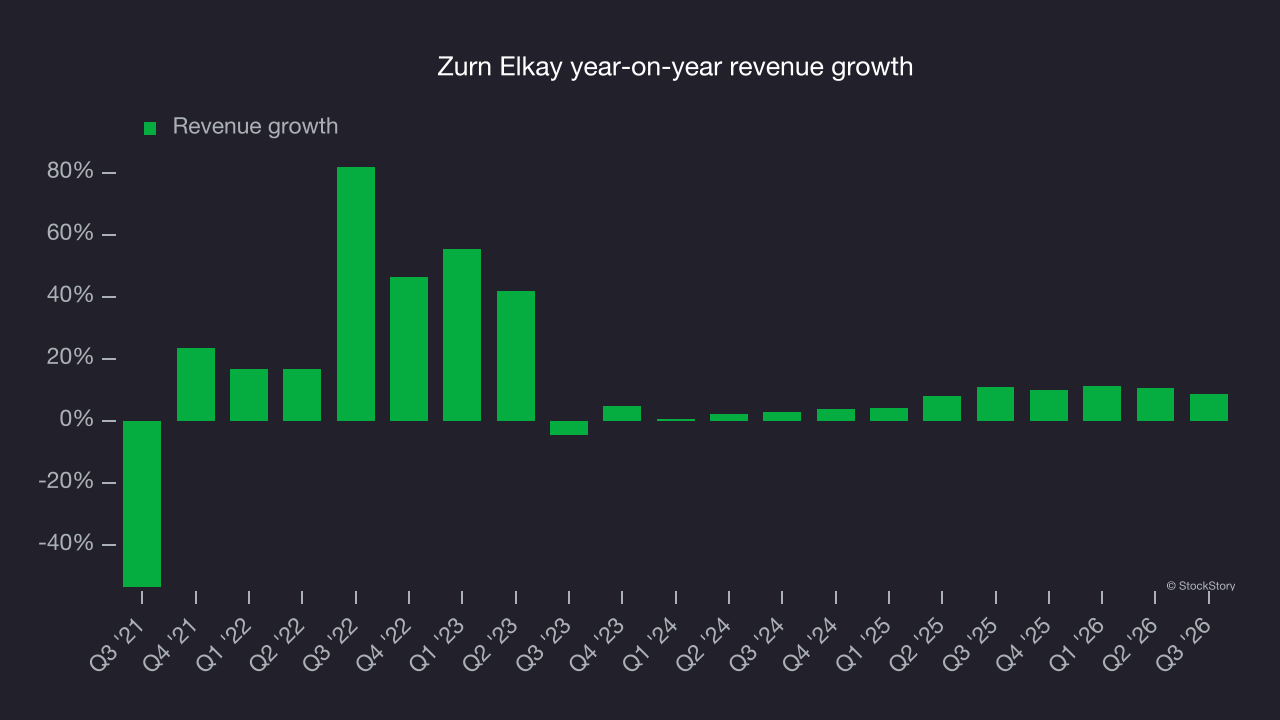
We can better understand the company’s revenue dynamics by analyzing its organic revenue, which strips out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, Zurn Elkay’s organic revenue averaged 7.3% year-on-year growth. This was in line with its two-year revenue growth, indicating that the company’s core operations, rather than acquisitions and divestitures, drove most of its results. 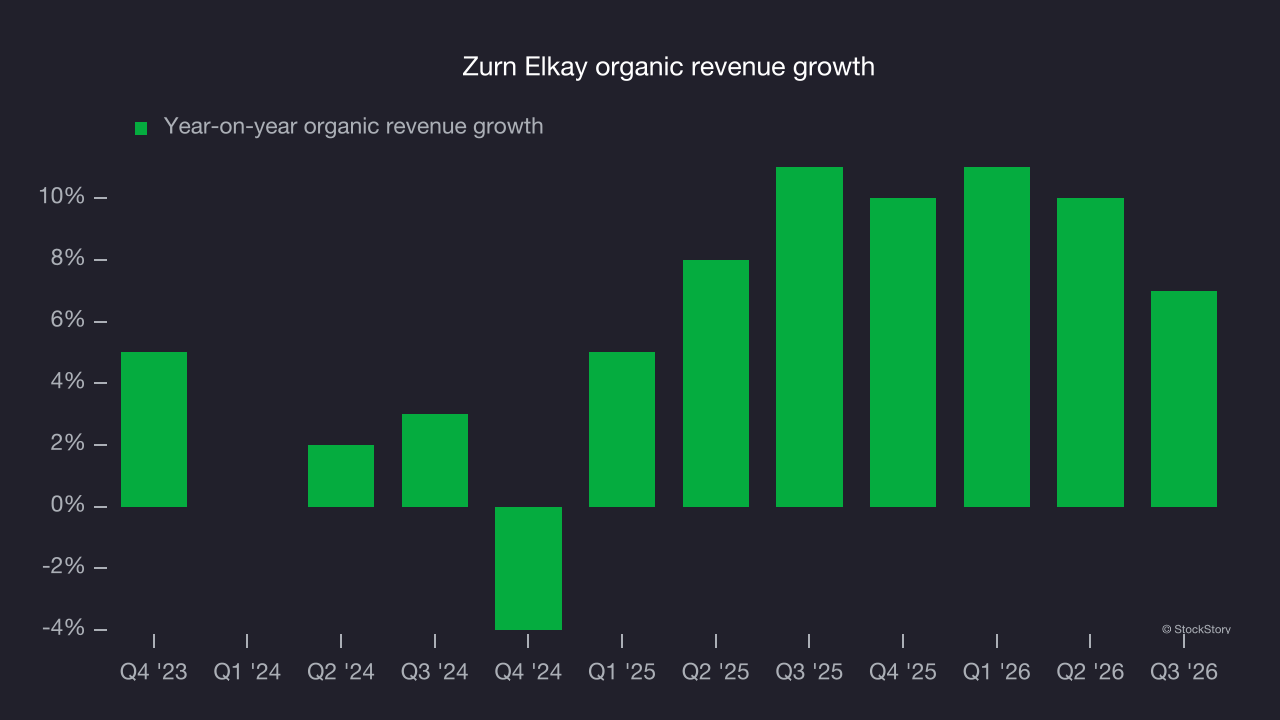
This quarter, Zurn Elkay grew its revenue by 8.7% year on year, and its $495.1 million of revenue was in line with Wall Street’s consensus estimates. Company management is currently guiding for a 6.5% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 6.6% over the next 12 months, according to S&P, a slight deceleration versus the last two years. This projection is underwhelming and indicates its products and services will see some demand headwinds. At least the company is tracking well in other measures of financial health.
Operating margin
Zurn Elkay has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, with an average operating margin of 15.2%. This result is unsurprising given its favorable gross margin baseline.
Looking at the trend in its profitability, Zurn Elkay’s operating margin rose by 13.5 percentage points over the last five years, as its revenue growth provided operating leverage.
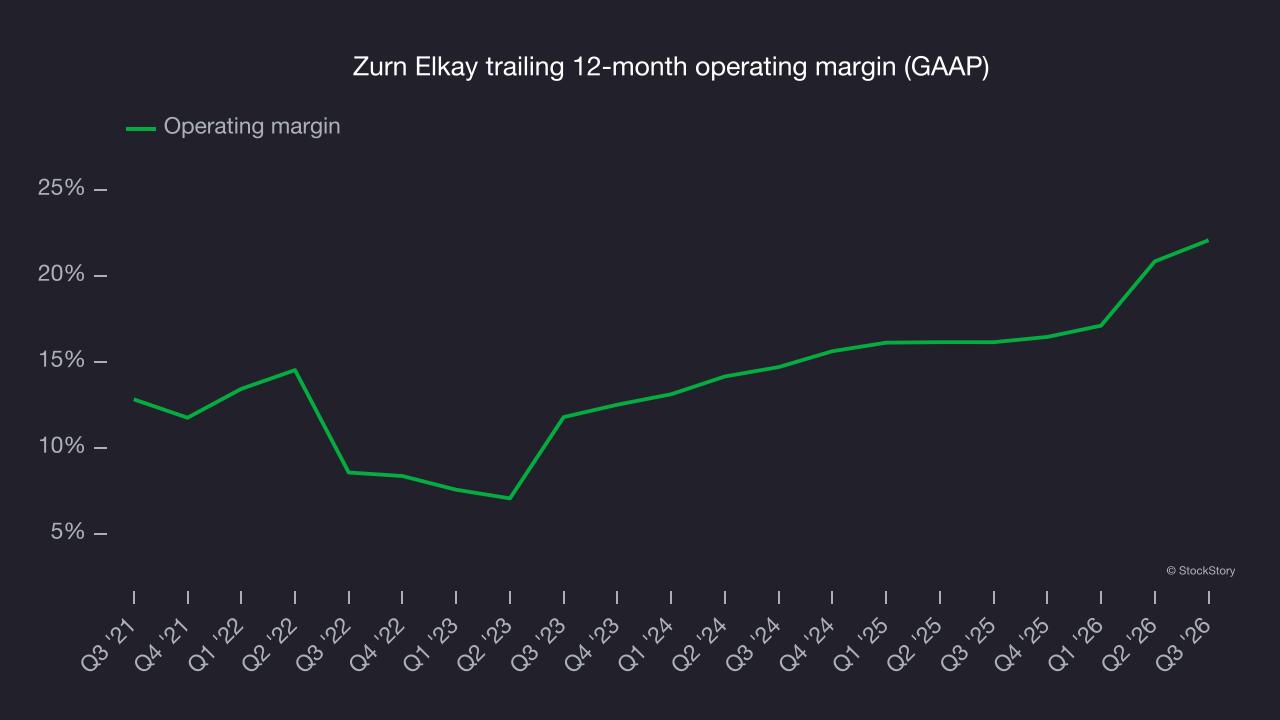
In Q3, Zurn Elkay generated an operating margin of 21.9%, up 4.8 percentage points year on year. Its gross margin expanded more than its operating margin, indicating that leverage on its cost of sales was the primary driver of the recent efficiency gains.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
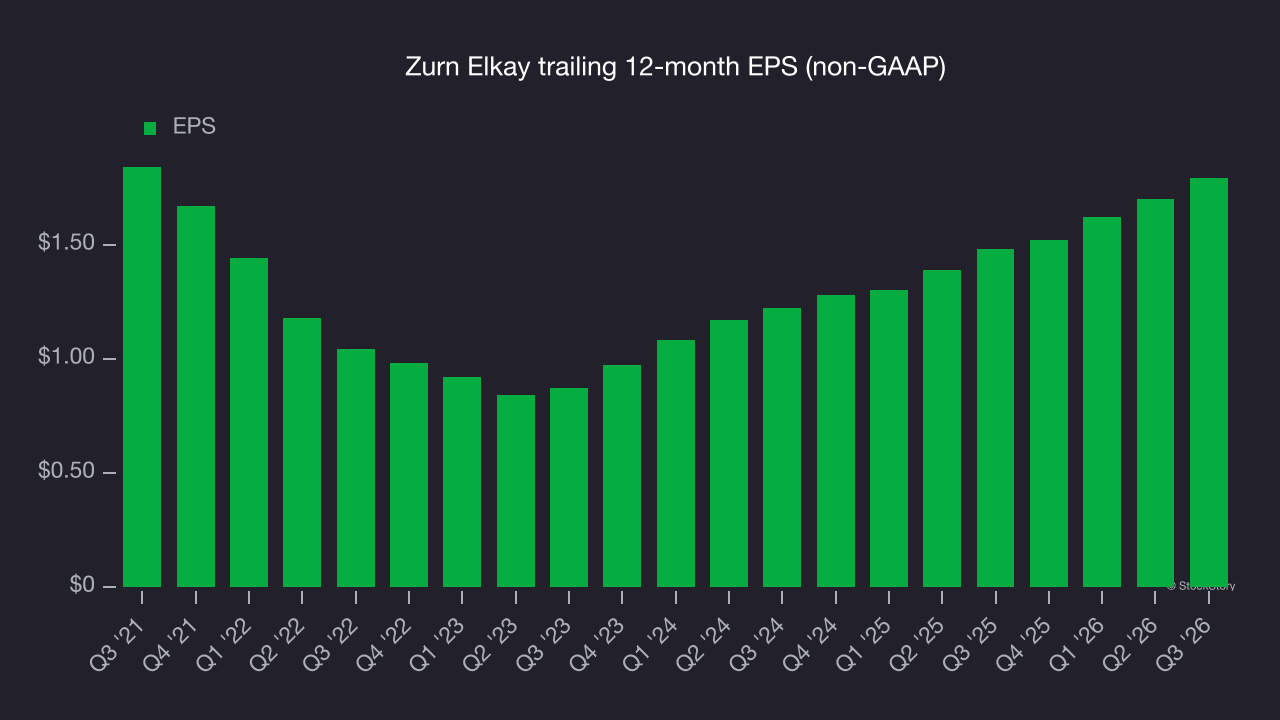
Zurn Elkay’s flat EPS over the last five years was below its 16.1% annualized revenue growth. However, its operating margin improved during this time, indicating that non-fundamental factors such as interest expenses and taxes affected its ultimate earnings.
Diving into the nuances of Zurn Elkay’s earnings can give us a better understanding of its performance. A five-year view shows Zurn Elkay has diluted its shareholders, growing its share count by 34.4%. This dilution overshadowed its increased operational efficiency and has led to lower per share earnings. Taxes and interest expenses can also affect EPS but don’t tell us as much about a company’s fundamentals. 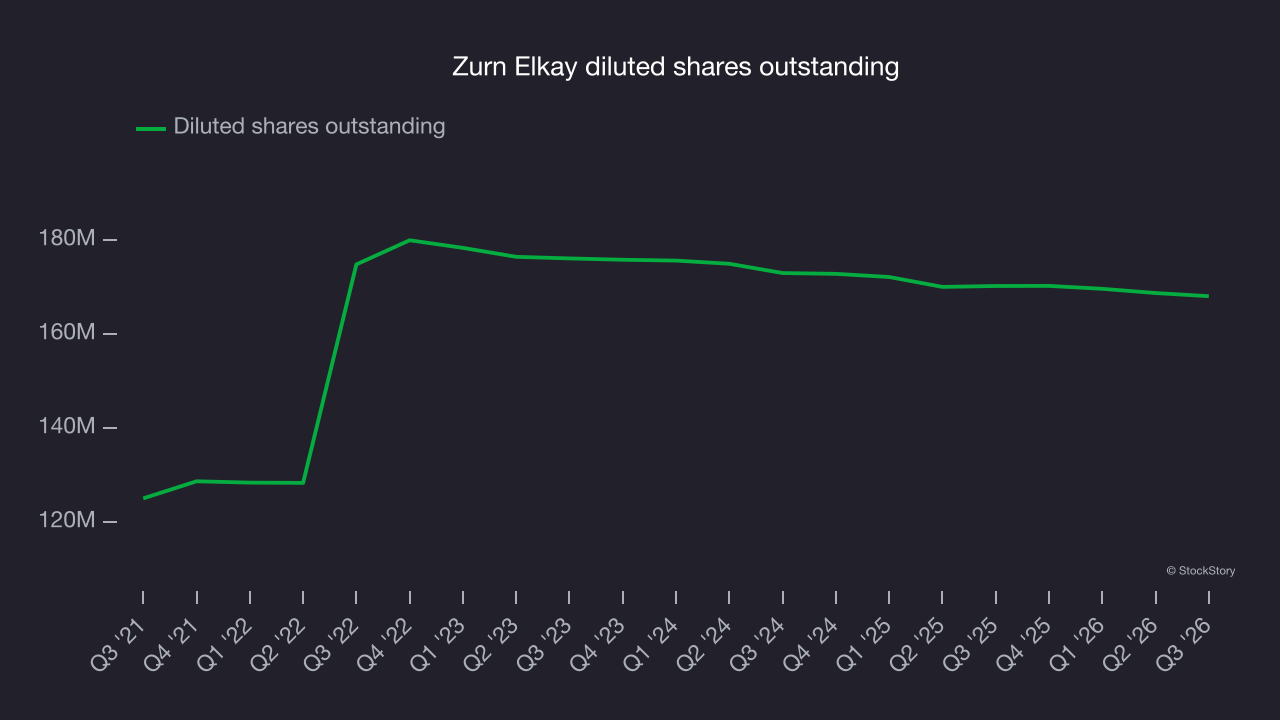
As with revenue, examining EPS over a more recent period can provide insight into an emerging theme or development for the business.
For Zurn Elkay, its two-year annual EPS growth of 21.1% was higher than its five-year trend. This acceleration made it one of the faster-growing industrials companies in recent history.
In Q3, Zurn Elkay reported adjusted EPS of $0.52, up from $0.43 in the same quarter last year. This result beat analysts’ consensus estimates by 4.2%. Over the next 12 months, Wall Street expects Zurn Elkay’s full-year EPS to grow 12.8% from $1.79 to $2.02, according to S&P.
Key takeaways from Zurn Elkay’s Q3 results
Zurn Elkay delivered a mixed quarter, with EBITDA narrowly beating Wall Street’s consensus estimates and next-quarter guidance pointing in different directions. Its EBITDA outlook topped analysts’ consensus estimates, but revenue guidance fell slightly short. The market seemed to be hoping for more, and shares tumbled 6.7% to $45.88 immediately after the results.
For investors considering Zurn Elkay, the latest quarter matters, but not nearly as much as longer-term fundamentals and valuation when deciding whether to buy the stock. Read our full research report for more on these factors (it’s free).