
Oncology (cancer) diagnostics company NeoGenomics (NASDAQ: NEO) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 11.4% year on year to $209.3 million. The company expects the full year’s revenue to be around $808 million, close to analysts’ consensus estimates. Its non-GAAP profit of $0.07 per share was 26.2% above analysts’ consensus estimates.
For more on NeoGenomics, read our free full research report.
NeoGenomics (NEO) Q3 2026 highlights:
- Revenue $209.3 million vs S&P analysts’ consensus estimates of $206.9 million (11.4% year-on-year growth, 1.1% beat)
- Adjusted EPS $0.07 vs S&P analysts’ consensus estimates of $0.06 (26.2% beat)
- Adjusted EBITDA $18.67 million vs analysts’ consensus estimates of $15.83 million (8.9% margin, 17.9% beat)
- Revenue guidance The company slightly lifted its revenue guidance for the full year to $808 million at the midpoint from $804 million
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $0.22 at the midpoint, a 16.2% increase
- EBITDA guidance $60 million at the midpoint for the full year, above analysts’ consensus estimates of $57.3 million
- Operating margin -3.8%, up from -14.4% in the same quarter last year
- Market capitalization $2.22 billion
“Our third-quarter results reinforce that we have the right strategy in place and the right team to execute against it,” said Tony Zook, Chief Executive Officer of NeoGenomics. “Clinical revenue growth of 13% continues to showcase the strength of our broad-based testing solutions portfolio, with NGS revenue growing a strong 29% and NGS test volume growing 17%. As our business continues its shift to higher-value, high-margin testing modalities, we see further opportunity to invest into our commercial teams, community channel strength, and product pipeline. At the same time, we expect to reduce complexity across our business through operational excellence initiatives designed to deliver accelerating growth and disciplined margin expansion over the long-term.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. NeoGenomics’s revenue grew at a decent 10.2% compounded annual growth rate over the last five years. Its growth was slightly above that of the average healthcare company and shows its offerings resonate with customers.
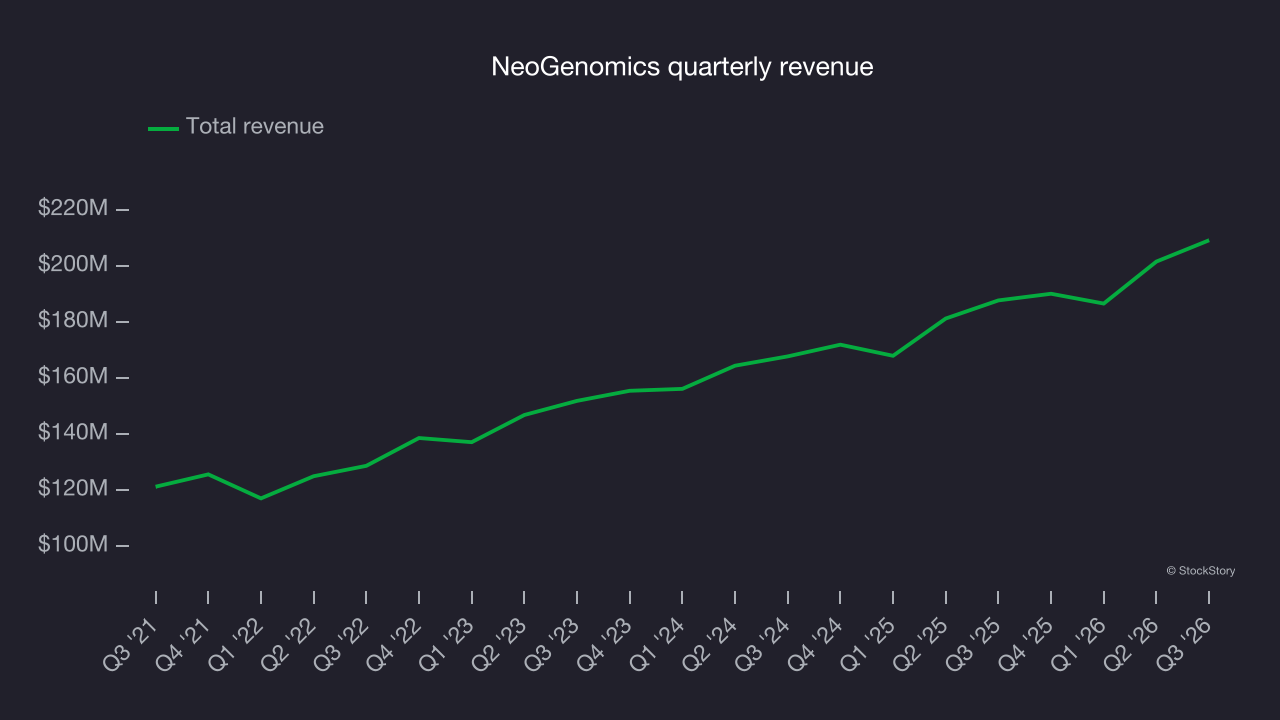
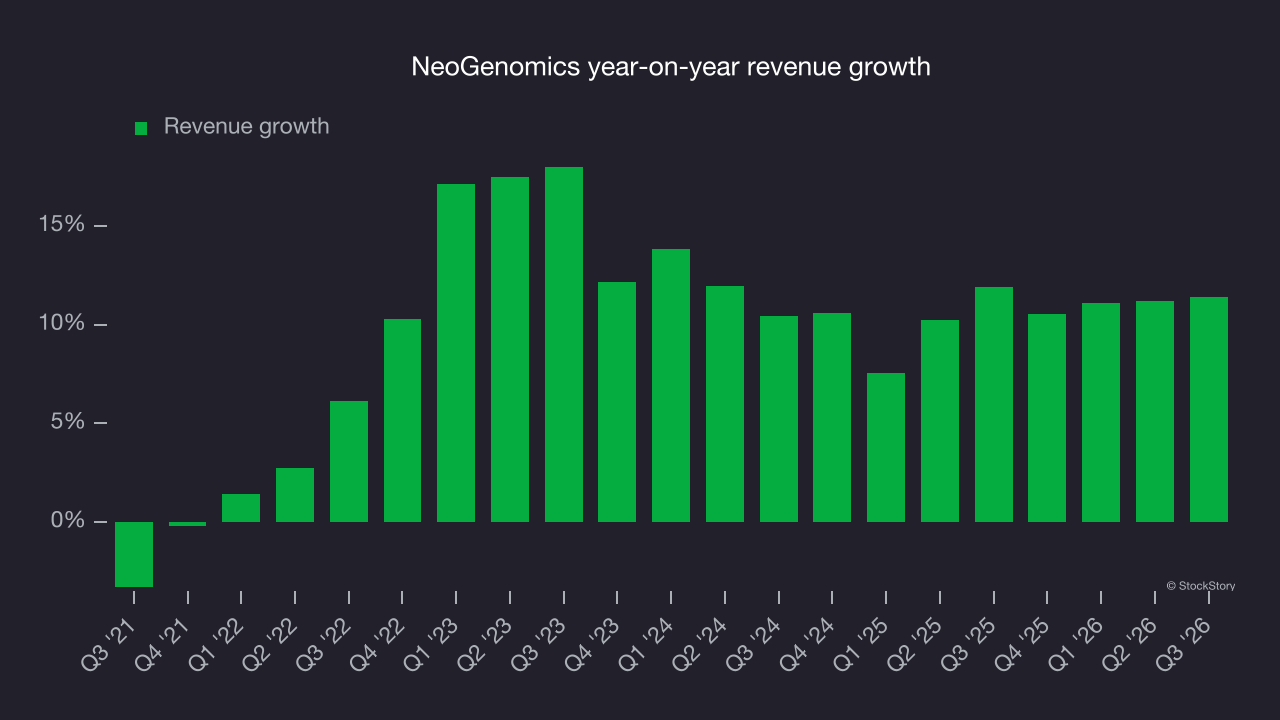
This quarter, NeoGenomics reported year-on-year revenue growth of 11.4%, and its $209.3 million of revenue exceeded Wall Street’s consensus estimates by 1.1%.
Looking ahead, sell-side analysts expect revenue to grow 9.6% over the next 12 months, according to S&P, similar to its two-year rate. Still, this projection is noteworthy and indicates the market is forecasting success for its products and services.
Adjusted operating margin
Although NeoGenomics broke even this quarter from an operational perspective, it has generally struggled over a longer time period. Its expensive cost structure has contributed to an average adjusted operating margin of negative 7.3% over the last five years. Unprofitable healthcare companies warrant extra scrutiny because they can be vulnerable when conditions deteriorate. It’s hard to be confident the business can endure a full cycle.
On the positive side, NeoGenomics’s adjusted operating margin rose by 23.2 percentage points over the last five years, as its revenue growth provided operating leverage. Its more recent performance shows that trajectory remains intact, with its margin also increasing by 3.3 percentage points on a two-year basis.
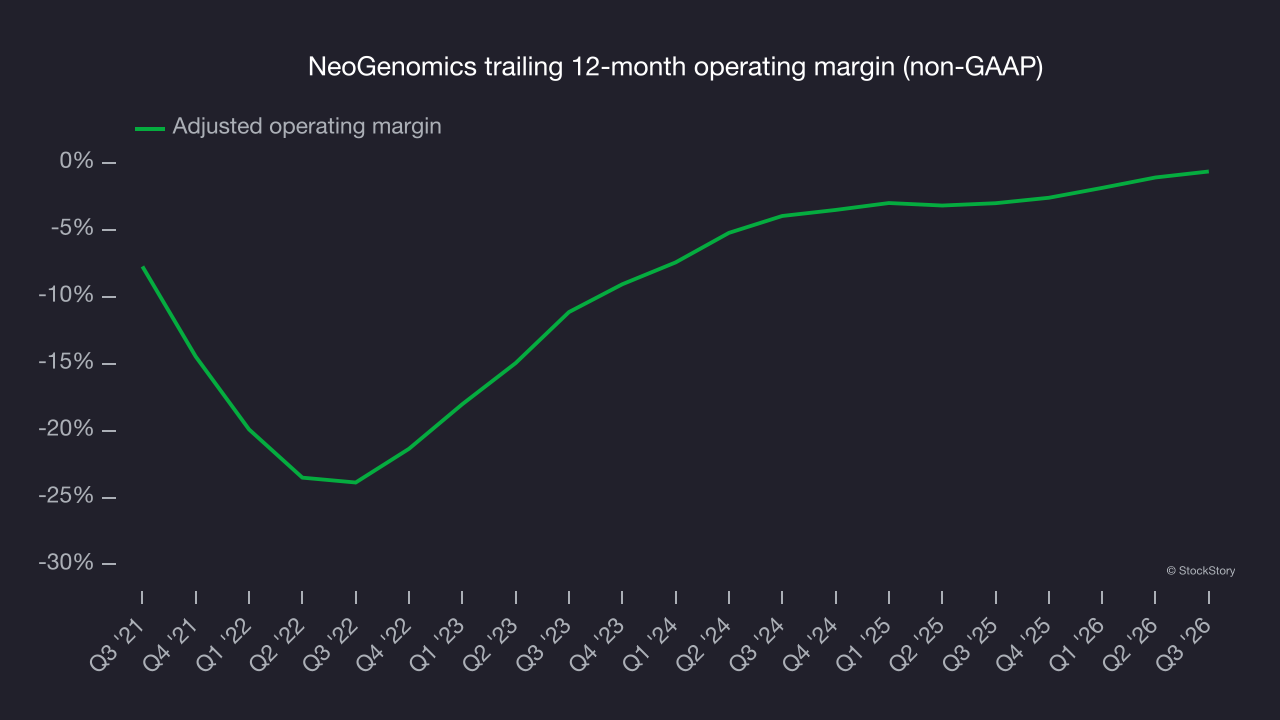
In Q3, NeoGenomics’s breakeven margin was 0.4%, up 1.7 percentage points year on year. This increase was a positive development and shows it was more efficient.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
NeoGenomics’s EPS grew at an 80.2% compounded annual growth rate over the last five years, higher than its 10.2% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
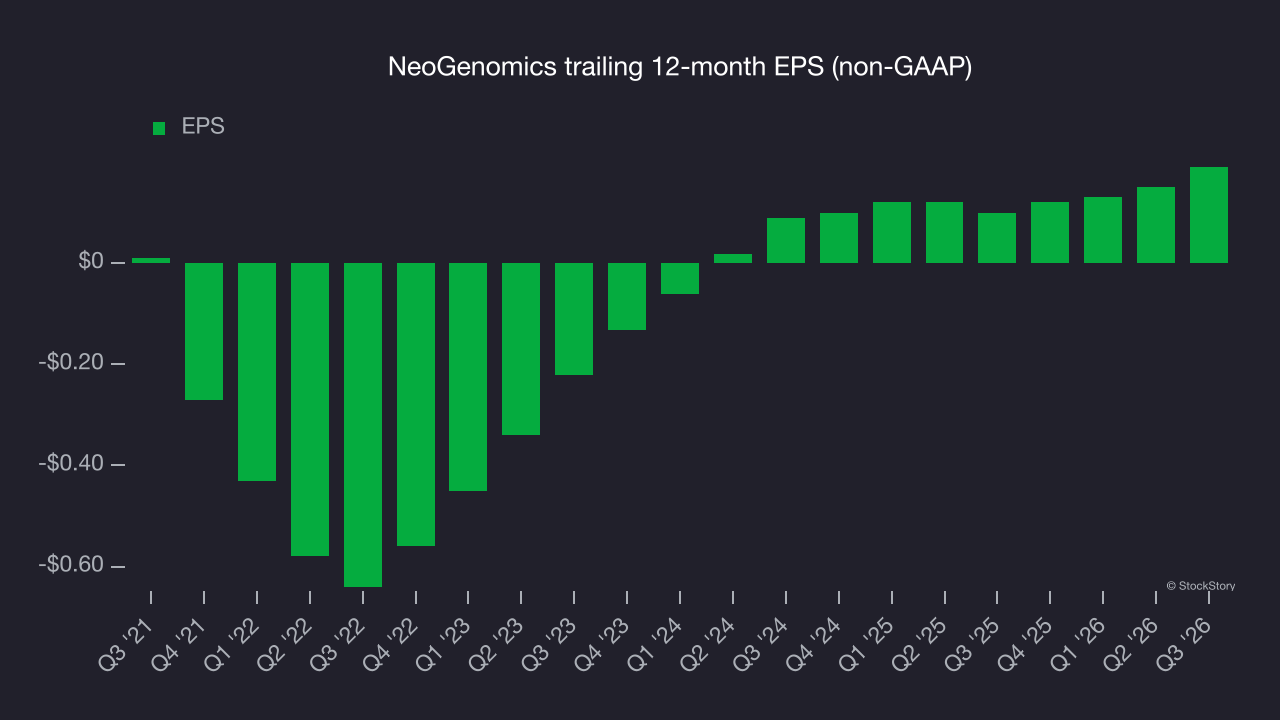
A closer look at NeoGenomics’s earnings helps explain its performance. NeoGenomics’s adjusted operating margin expanded by 23.2 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, NeoGenomics reported adjusted EPS of $0.07, up from $0.03 in the same quarter last year. This comfortably beat analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects NeoGenomics’s full-year EPS to grow 61.4% from $0.19 to $0.31, according to S&P.
Key takeaways from NeoGenomics’s Q3 results
NeoGenomics delivered a solid quarter, beating analysts’ consensus EPS estimates and setting full-year EPS guidance well above Wall Street’s consensus. Shares remained flat at $18.09 immediately after the release.
NeoGenomics may have had a good quarter, but that alone doesn’t determine whether the stock is a buy. The latest quarter is only one part of assessing longer-term business quality. Quality, when combined with valuation, can help determine if the stock is a buy. For more on NeoGenomics, read the full research report here (it’s free).