
Higher education company Laureate Education (NASDAQ: LAUR) beat Wall Street’s revenue expectations in Q3 2026, with revenue up 21.2% year on year to $485.1 million. The company expects the full year’s revenue to be around $1.93 billion, close to analysts’ consensus estimates. Its GAAP profit of $0.73 per share was 60.5% above analysts’ consensus estimates.
For more on Laureate Education, read our free full research report.
Laureate Education (LAUR) Q3 2026 highlights:
- Revenue $485.1 million vs S&P analysts’ consensus estimates of $481.8 million (21.2% year-on-year growth, 0.7% beat)
- EPS (GAAP) $0.73 vs analysts’ consensus estimates of $0.45 (60.5% beat)
- Adjusted EBITDA $146.8 million vs analysts’ consensus estimates of $135.5 million (30.3% margin, 8.4% beat)
- Revenue guidance The company reconfirmed its revenue guidance for the full year of $1.93 billion at the midpoint
- EBITDA guidance $596 million at the midpoint for the full year, in line with analysts’ consensus estimates
- Operating margin 24.6%, up from 17.9% in the same quarter last year
- Free cash flow margin 25.5%, down from 30.7% in the same quarter last year
- Enrolled students increased by 28,200 year on year
- Market capitalization $5.01 billion
Eilif Serck-Hanssen, President and Chief Executive Officer, said, “We are pleased to report strong new enrollment intakes in both of our markets. The primary intake in Mexico included a very successful launch of our new campus in Puebla, as well as further growth in existing campuses. During the secondary intake in Peru, we continued to leverage our fully online capabilities to meet growing demand for working adults as that market scales.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Laureate Education grew its revenue at a 12.2% annual rate. Though this growth is acceptable on an absolute basis, revenue growth alone is not enough for the consumer discretionary sector, which can display significant earnings volatility. This means the bar for the sector is particularly high, reflecting the non-essential and hit-driven nature of the products and services offered. Additionally, the five-year growth period starts around Covid, when revenue was depressed before rebounding.
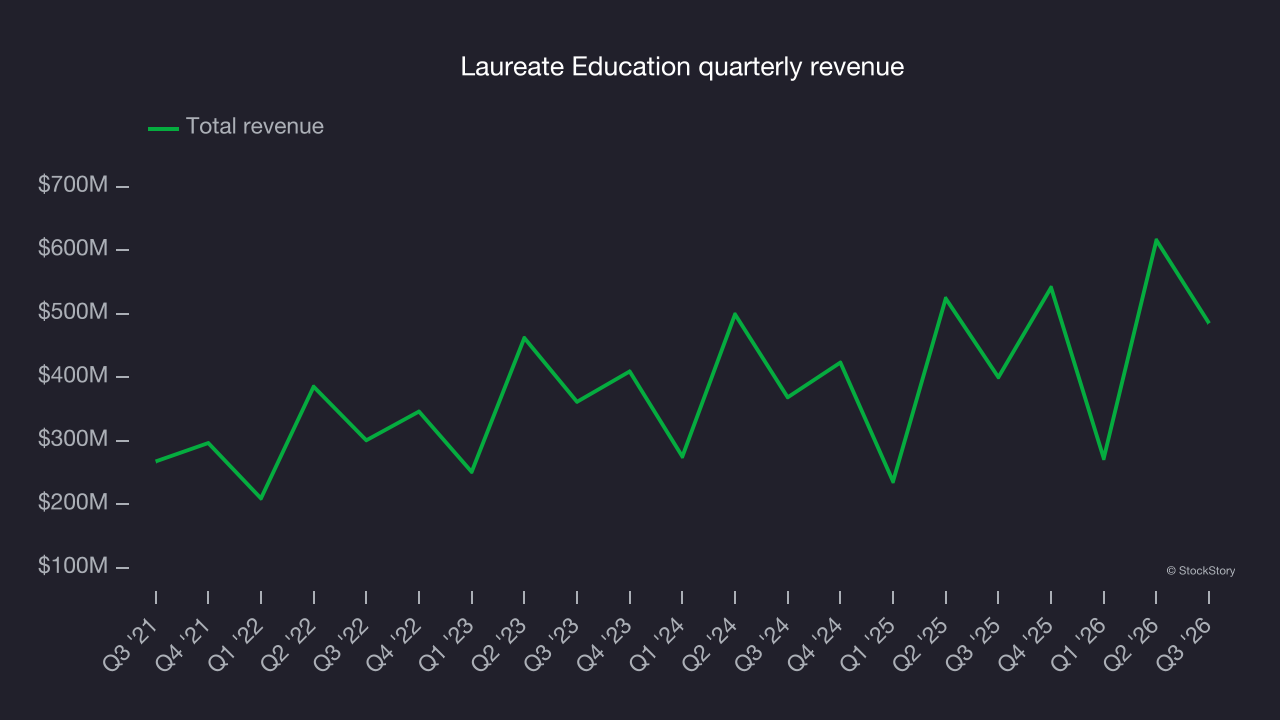
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. Laureate Education’s recent performance shows its demand has slowed as its annualized revenue growth of 11.1% over the last two years was below its five-year trend. Slowing revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 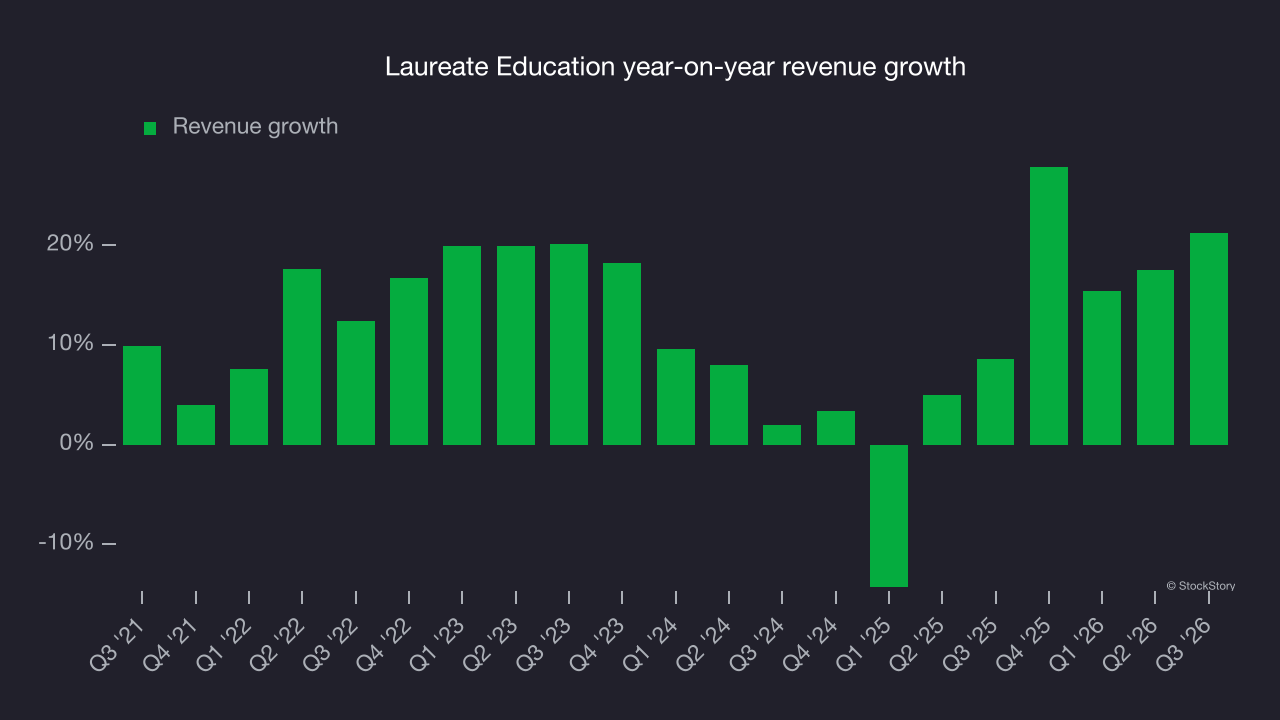
The number of enrolled students, which reached 539,600 in the latest quarter, helps explain the company’s revenue dynamics. Over the last two years, Laureate Education’s enrolled students averaged 5.6% year-on-year growth. Revenue growth outpaced enrollment growth during the same period, indicating that the company’s monetization has risen. 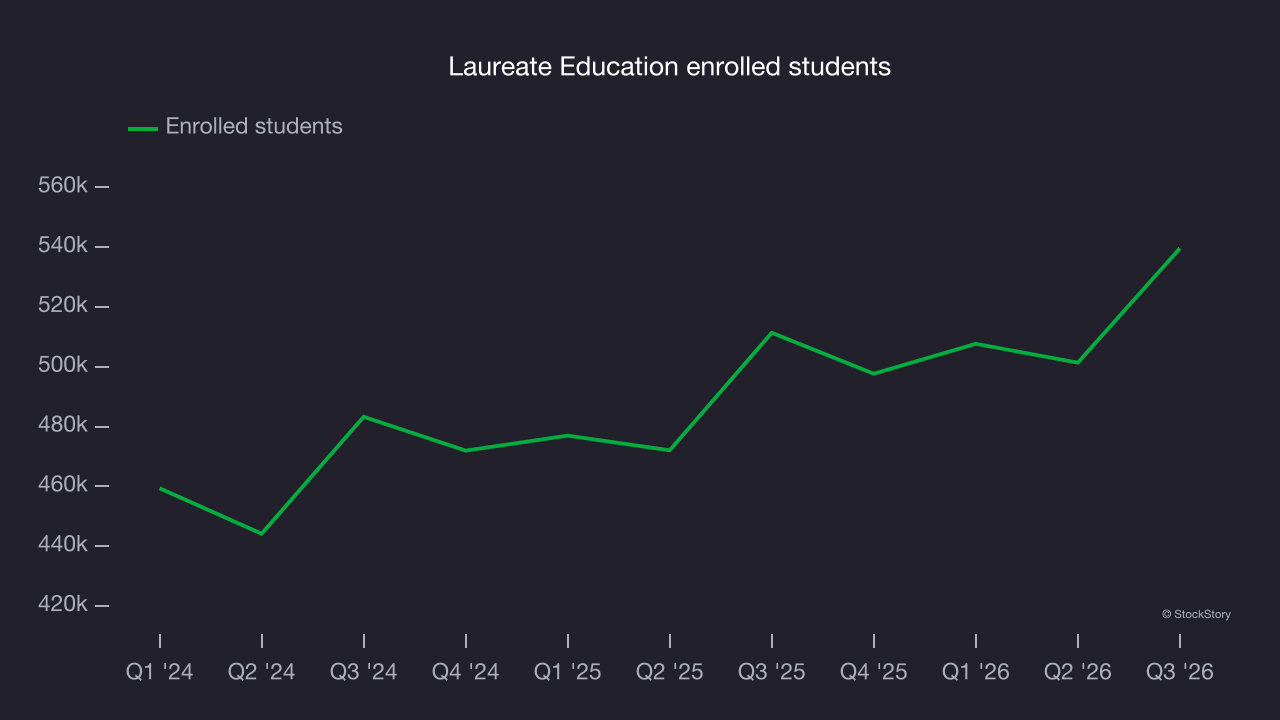
This quarter, Laureate Education reported strong year-on-year revenue growth of 21.2%, and its $485.1 million of revenue topped Wall Street’s consensus estimates by 0.7%.
Looking ahead, sell-side analysts expect revenue to grow 3.9% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is uninspiring and implies its products and services will face some demand headwinds.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Laureate Education’s operating margin has risen over the last 12 months and averaged 24.9% over the last two years. The company’s improved efficiency is a positive, but its suboptimal cost structure means profitability remains poor for a consumer discretionary business.
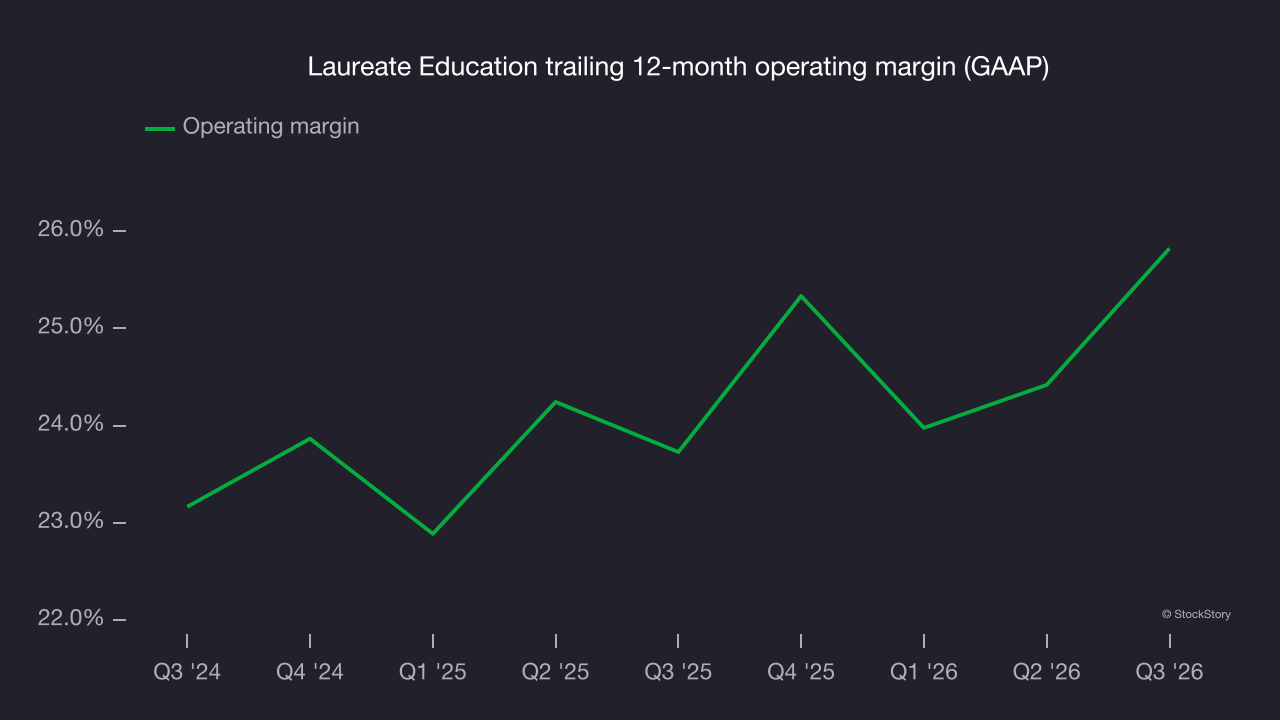
This quarter, Laureate Education generated an operating margin of 24.6%, up 6.7 percentage points year on year. The increase was a positive sign of improved efficiency.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Laureate Education’s flat EPS over the last five years was below its 12.2% annualized revenue growth. The difference stemmed from higher interest expenses or taxes, as the company improved its operating margin and repurchased its shares during this time.
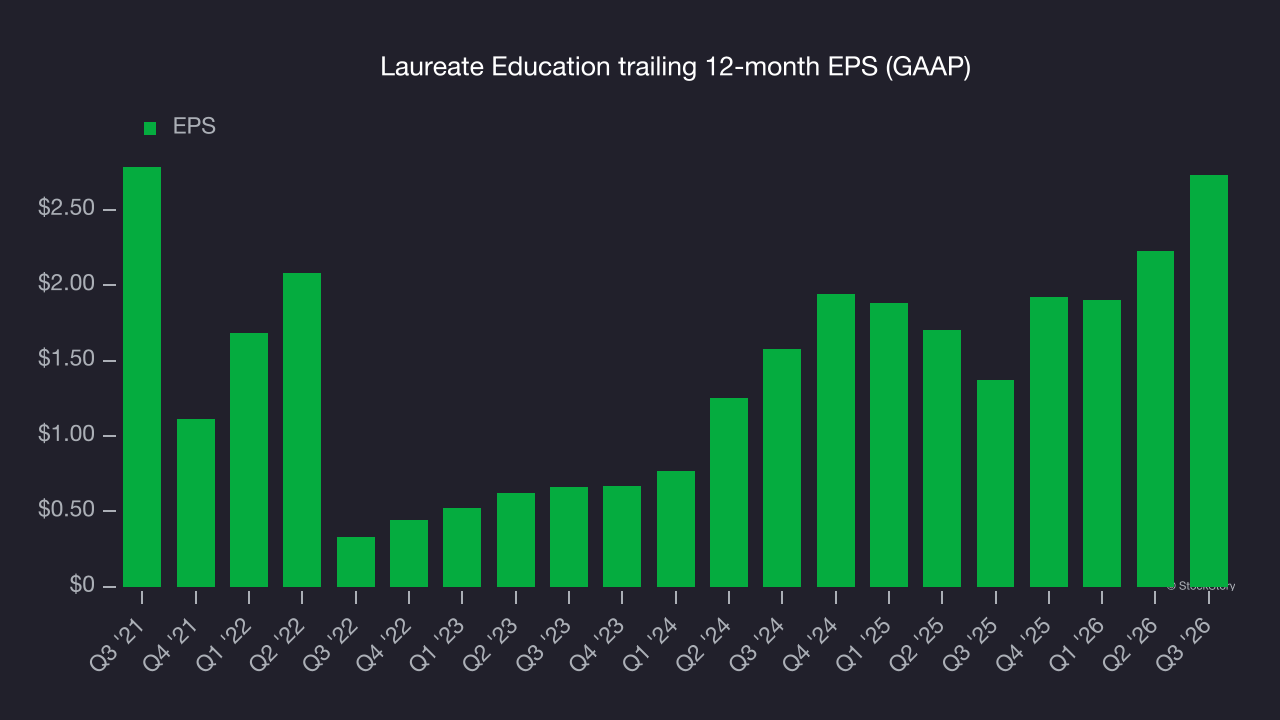
In Q3, Laureate Education reported EPS of $0.73, up from $0.23 in the same quarter last year. EPS came in well above analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects Laureate Education’s full-year EPS to shrink by 14.1% from $2.73 to $2.35, according to S&P.
Key takeaways from Laureate Education’s Q3 results
Laureate Education’s EPS and EBITDA both topped Wall Street’s consensus estimates, giving its Q3 results some clear positives. Shares rose 2.6% to $37.32 immediately after the release.
Laureate Education reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. The latest quarter is only one piece of the longer-term business quality picture. Quality, when combined with valuation, can help determine if the stock is a buy. For more on Laureate Education, read the full research report here (it’s free).