What a fantastic six months it’s been for GoodRx. Shares of the company have skyrocketed 58.7%, hitting $3.29. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy GoodRx, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think GoodRx Will Underperform?
We’re happy investors have made money, but we’re passing on GoodRx for now. Here are three reasons why there are better opportunities than GDRX, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
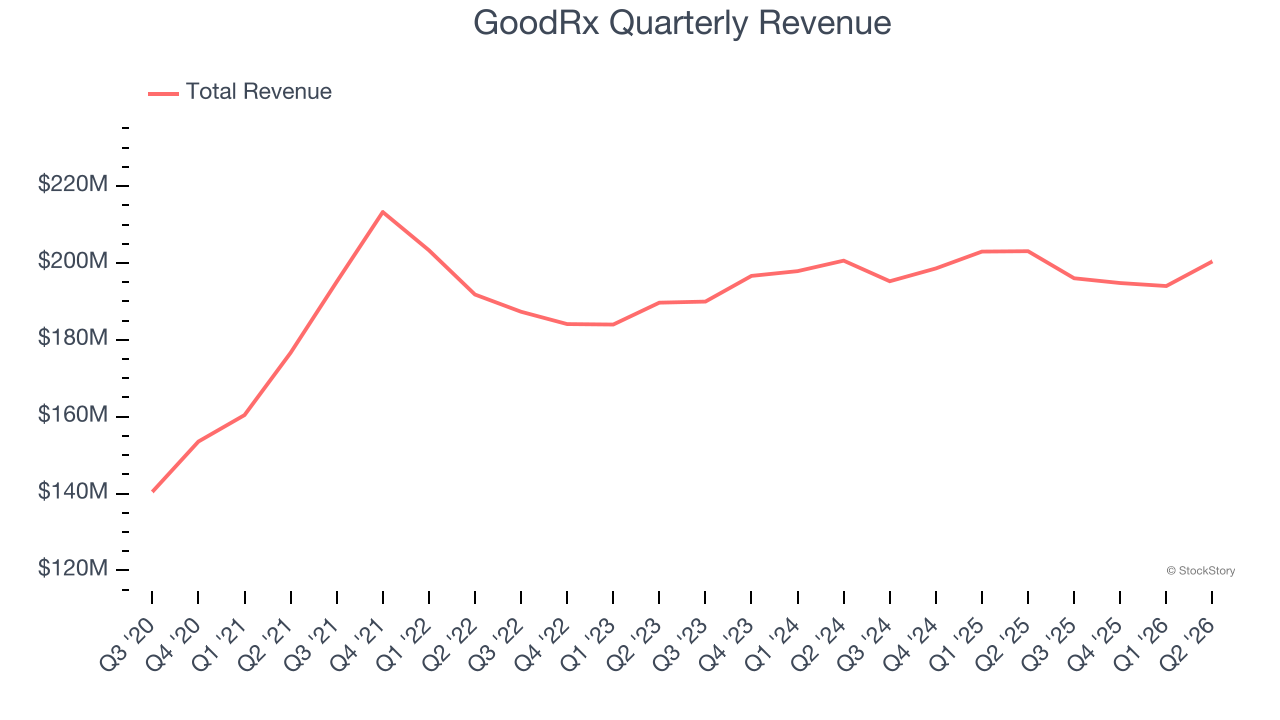
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Unfortunately, GoodRx’s 4.5% annualized revenue growth over the last five years was mediocre. This was below our standard for the healthcare sector.
2. Fewer Distribution Channels Limit Its Ceiling
Larger companies benefit from economies of scale, where fixed costs like infrastructure, technology, and administration are spread over a higher volume of goods or services, reducing the cost per unit. Scale can also lead to bargaining power with suppliers, greater brand recognition, and more investment firepower. A virtuous cycle can ensue if a scaled company plays its cards right.
With just $785.2 million in revenue over the past 12 months, GoodRx is a small company in an industry where scale matters. This makes it difficult to build trust with customers because healthcare is heavily regulated, complex, and resource-intensive.
3. Previous Growth Initiatives Haven’t Paid Off Yet
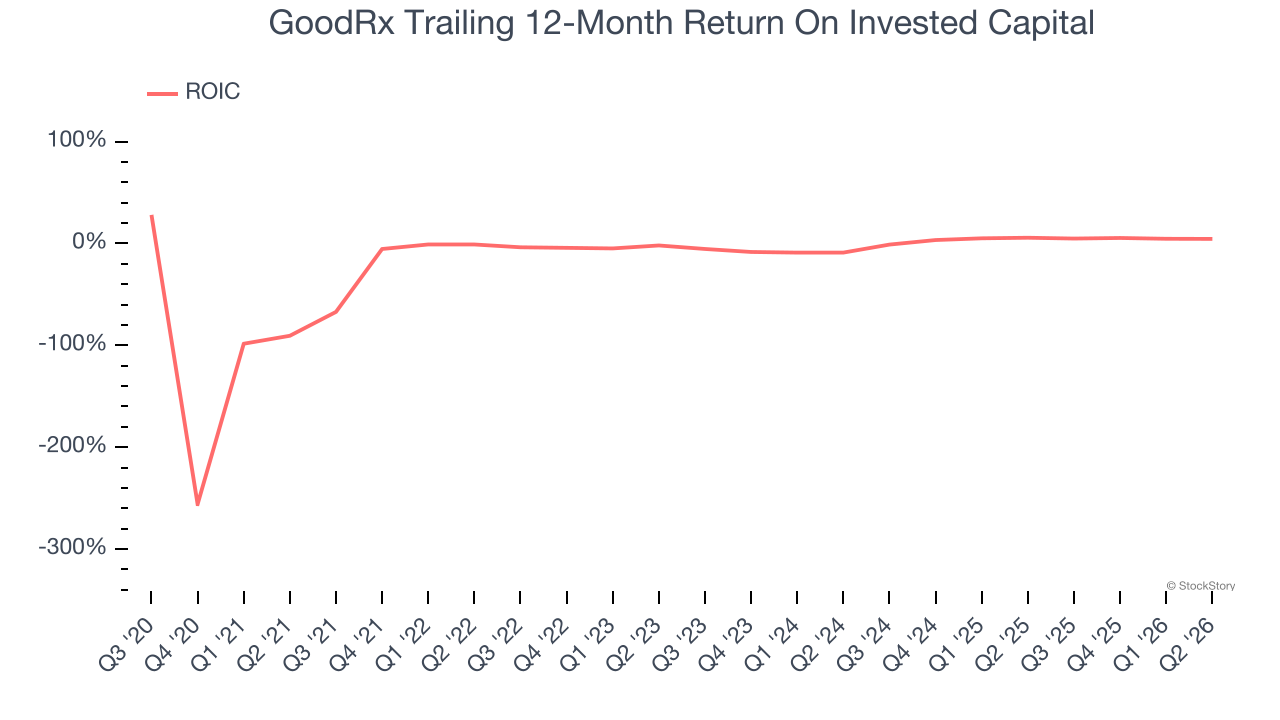
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
GoodRx’s five-year average ROIC was negative 0.4%, meaning management lost money while trying to expand the business. Investors are likely hoping for a change soon.
Final Judgment
GoodRx doesn’t pass our quality test. After the recent rally, the stock trades at 9.9× forward P/E (or $3.29 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better stocks to buy right now. Let us point you toward our favorite semiconductor picks and shovels play.
Stocks We Like More Than GoodRx
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.