Water management manufacturer Watts Water (NYSE: WTS) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue up 19% year on year to $728 million. Its non-GAAP profit of $3.40 per share was 8.1% above analysts’ consensus estimates.
For more on Watts Water Technologies, read our free full research report.
Watts Water Technologies (WTS) Q3 2026 highlights:
- Revenue $728 million vs S&P analysts’ consensus estimates of $692.2 million (19% year-on-year growth, 5.2% beat)
- Adjusted EPS $3.40 vs S&P analysts’ consensus estimates of $3.14 (8.1% beat)
- Operating margin 26.2%, up from 18.2% in the same quarter last year
- Free cash flow margin 18.1%, similar to the same quarter last year
- Organic revenue rose 12.2% year on year (beat)
- Market capitalization $12.03 billion
Chief Executive Officer Robert J. Pagano Jr. said, “Strong execution across our businesses drove double-digit organic growth and significant adjusted operating margin expansion in the third quarter. These results reflect the strength of our diversified portfolio and our ability to capitalize on attractive growth opportunities across our markets. Demand remained particularly strong in data center applications, reinforcing our confidence in the long-term potential of this market. We are again raising our full year sales and margin guidance, given our strong year-to-date performance and expectations for the remainder of the year. While higher interest rates and ongoing market uncertainty continue to weigh on new construction markets, our momentum in data center sales and our strong price performance to date are supporting our outlook. Looking ahead, we plan to continue to build on our competitive strengths through customer-driven innovation, digital capabilities and the One Watts Performance System, reinforcing our market leadership and supporting long-term, profitable growth. I want to thank the global Watts team for their commitment to serving our customers, advancing our strategy and delivering results.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Watts Water Technologies’s revenue grew at a solid 9.9% compounded annual growth rate over the last five years. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
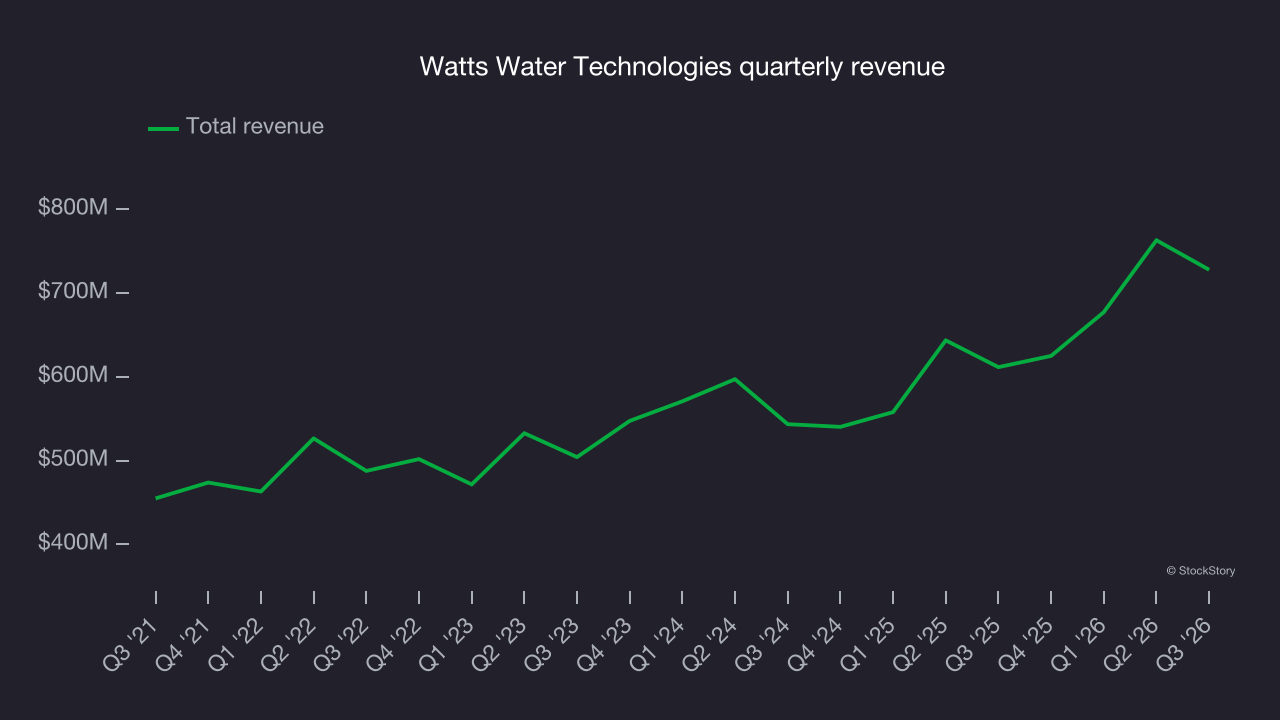
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Watts Water Technologies’s annualized revenue growth of 11.2% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 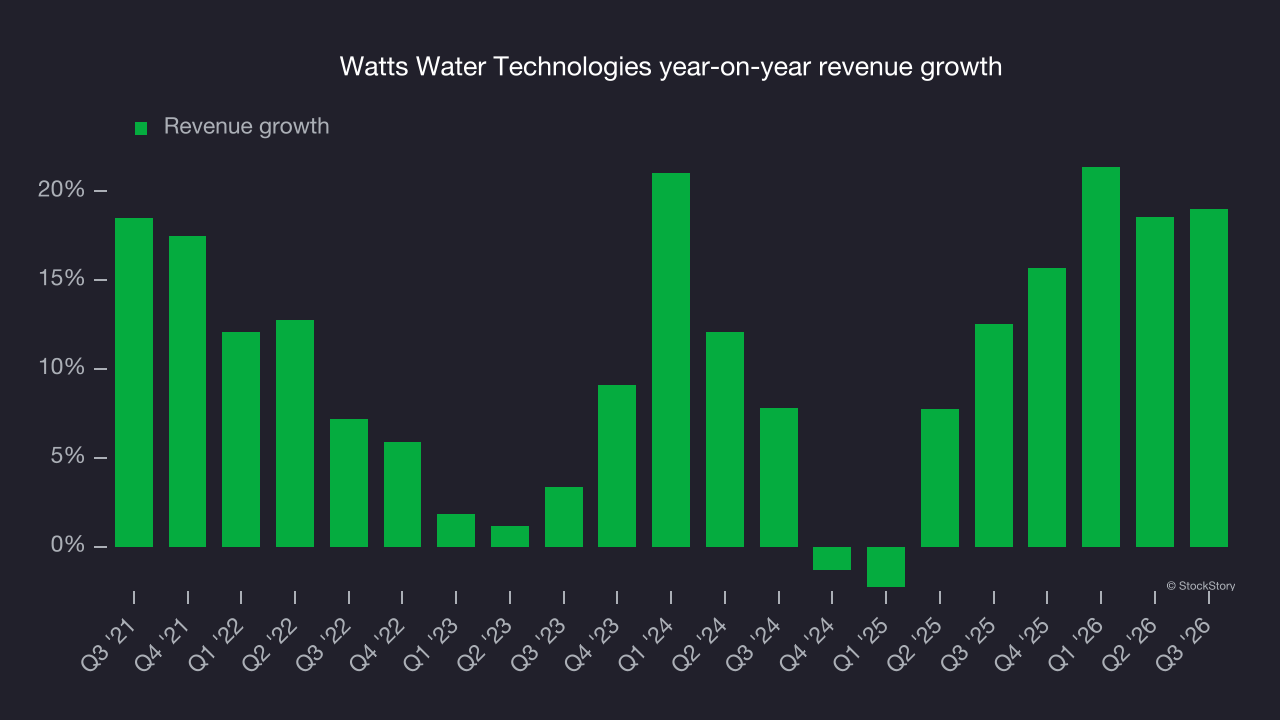
A closer look at the company’s revenue dynamics starts with its organic revenue, which strips out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, Watts Water Technologies’s organic revenue averaged 6.5% year-on-year growth. Total revenue growth outpaced organic growth over that period, indicating that a combination of acquisitions and foreign exchange rates boosted its headline results. 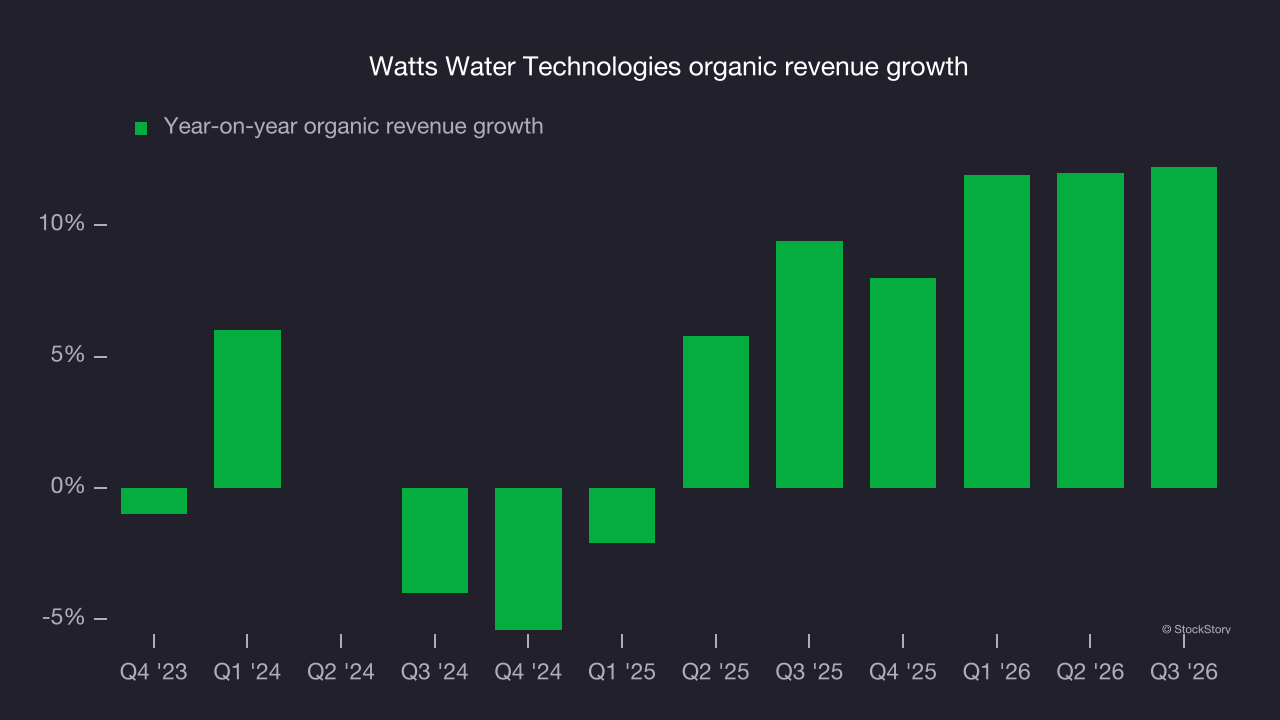
This quarter, Watts Water Technologies reported year-on-year revenue growth of 19%, and its $728 million of revenue exceeded Wall Street’s consensus estimates by 5.2%.
Looking ahead, sell-side analysts expect revenue to grow 5.5% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and implies its products and services will see some demand headwinds. At least the company is tracking well in other measures of financial health.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Watts Water Technologies has performed well over the last five years. It demonstrated strong profitability for an industrials business, with an average operating margin of 18%. This result is unsurprising given its favorable gross margin baseline.
Analyzing the trend in its profitability, Watts Water Technologies’s operating margin rose by 5.3 percentage points over the last five years, as its revenue growth provided operating leverage.
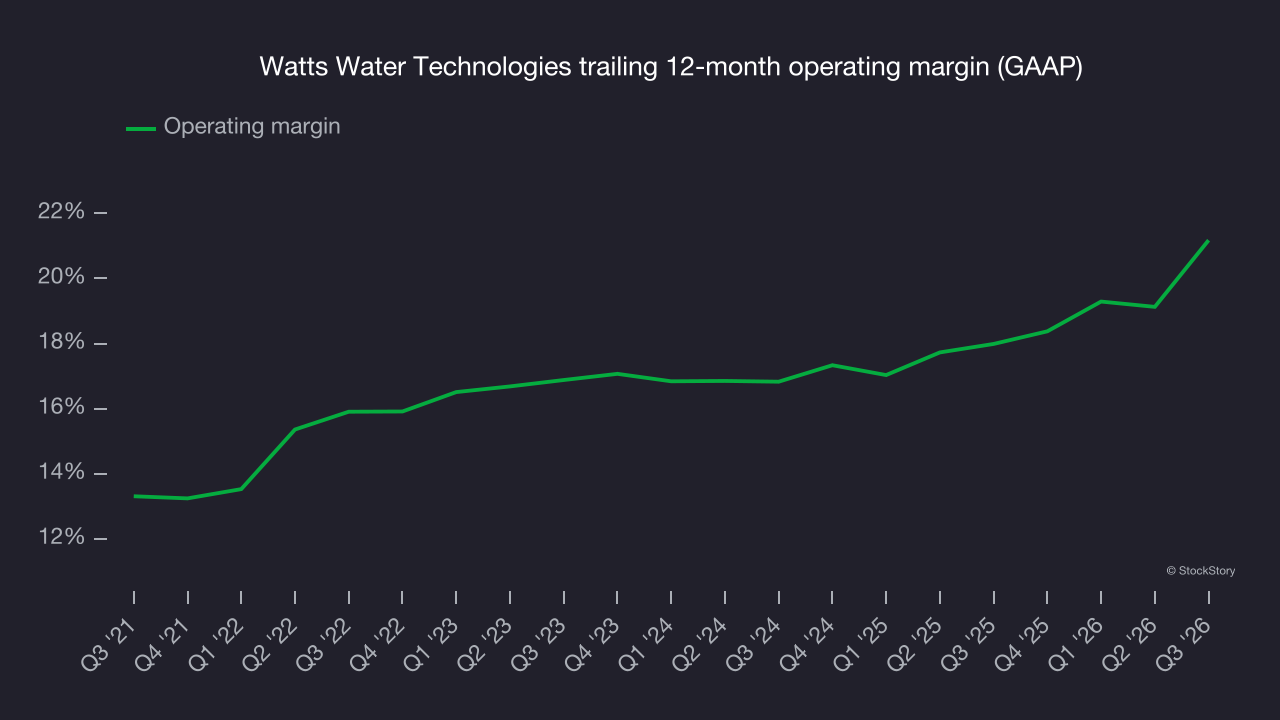
In Q3, Watts Water Technologies generated an operating margin of 26.2%, up 8 percentage points year on year. The increase was solid, and its operating margin rose more than its gross margin, indicating greater efficiency in expenses such as marketing, research and development and administrative overhead.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Watts Water Technologies’s EPS grew at a 19.3% compounded annual growth rate over the last five years, higher than its 9.9% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
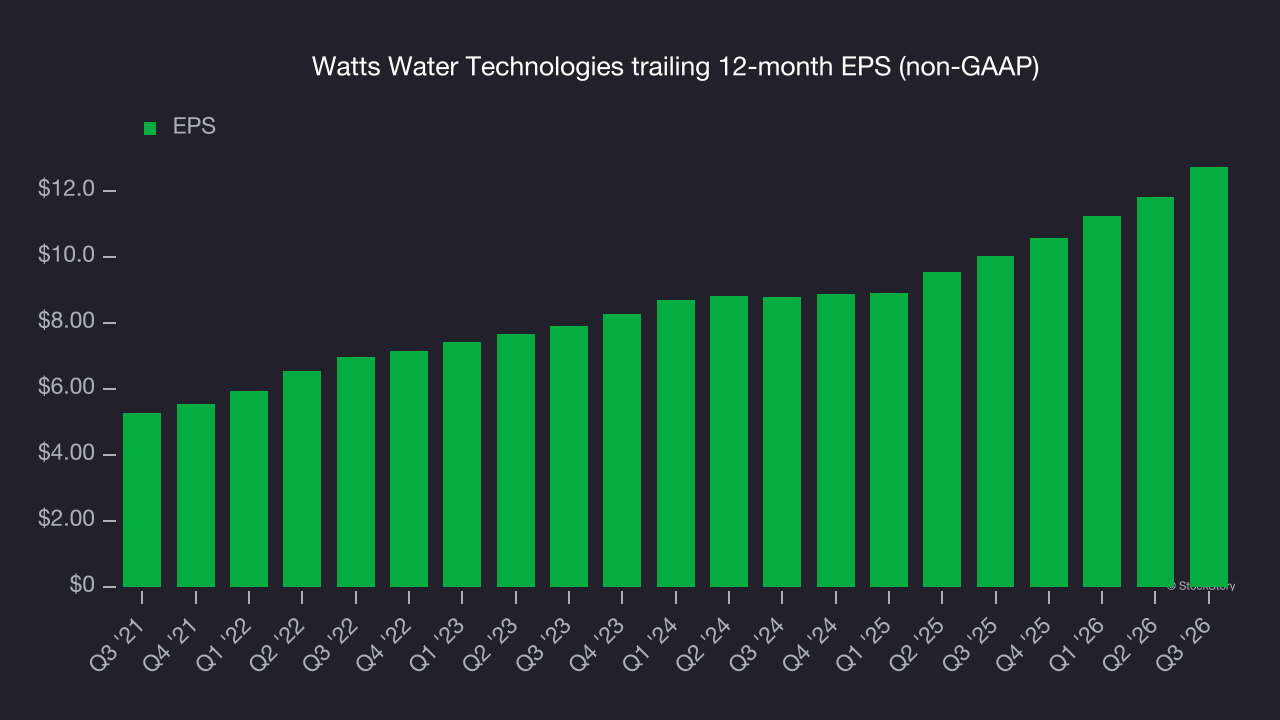
A closer look at Watts Water Technologies’s earnings helps explain the drivers of its performance. As mentioned earlier, Watts Water Technologies’s operating margin expanded by 5.3 percentage points over the last five years. On top of that, its share count shrank by 1.2%. These are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 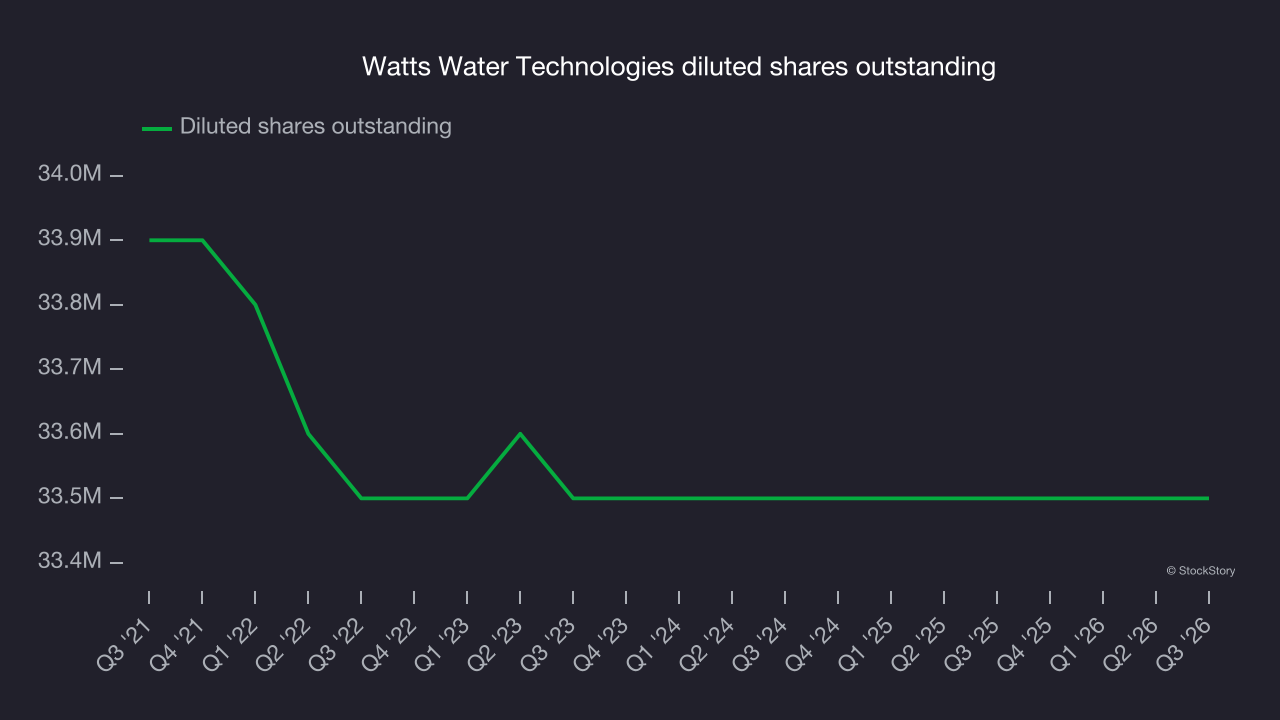
As with revenue, a shorter-term view of EPS can reveal changes in the business.
For Watts Water Technologies, its two-year annual EPS growth of 20.3% is similar to its five-year trend, implying strong and stable earnings power.
In Q3, Watts Water Technologies reported adjusted EPS of $3.40, up from $2.50 in the same quarter last year. This result beat analysts’ consensus estimates by 8.1%. Over the next 12 months, Wall Street expects Watts Water Technologies’s full-year EPS to grow 7.3% from $12.72 to $13.65, according to S&P.
Key takeaways from Watts Water Technologies’s Q3 results
Watts Water Technologies delivered a solid Q3, with organic revenue well above analysts’ consensus estimates and revenue topping Wall Street’s consensus by a wide margin. Shares remained flat at $355.40 immediately after the results.
Watts Water Technologies had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. That decision requires considering the bigger picture of valuation and business qualities as well as the latest earnings. For more on Watts Water Technologies, read our full research report here (it’s free).