Engineered components manufacturer for critical industries ITT Inc. (NYSE: ITT) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue up 44.2% year on year to $1.44 billion. Its non-GAAP profit of $2.26 per share was 8.6% above analysts’ consensus estimates.
For more on ITT, read our free full research report.
ITT (ITT) Q3 2026 highlights:
- Revenue $1.44 billion vs S&P analysts’ consensus estimates of $1.42 billion (44.2% year-on-year growth, 1.7% beat)
- Adjusted EPS $2.26 vs S&P analysts’ consensus estimates of $2.08 (8.6% beat)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $8.58 at the midpoint, a 4.4% increase
- Operating margin 15.7%, down from 18% in the same quarter last year
- Free cash flow margin 20%, up from 15.4% in the same quarter last year
- Organic revenue rose 7.6% year on year (beat)
- Market capitalization $18.34 billion
“ITTers around the world delivered yet another strong quarter as they executed relentlessly across the business. Our teams continue to win in the market, whilst our acquisitions are enhancing the strength of our portfolio and compounding ITT's long-term value creation. At SPX FLOW, we are executing with discipline and speed, delivering high-single-digit growth and capturing cost synergies ahead of schedule. We are unlocking revenue synergies as we leverage our expanded capabilities, global reach and customer relationships. And with a healthy backlog and orders momentum, we are well-positioned to continue driving growth and margin expansion next year whilst building an even stronger ITT,” said ITT’s Chief Executive Officer and President Luca Savi.
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long term. ITT’s 13.2% annualized revenue growth over the last five years was strong. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
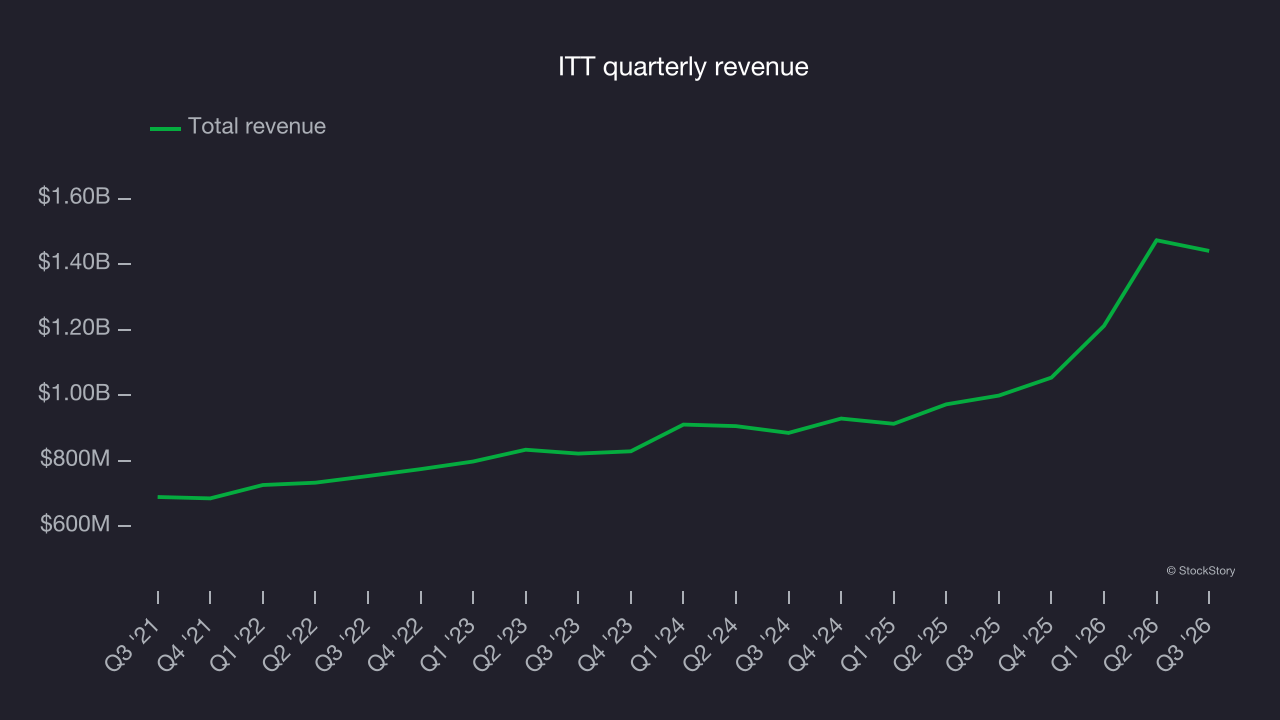
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. ITT’s annualized revenue growth of 21.1% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 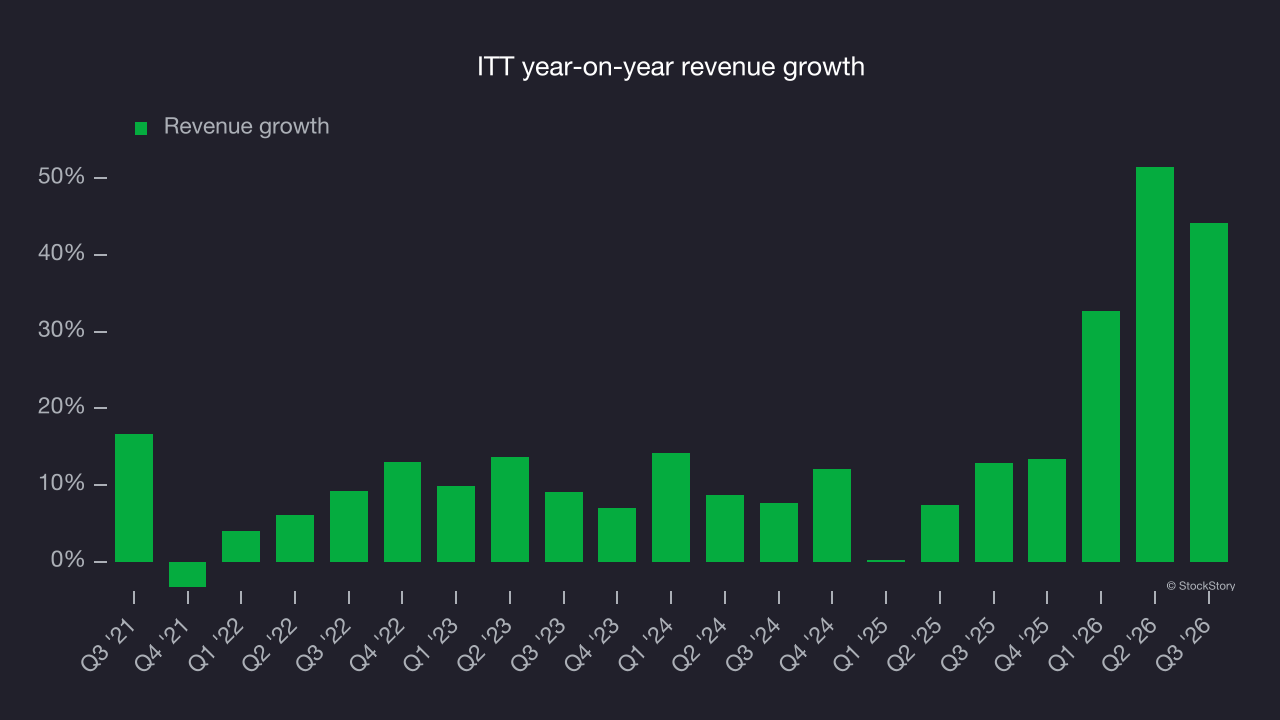
Organic revenue helps clarify the company’s revenue dynamics by stripping out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, ITT’s organic revenue averaged 7% year-on-year growth. Total revenue growth outpaced organic growth over that period, indicating that a combination of acquisitions and foreign exchange rates boosted its headline results. 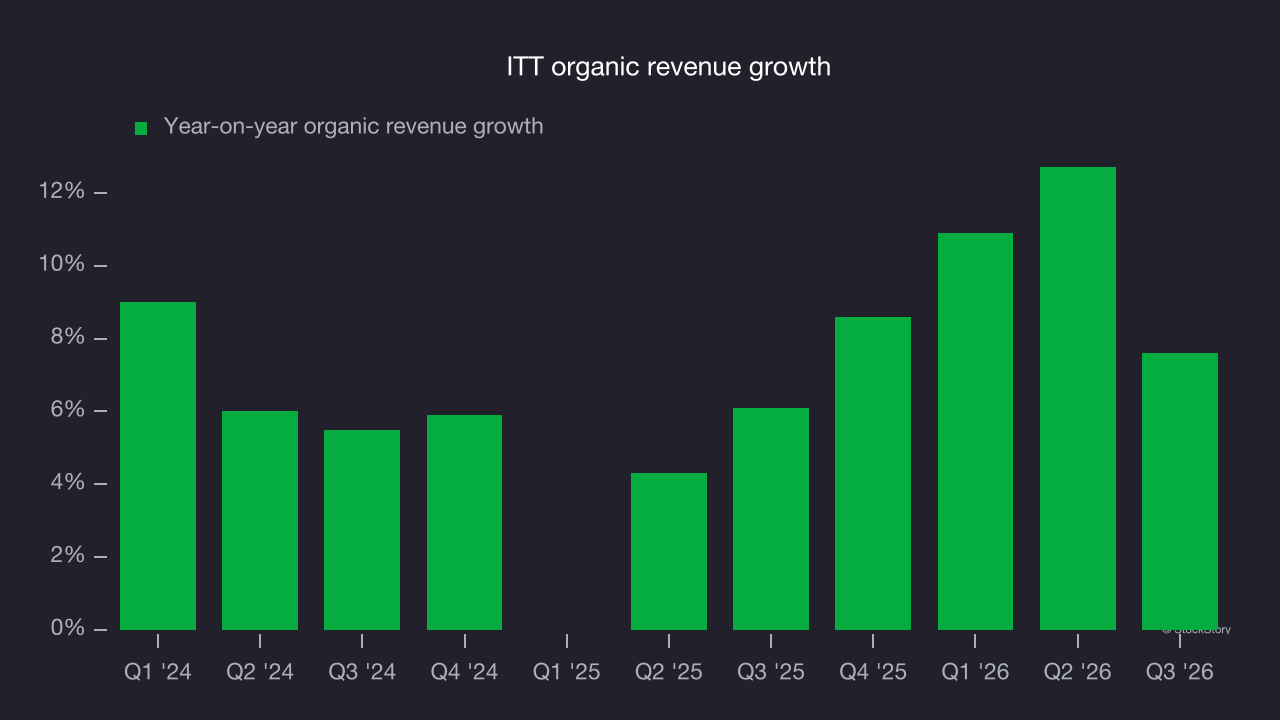
This quarter, ITT reported year-on-year revenue growth of 44.2%, and its $1.44 billion in revenue beat Wall Street’s consensus estimates by 1.7%.
Looking ahead, sell-side analysts expect revenue to grow 14.3% over the next 12 months, according to S&P, a deceleration versus the last two years. Despite the slowdown, this projection is noteworthy and implies the market is forecasting success for its products and services.
Operating margin
Operating margin is one of the best measures of profitability because it shows how much money a company earns after procuring and manufacturing its products, marketing and selling them and, most importantly, keeping them relevant through research and development.
ITT’s operating margin has more or less stayed the same over the last 12 months, averaging 16.2% over the last five years. This profitability was high for an industrials business thanks to its efficient cost structure and economies of scale. Its fast historical revenue growth and healthy gross margin also reflect these advantages, which is why all three metrics are best considered together.
Analyzing the trend in its profitability, ITT’s operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
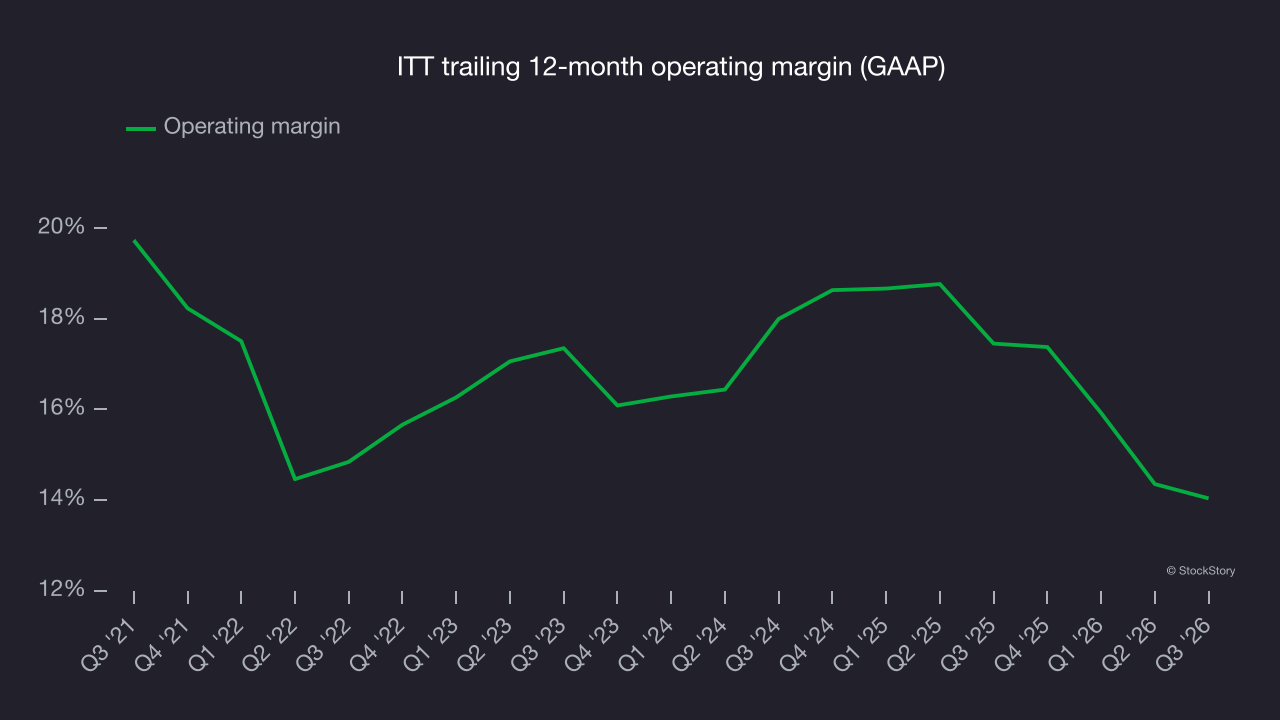
In Q3, ITT generated an operating margin of 15.7%, down 2.3 percentage points year on year. By contrast, its revenue and gross margin rose, suggesting it was less efficient because operating expenses such as marketing, research and development and administrative overhead grew faster than revenue.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
ITT’s EPS grew at a 15.4% compounded annual growth rate over the last five years, higher than its 13.2% annualized revenue growth. However, that comparison warrants caution because its operating margin didn’t improve and it didn’t repurchase its shares, meaning the difference came from reduced interest expenses or taxes.
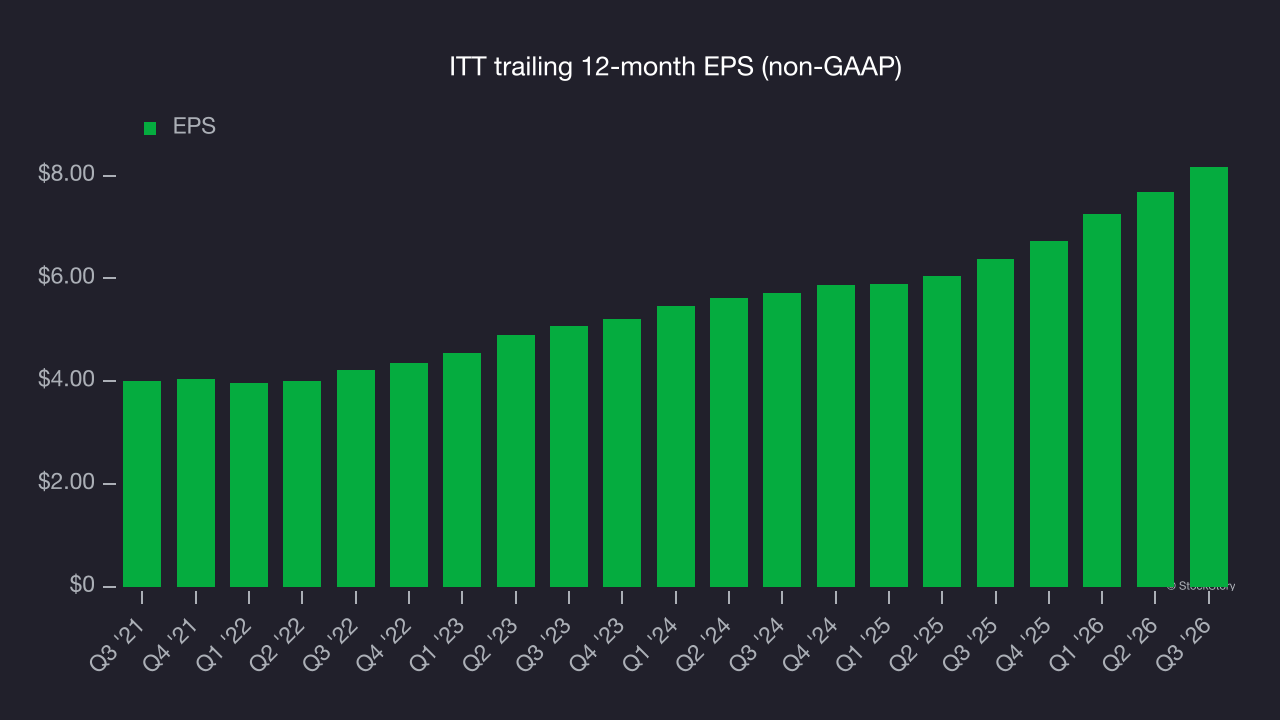
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For ITT, its two-year annual EPS growth of 19.6% was higher than its five-year trend. That acceleration is a positive, particularly given the already high base.
In Q3, ITT reported adjusted EPS of $2.26, up from $1.78 in the same quarter last year. This result beat analysts’ consensus estimates by 8.6%. Over the next 12 months, Wall Street expects ITT’s full-year EPS to grow 12.7% from $8.17 to $9.21, according to S&P.
Key takeaways from ITT’s Q3 results
ITT’s full-year EPS guidance came in well above analysts’ consensus estimates, and revenue also topped Wall Street’s consensus. Those positives made this a solid quarter overall. Shares remained flat at $206.49 immediately after the results.
Is ITT an attractive investment opportunity at the current price? The latest quarter matters, but longer-term fundamentals and valuation are more important when deciding whether to buy the stock. For more on ITT, read our full research report here (it’s free).