
Consumer financial services company Synchrony Financial (NYSE: SYF) met Wall Street’s revenue expectations in Q3 2026, but sales were flat year on year at $3.82 billion. Its GAAP profit of $2.68 per share was 10.5% above analysts’ consensus estimates.
Is now the time to buy Synchrony Financial? Find out by accessing our full research report, it’s free.
Synchrony Financial (SYF) Q3 2026 Highlights:
- Net Interest Income: $4.81 billion vs analyst estimates of $4.82 billion (in line)
- Net Interest Margin: 15.5% vs analyst estimates of 15.5% (3.6 basis point beat)
- Revenue: $3.82 billion vs analyst estimates of $3.80 billion (flat year on year, in line)
- Efficiency Ratio: 35.9% vs analyst estimates of 34.2% (165.8 basis point miss)
- EPS (GAAP): $2.68 vs analyst estimates of $2.42 (10.5% beat)
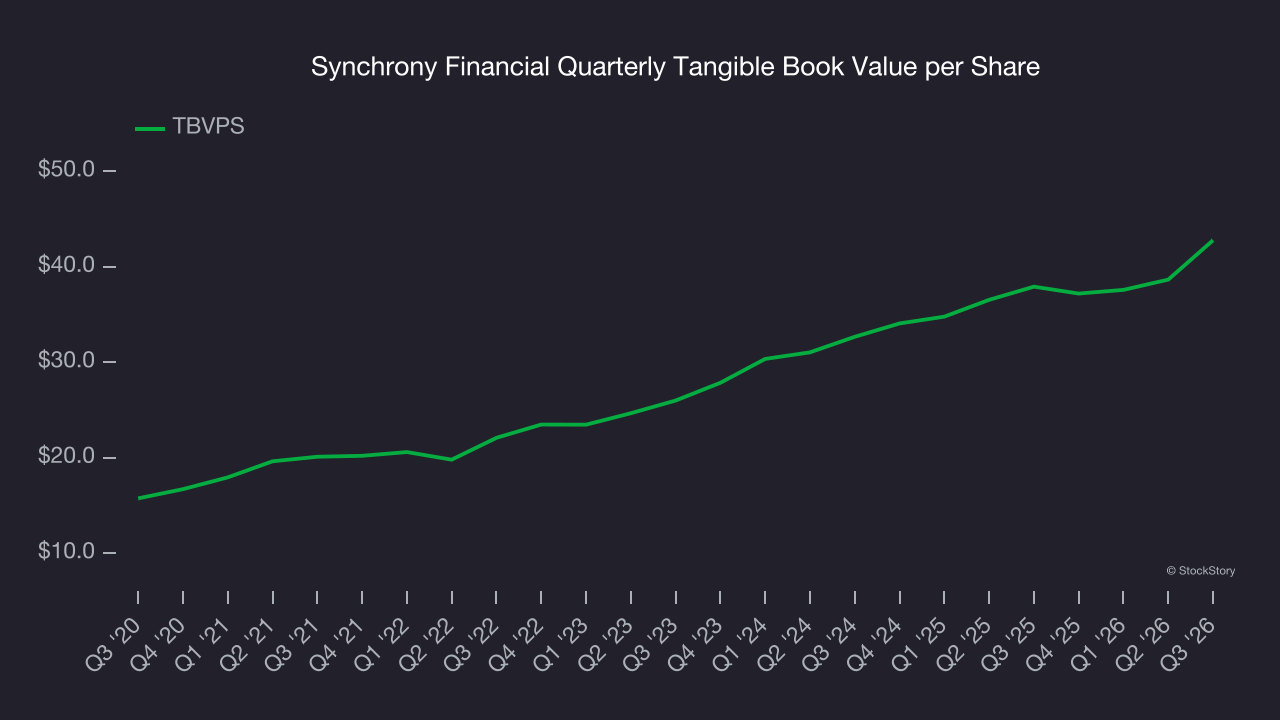
- Tangible Book Value per Share: $42.79 vs analyst estimates of $43.06 (12.8% year-on-year growth, 0.6% miss)
- Market Capitalization: $24.16 billion
Company Overview
Powering over 73 million active accounts and partnerships with major brands like Amazon, PayPal, and Lowe's, Synchrony Financial (NYSE: SYF) provides credit cards, installment loans, and banking products through partnerships with retailers, healthcare providers, and digital platforms.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Over the last five years, Synchrony Financial grew its revenue at a decent 8.2% compounded annual growth rate. Its growth was slightly above the average financials company and shows its offerings resonate with customers.
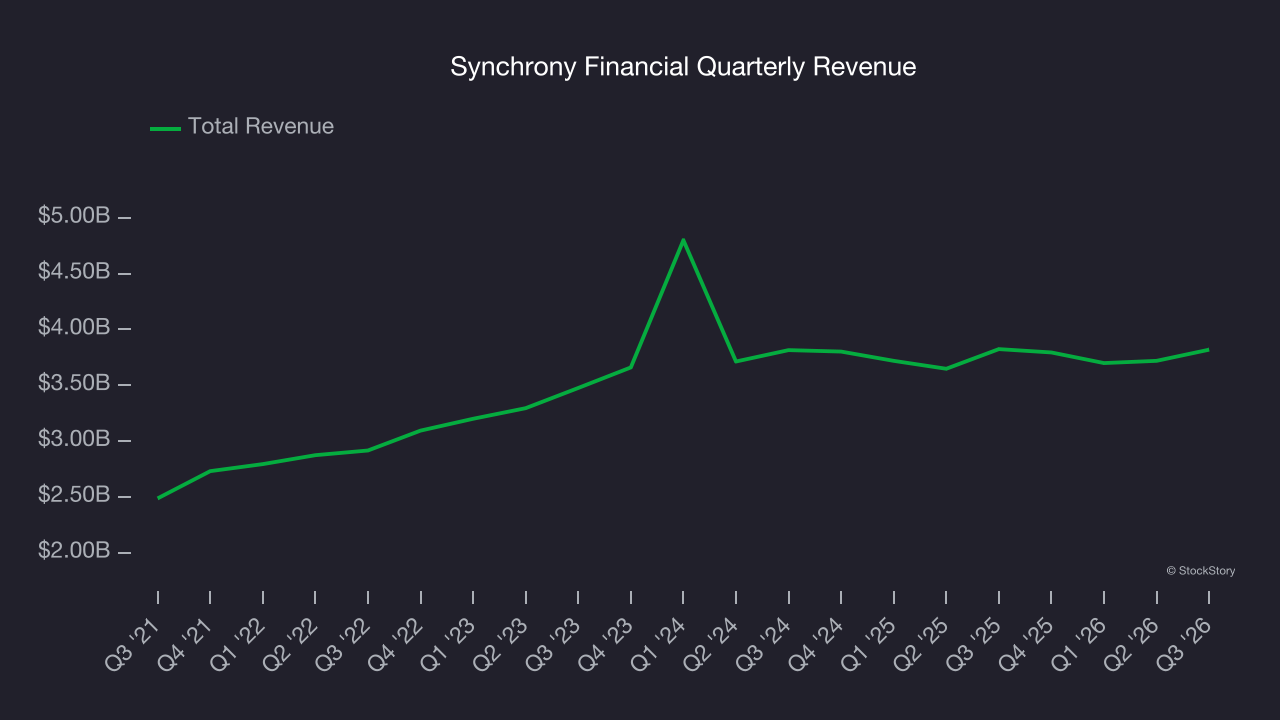
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Synchrony Financial’s recent performance marks a sharp pivot from its five-year trend as its revenue has shown annualized declines of 3% over the last two years. 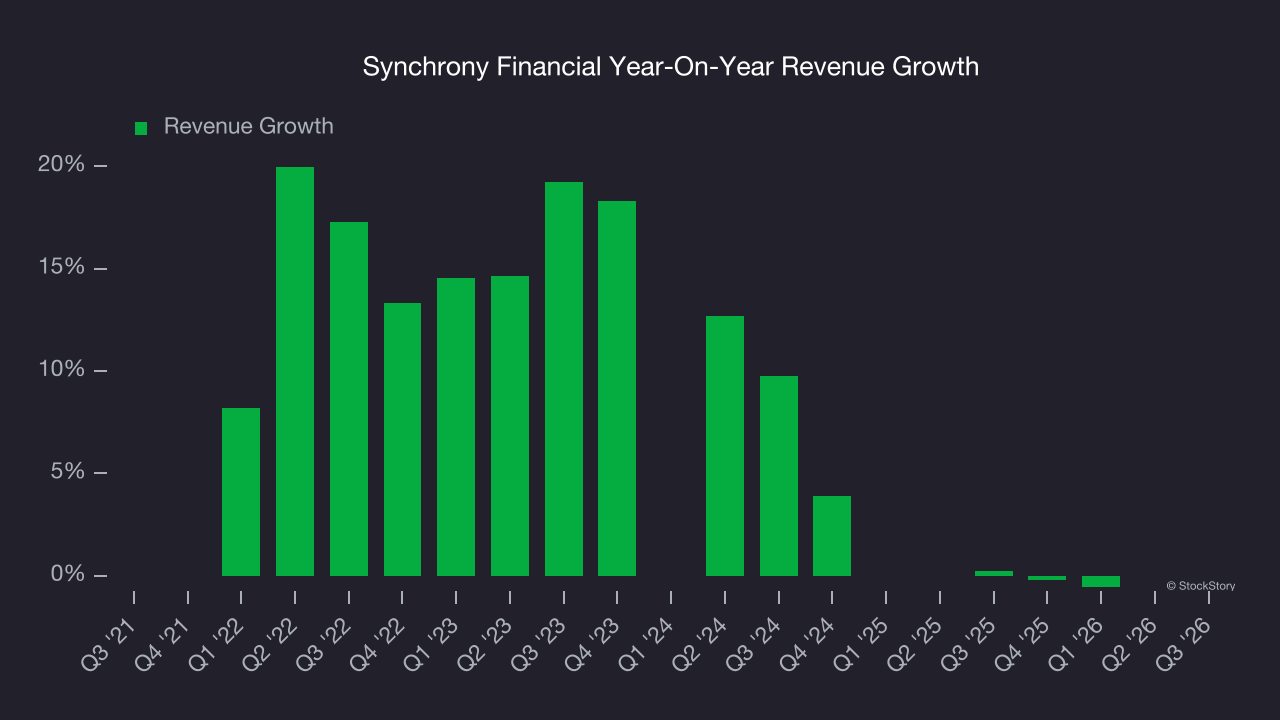 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Synchrony Financial’s $3.82 billion of revenue was flat year on year and in line with Wall Street’s estimates.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Tangible Book Value Per Share (TBVPS)
Financial firms generate earnings through diverse intermediation activities, making them fundamentally balance sheet-driven enterprises. Investors focus on balance sheet quality and consistent book value compounding when evaluating these multifaceted financial institutions.
This explains why tangible book value per share (TBVPS) is a premier metric for the sector. TBVPS provides concrete per-share net worth that investors can trust when evaluating companies with complex, multi-faceted business models. On the other hand, EPS is often distorted by the diverse nature of operations, mergers, and various accounting treatments across different business units. Book value provides clearer performance insights.
Synchrony Financial’s TBVPS grew at an excellent 16.3% annual clip over the last five years. TBVPS growth has recently decelerated a bit to 14.4% annual growth over the last two years (from $32.68 to $42.79 per share).
Tangible Book Value Per Share (TBVPS)
Diversified financial companies operate across multiple business segments, from investment banking and trading to wealth management and specialized lending. Their valuations hinge on balance sheet quality and the ability to compound shareholder equity across these diverse operations.
This is why we consider tangible book value per share (TBVPS) an important metric for the sector. TBVPS represents the real net worth per share across all business segments, providing a clear measure of shareholder equity regardless of the complexity of operations. Other (and more commonly known) per-share metrics like EPS can sometimes be murky due to the complexity of multiple business lines, M&A activity, or accounting rules that vary across different financial services segments.
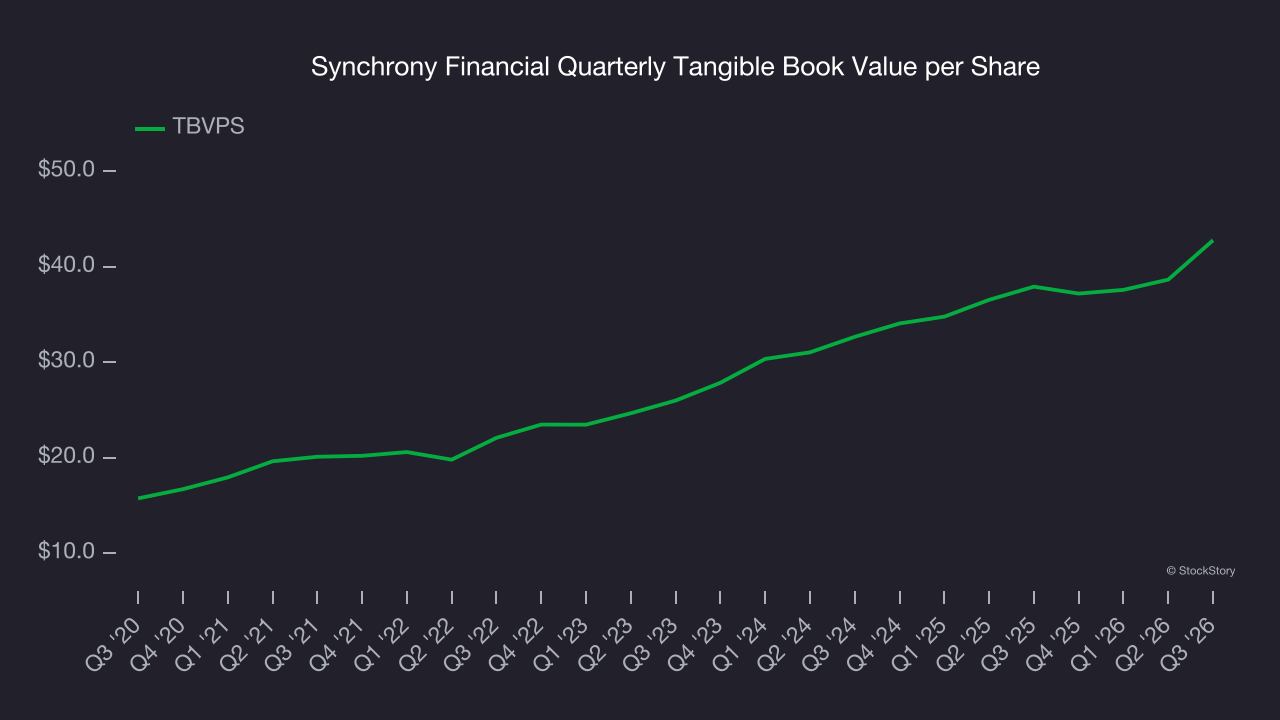
Synchrony Financial’s TBVPS grew at an excellent 16.3% annual clip over the last five years. TBVPS growth has recently decelerated a bit to 14.4% annual growth over the last two years (from $32.68 to $42.79 per share).
Key Takeaways from Synchrony Financial’s Q3 Results
We enjoyed seeing Synchrony Financial beat analysts’ efficiency ratio expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Overall, this print had some key positives. The stock remained flat at $73.63 immediately after reporting.
Is Synchrony Financial an attractive investment opportunity at the current price? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).