
Earnings results often indicate what direction a company will take in the months ahead. With Q2 behind us, let’s have a look at Expro (NYSE: XPRO) and its peers.
Oilfield services companies provide equipment, technology, and services enabling exploration and production activities, including drilling, completion, well intervention, and reservoir evaluation. Their fortunes closely track upstream capital spending cycles. Tailwinds include increased drilling activity during favorable commodity environments, demand for efficiency-enhancing technologies, and growing offshore and unconventional resource development. Headwinds include significant revenue volatility tied to oil and gas price swings and producer spending discipline. Intense competition pressures pricing and margins, while the energy transition may structurally reduce long-term demand. Workforce availability and technological disruption require continuous adaptation.
The 25 oilfield services stocks we track reported a strong Q2. As a group, revenues beat analysts’ consensus estimates by 4.6%.
In light of this news, share prices of the companies have held steady. On average, they are relatively unchanged since the latest earnings results.
Expro (NYSE: XPRO)
Operating in over 50 countries from deepwater offshore platforms to remote onshore fields, Expro (NYSE: XPRO) provides equipment and services that help oil and gas companies drill wells, measure production, and maintain well integrity.
Expro reported revenues of $393.2 million, down 7% year on year. This print exceeded analysts’ expectations by 3%. Despite the top-line beat, it was still a slower quarter for the company with a significant miss of analysts’ EPS estimates and a miss of analysts’ EBITDA estimates.
Michael Jardon, Chief Executive Officer, commented, “Our second quarter results reflect a good sequential increase coming out of a seasonally low first quarter. This is despite the impacts caused by the Middle East conflict that tempered our second quarter results."
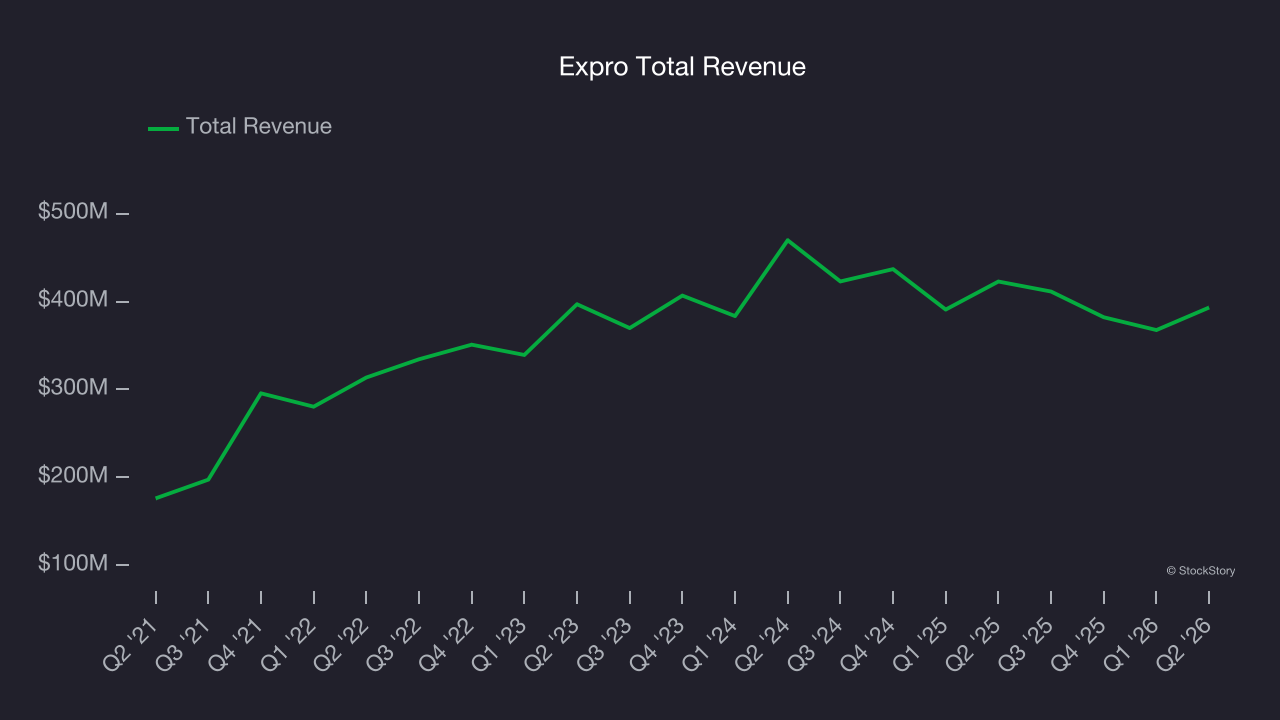
Interestingly, the stock is up 3.5% since reporting and currently trades at $16.22.
Read our full report on Expro here, it’s free.
Best Q2: NESR (NASDAQ: NESR)
Operating across 16 countries from Algeria to Indonesia, NESR (NASDAQ: NESR) provides oilfield services like hydraulic fracturing, cementing, and drilling to oil and gas companies.
NESR reported revenues of $520.8 million, up 59.1% year on year, outperforming analysts’ expectations by 17.8%. The business had an incredible quarter with a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
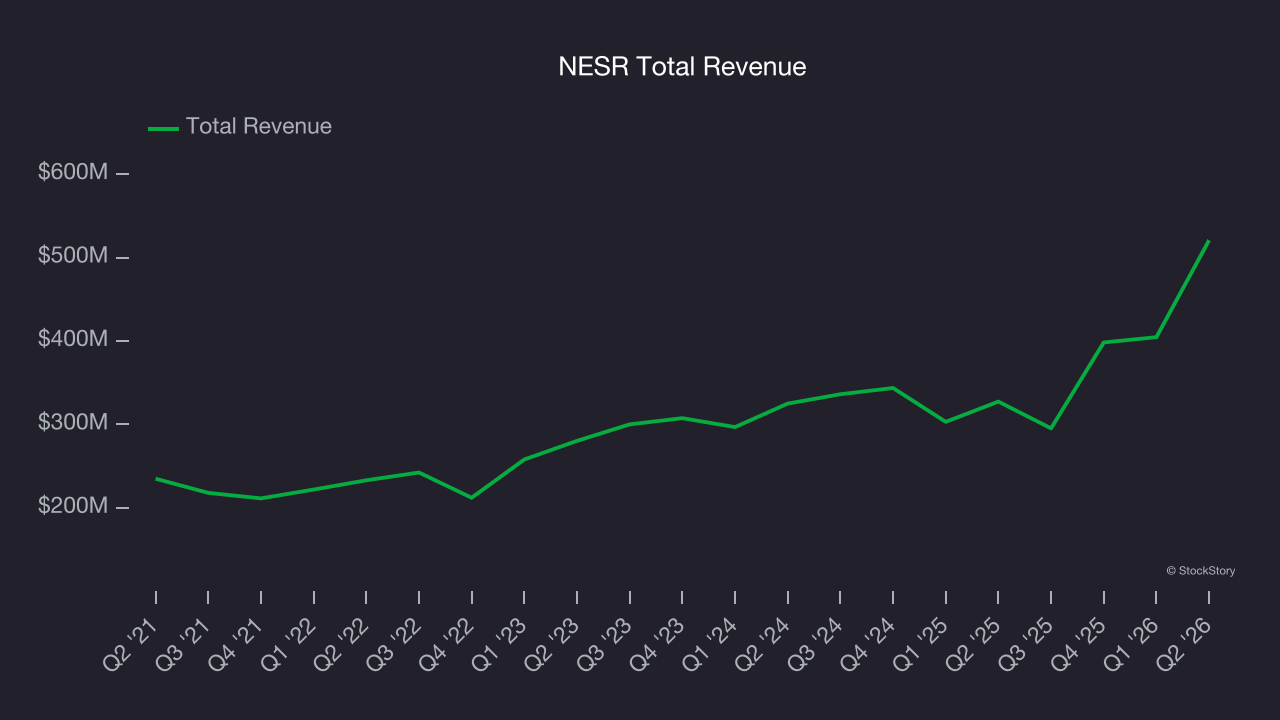
NESR achieved the fastest revenue growth in the group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 19.7% since reporting. It currently trades at $23.30.
Is now the time to buy NESR? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: ProPetro (NYSE: PUMP)
Operating exclusively in the Permian Basin—one of America's most prolific oil-producing regions—ProPetro (NYSE: PUMP) provides hydraulic fracturing services that pump high-pressure fluid and sand into oil wells to release trapped hydrocarbons.
ProPetro reported revenues of $305.8 million, down 6.2% year on year, falling short of analysts’ expectations by 1.6%. It was a disappointing quarter as it posted a significant miss of analysts’ EBITDA estimates and a significant miss of analysts’ EPS estimates.
As expected, the stock is down 13.5% since the results and currently trades at $9.22.
Read our full analysis of ProPetro’s results here.
TechnipFMC (NYSE: FTI)
Operating a fleet of 16 specialized vessels that install equipment on the seafloor, TechnipFMC (NYSE: FTI) designs and manufactures subsea systems that control the flow of oil and natural gas from the ocean floor to processing facilities.
TechnipFMC reported revenues of $2.76 billion, up 9% year on year. This number beat analysts’ expectations by 3.5%. It was a very strong quarter as it also put up a beat of analysts’ EPS estimates and a decent beat of analysts’ EBITDA estimates.
The stock is down 2.9% since reporting and currently trades at $69.62.
Read our full, actionable report on TechnipFMC here, it’s free.
Halliburton (NYSE: HAL)
Behind nearly every oil and gas well drilled worldwide, Halliburton (NYSE: HAL) provides drilling, completion, and production services that help oil and gas companies extract hydrocarbons from underground reservoirs.
Halliburton reported revenues of $5.71 billion, up 3.7% year on year. This result topped analysts’ expectations by 3.6%. Overall, it was a very strong quarter as it also produced a beat of analysts’ EPS estimates.
The stock is down 7.5% since reporting and currently trades at $32.48.
Read our full, actionable report on Halliburton here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Growth Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.