What a fantastic six months it’s been for Matson. Shares of the company have skyrocketed 41.9%, hitting $226.89. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy Matson, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Matson Not Exciting?
We’re happy investors have made money, but we’re passing on Matson for now. Here are three reasons why MATX doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
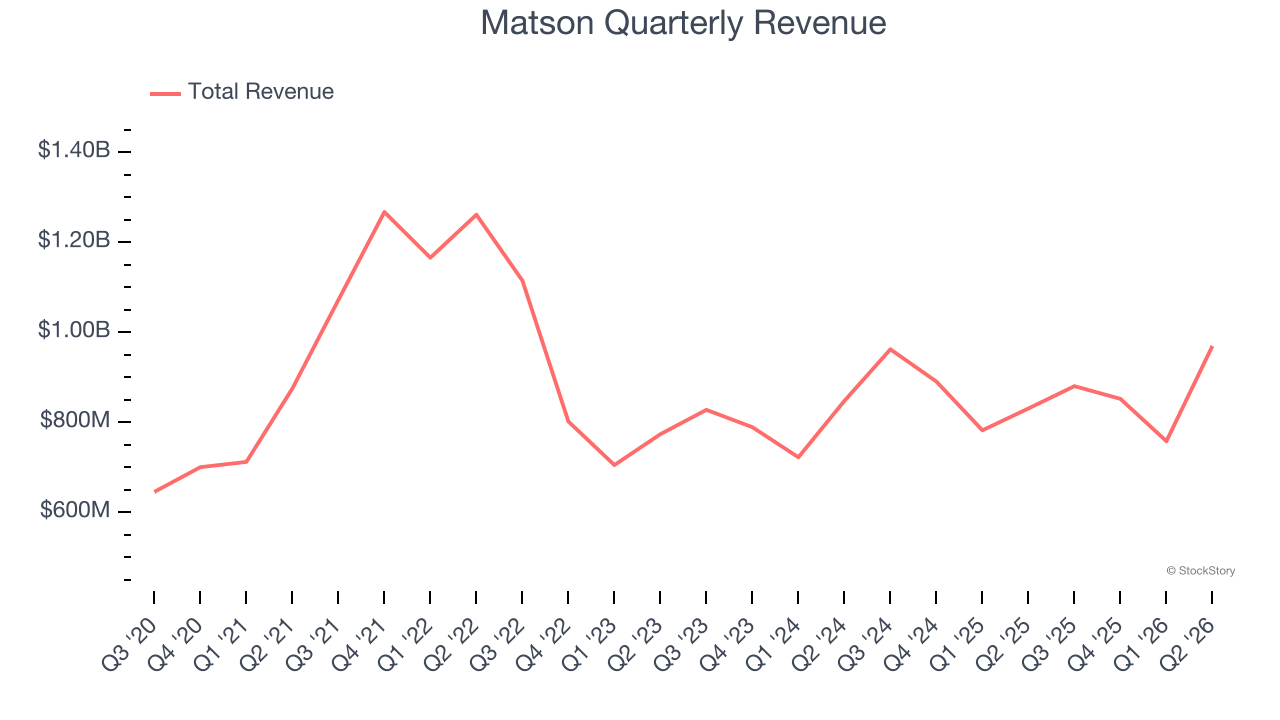
Reviewing a company’s long-term sales performance reveals insights into its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Unfortunately, Matson’s 3.4% annualized revenue growth over the last five years was sluggish. This fell short of our benchmark for the industrials sector.
2. Free Cash Flow Margin Dropping
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
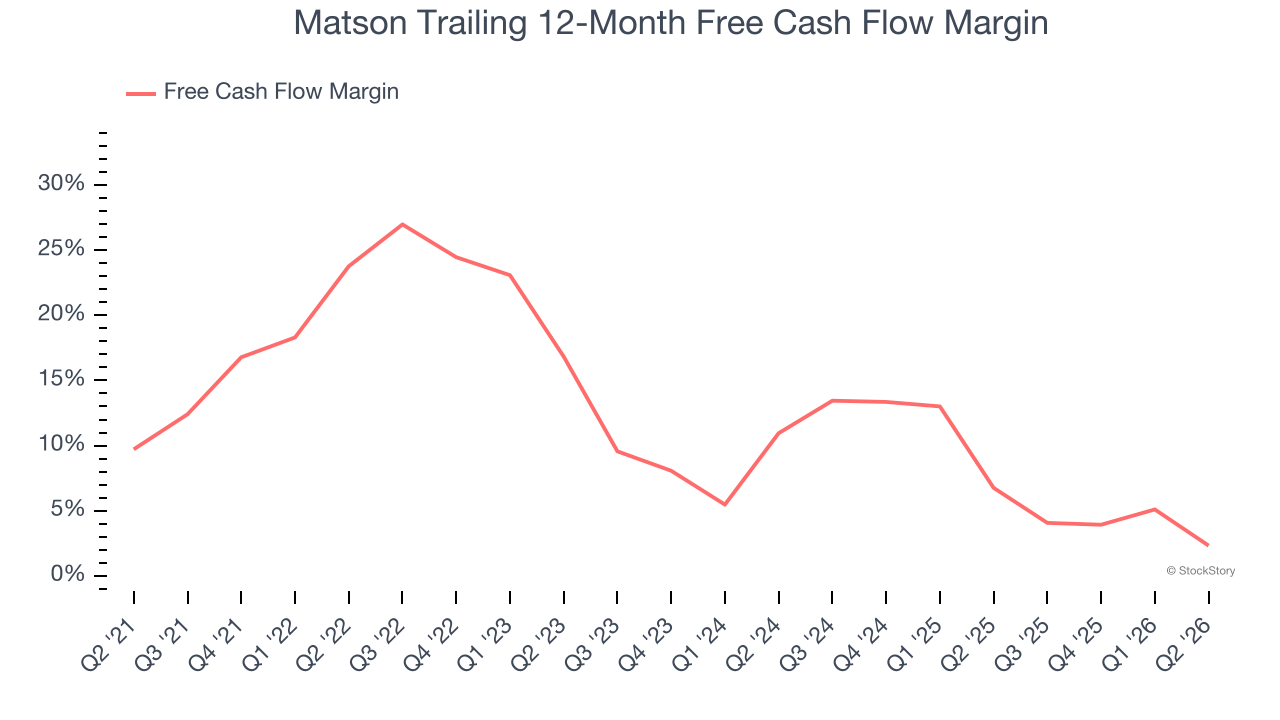
As you can see below, Matson’s margin dropped by 21.4 percentage points over the last five years. Continued declines could signal it is in the middle of an investment cycle. Matson’s free cash flow margin for the trailing 12 months was 2.3%.
3. New Investments Fail to Bear Fruit as ROIC Declines
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
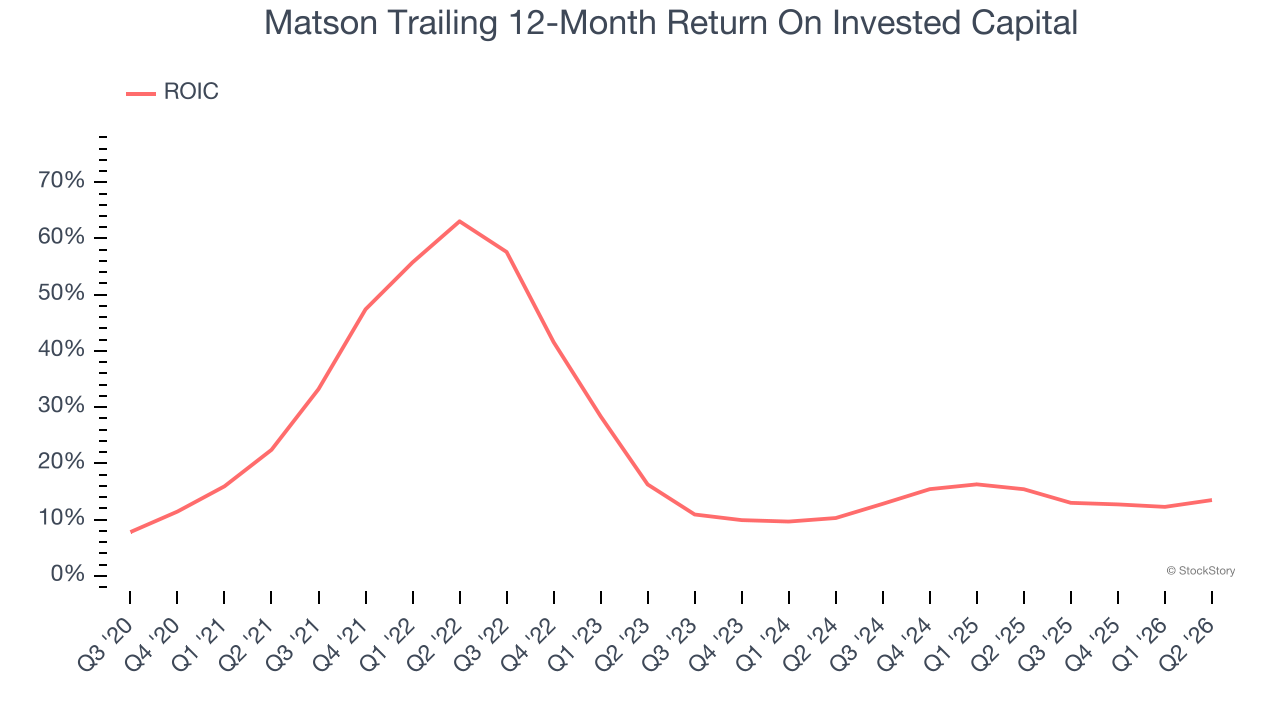
Over the last few years, Matson’s ROIC has unfortunately decreased significantly. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Matson’s business quality ultimately falls short of our standards. Following the recent surge, the stock trades at 14× forward P/E (or $226.89 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re fairly confident there are better stocks to buy right now. We’d recommend looking at one of Charlie Munger’s all-time favorite businesses.
Stocks We Like More Than Matson
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.